
Updated:
Get Form Now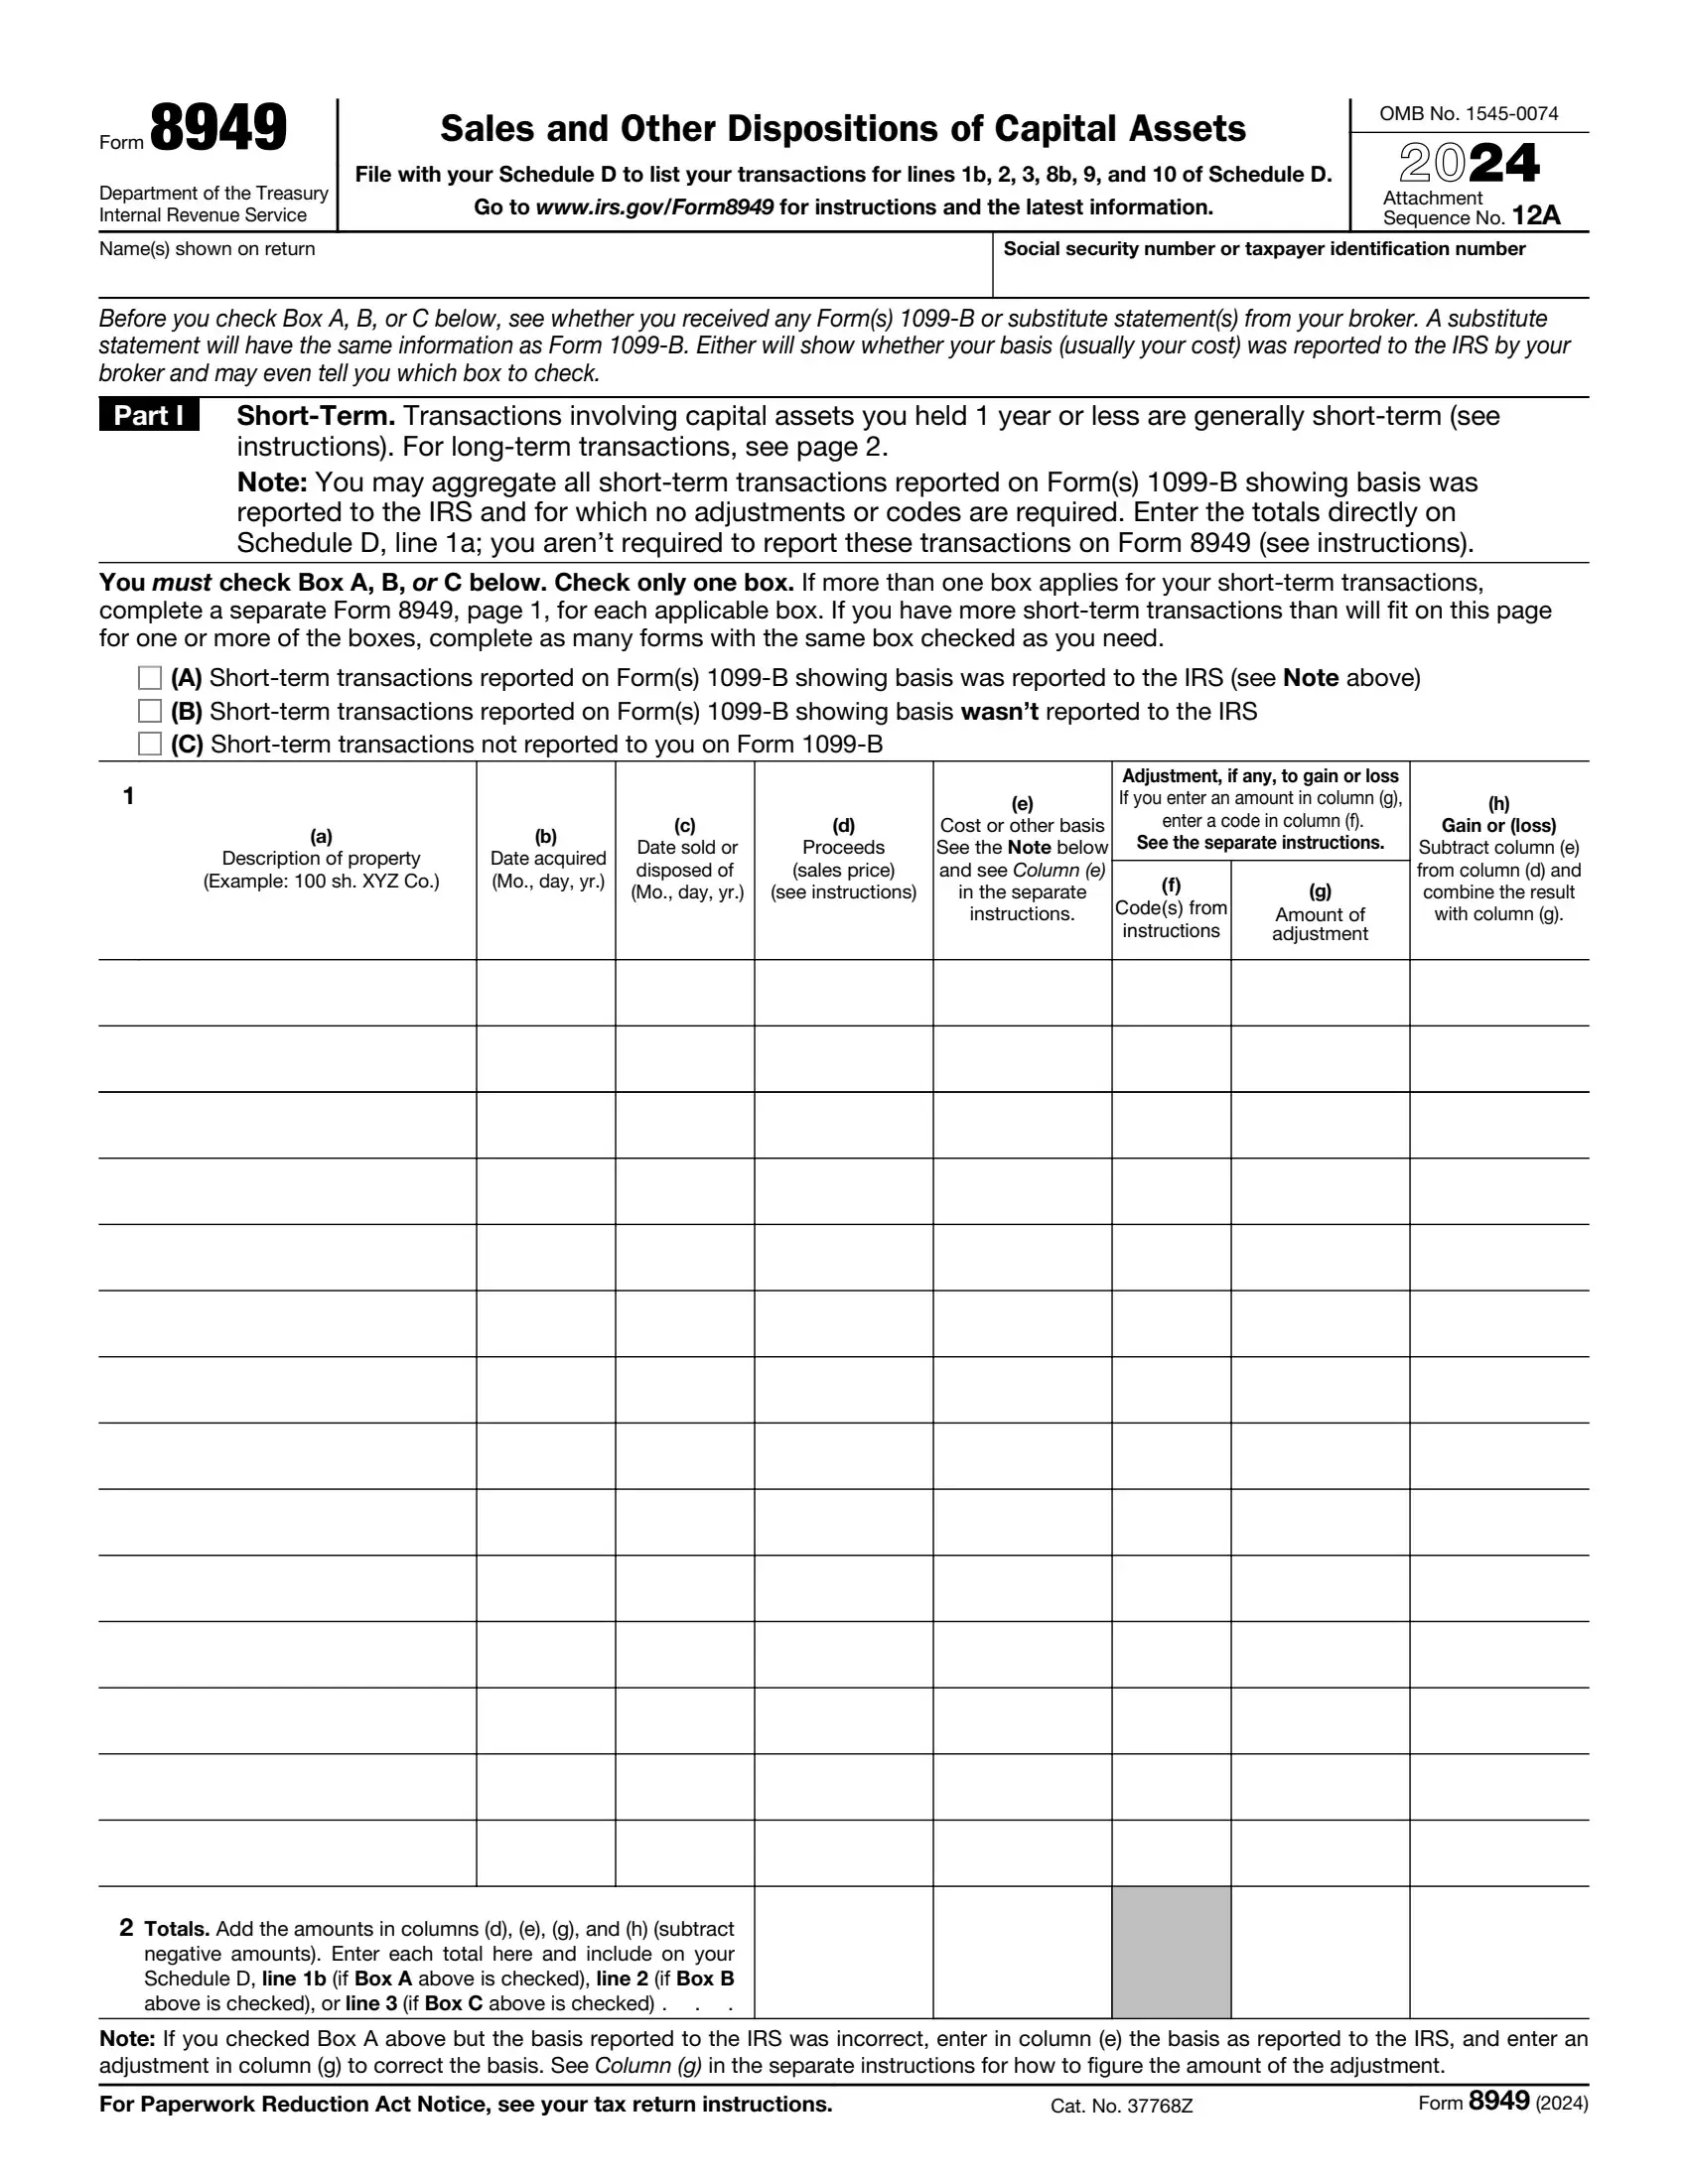
IRS Form 8949 is a tax form that taxpayers use to report the sale or exchange of capital assets that are not reported on other forms. Examples include stocks, bonds, real estate, and other investments. The form is essential for calculating capital gains or losses, which are then transferred to Schedule D (Form 1040) and used to determine the taxpayer’s tax liability. Information required on Form 8949 includes:
Taxpayers use Form 8949, titled “Sales and Other Dispositions of Capital Assets,” to detail each transaction individually, allowing for adjustments such as market discounts, nondeductible losses, and wash sale losses. This detailed reporting ensures accurate calculation of the capital gains tax owed, reflecting the taxpayer’s investment activity throughout the year.
Other IRS Forms for Business
The IRS requires businesses to report information on financial transactions and actions they take through their operation. Find out more about similar IRS forms on our other pages.
The paper is useful for a person who got Form 1099. The last is a state record that any company or individual, excluding your employer, gave you money for some object. Usually, the payers themselves submit Form 1099. Then it goes to the person who received the number of funds and at the same time to the IRS.
Who is the payer? It may be the bank that paid a client the benefit on their deposit or a client of a freelancer who paid him money. Form 1099 contains your SSN or taxpayer ID, so the IRS keeps records of such transactions and knows that you received the money.
Form 1099 does not mean that you are obliged to send the tax on this profit. If you have deductions that offset your income, then you do not have to pay tax. Even the gain from the sale of a private house is not always taxed, so often the Form 1099 is just an official statement of the transfer. The document does not exist to force a person to pay a tax but to keep records of profits and expenses annually.
There are many varieties of this document (they differ in the index after the form number), and we do not intend to consider them here. It is important to note that filling out Form 8949 often follows receiving you have owned for a period of less than one year), while the second one deals with long-term transactions (with assets that you held for more than a year). Form 1099 provides information about the type of transfer if it is unknown.
The form requires you to fill in a couple of lines, check the box, and complete the table. This can be done via our online form builder that is more convenient than the printed version of the document. Next, see our short guide for filling out the form.
Enter the basic data.
Enter the name listed on the return and identification information such as your taxpayer ID or social security number.

Specify the transaction type.
Sections A-C of the first part are intended for short-term transfers.

Items D-F of the second part concerns long-term ones.

Fill in the primary data in the table.
Most likely, you will not have to adjust the data in columns (a) – (c). The description of the object is based on the information provided in Form 1099. The dates of selling and buying are indicated at the same place.

Complete the other columns.
Specify the price for which the object was sold in column (d). Enter the amount corresponding to the cost or other basis (e). In column (g), you can give the adjustments that you think are necessary. Finally, in column (h), specify profit or loss.

The IRS instruction that accompanies the document will help you better understand the calculations.
Calculate the total sum.
At the bottom, enter the total count for each column specified in the document.

Copy the data to Schedule D.
Enter the total amount from columns (d), (e), (g), and (h) on the first line of Form 1040 if you selected A, on the second line if you selected B, and on the third line if you selected C.

Here is the correspondence of the form lines for long-term operations (Part two Form 8949).

What it is: Form 8949, Sales and Other Dispositions of Capital Assets: use Form 8949 to report sales and exchanges of capital assets.[2]
Where and when to file: File Form 8949 with the Schedule D for the return you are filing.[2]
Individuals use Form 8949 to report the sale or exchange of a capital asset reported on a Form 1099-K, Form 1099-B, or Form 1099-DA, and the sale or exchange of a capital asset not reported on another form or schedule.[2]
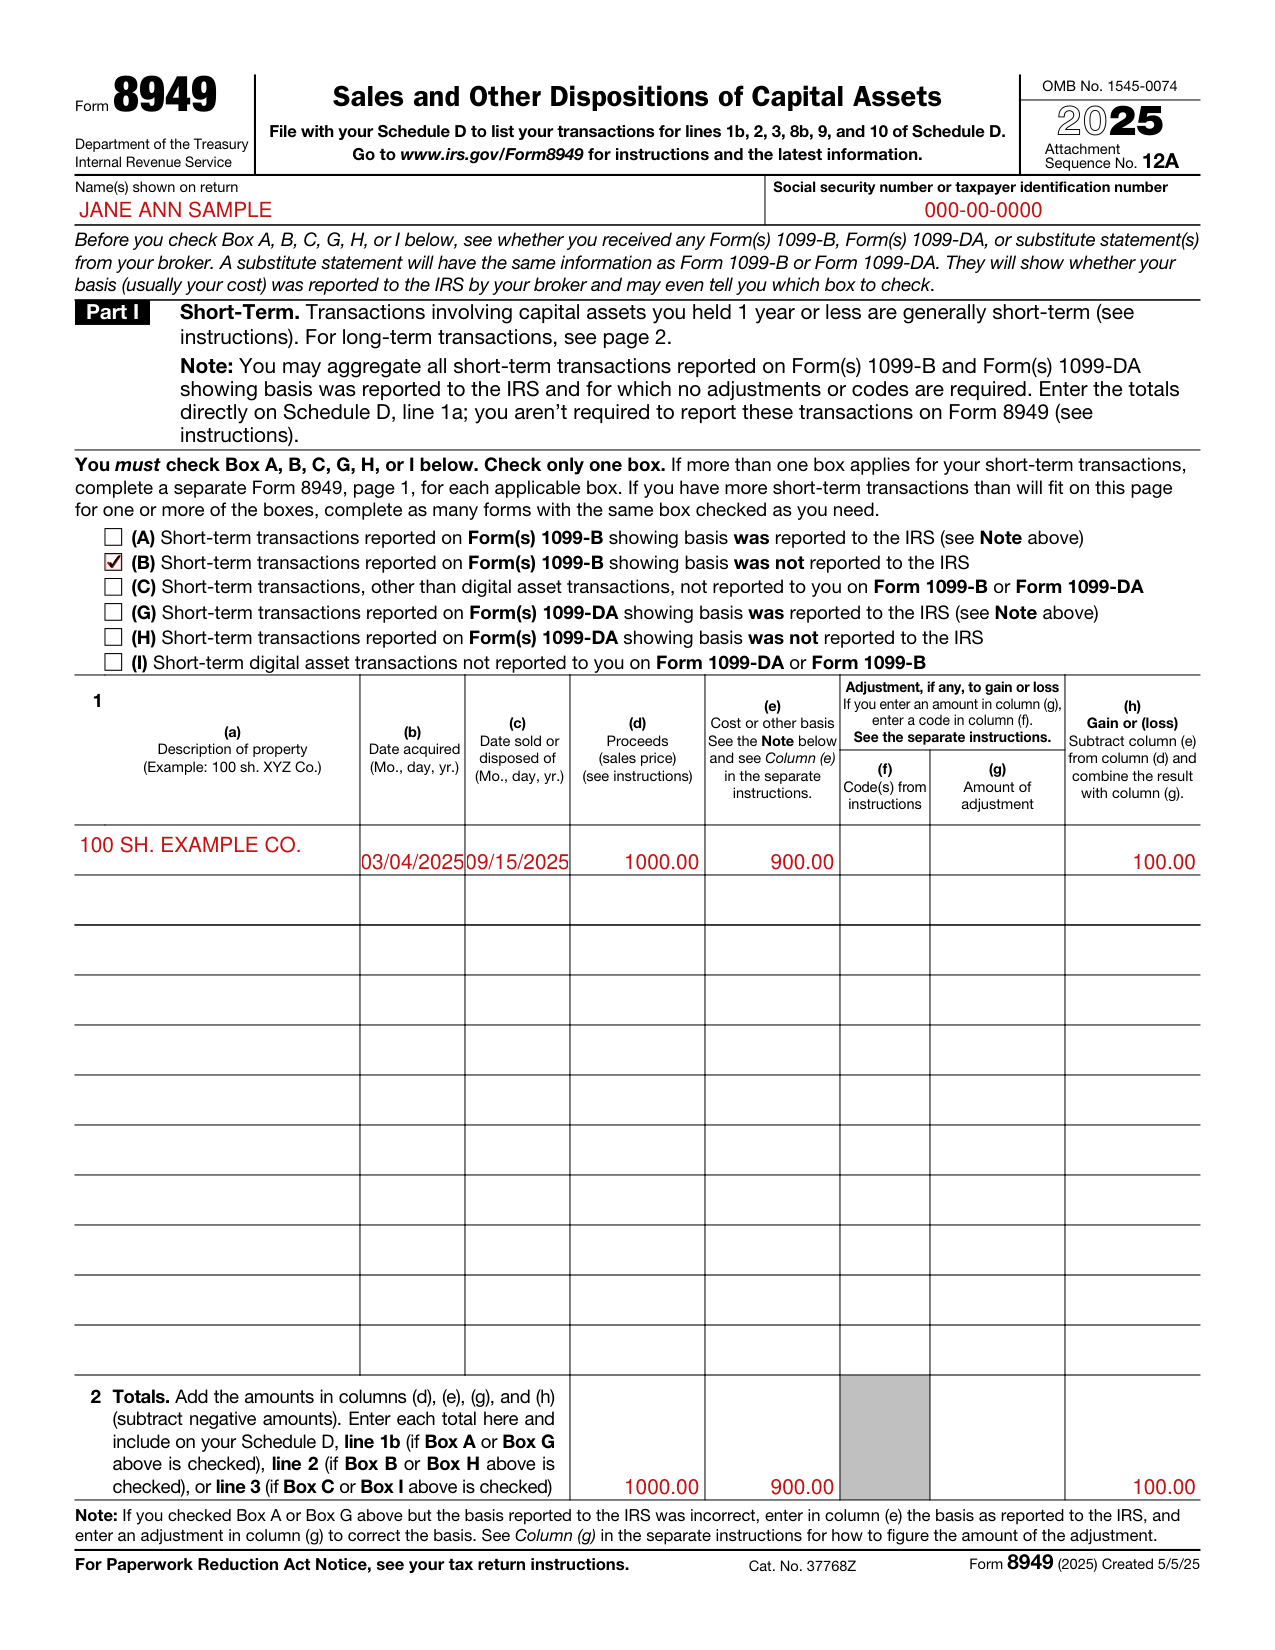

Enter the name(s) shown on the return and the social security number or taxpayer identification number.
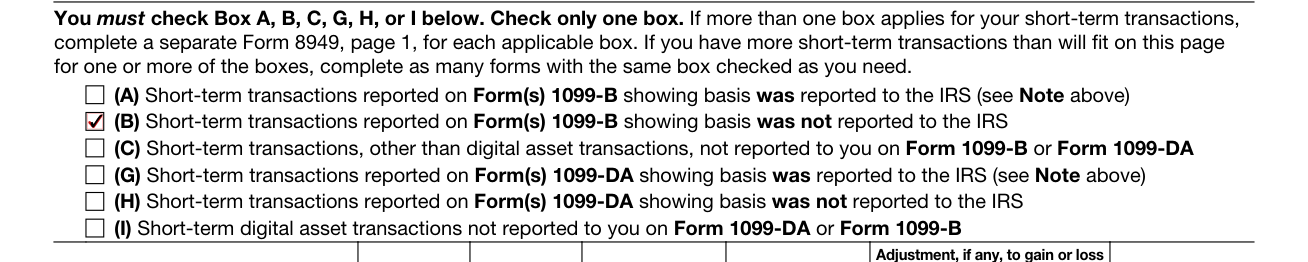
The holding period for short-term capital gains and losses is generally 1 year or less.
You must check Box A, B, C, G, H, or I. Check only one box. If more than one box applies for your short-term transactions, complete a separate Form 8949, page 1, for each applicable box. If you have more short-term transactions than will fit on page 1 for one or more of the boxes, complete as many forms with the same box checked as you need.
Box A or Box G: report on Part I with box A or box G checked all short-term transactions reported to you on Form 1099-B or Form 1099-DA (or substitute statement) with an amount shown for cost or other basis unless the statement indicates that amount wasn't reported to the IRS.
Box B or Box H: report on Part I with box B or box H checked all short-term transactions reported to you on Form 1099-B or Form 1099-DA (or substitute statement) without an amount shown for cost or other basis or showing that cost or other basis wasn't reported to the IRS.
Box C or Box I: use it when you didn't receive a Form 1099-B or Form 1099-DA (or substitute statement).
Do not use box C to report digital asset transactions. Use box I.[2]
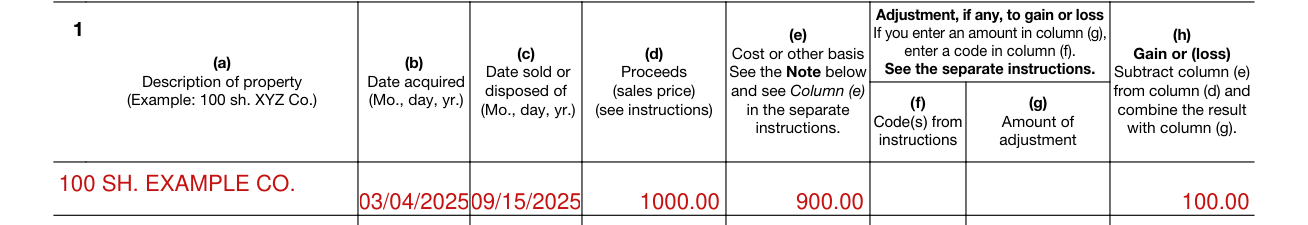
Box 1, Column (a): for stock, include the number of shares.
Box 1, Column (b): enter the date you acquired the property. Enter the trade date for stocks and bonds you purchased on an exchange or over-the-counter market.
Box 1, Column (c): enter the date you sold or disposed of the property. Use the trade date for stocks and bonds traded on an exchange or over-the-counter market.
Box 1, Column (d): if you received a Form 1099-B, Form 1099-DA, or Form 1099-S (or substitute statement) for a transaction, enter in column (d) the proceeds shown on the form or statement you received.
If you didn't receive a Form 1099-B, Form 1099-DA, or Form 1099-S (or substitute statement) for a transaction, enter in column (d) the net proceeds. The net proceeds equal the gross proceeds minus any selling expenses (such as broker's fees, commissions, and state and local transfer taxes).
Column (e): if Form 1099-B or Form 1099-DA (or substitute statement) shows that the cost or other basis was reported to the IRS, always report the basis shown on that form (or statement) in column (e).[2]
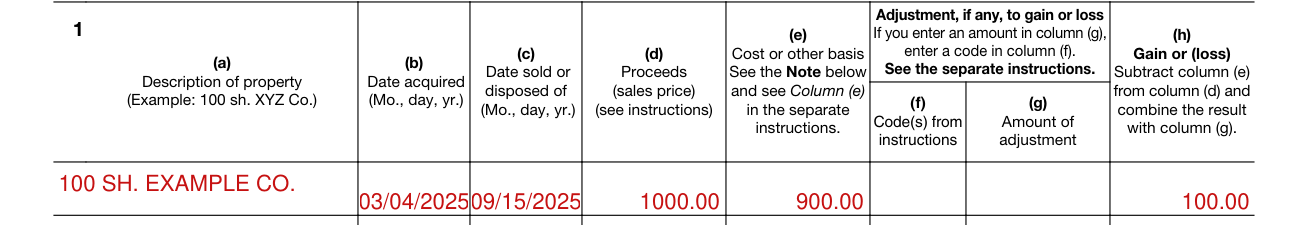
How to complete Form 8949, columns (f) and (g): for most transactions, you don't need to complete columns (f) and (g) and can leave them blank.
Enter a code in column (f) to explain the adjustment.
Enter in column (g) any necessary adjustments to gain (or loss). Enter negative amounts in parentheses.[2]
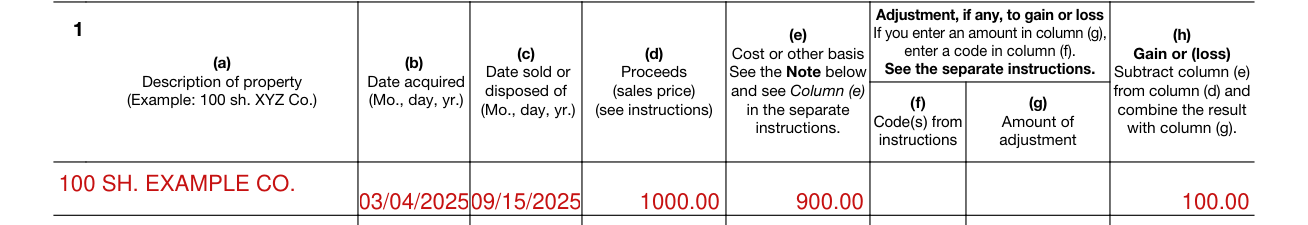
Figure gain (or loss) on each row. First, subtract the cost or other basis from the proceeds (sales price). Then take into account any adjustments. Enter the gain (or loss) in column (h). Enter negative amounts in parentheses.[2]
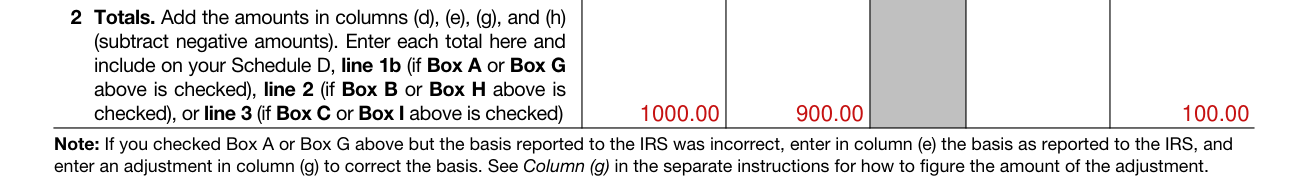
Add the amounts in columns (d), (e), (g), and (h) (subtract negative amounts). Enter each total on the Totals line and include it on your Schedule D, line 1b (if Box A or Box G is checked), line 2 (if Box B or Box H is checked), or line 3 (if Box C or Box I is checked).
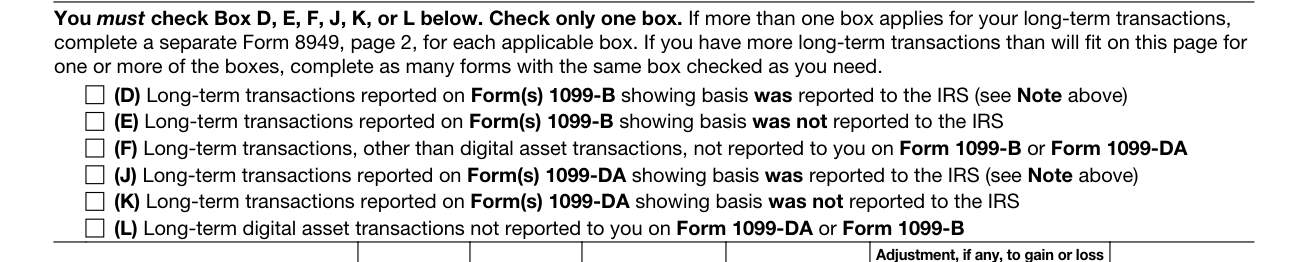
Part II, Long-Term: transactions involving capital assets you held more than 1 year are generally long-term (see instructions).
You must check Box D, E, F, J, K, or L. Check only one box. If more than one box applies for your long-term transactions, complete a separate Form 8949, page 2, for each applicable box.
Box D or Box J: report on Part II with box D or box J checked all long-term transactions reported to you on Form 1099-B or Form 1099-DA (or substitute statement) with an amount shown for cost or other basis unless the statement indicates that amount wasn't reported to the IRS.
Box E or Box K: report on Part II with box E or box K checked all long-term transactions reported to you on Form 1099-B or Form 1099-DA (or substitute statement) without an amount shown for cost or other basis or showing that cost or other basis wasn't reported to the IRS.
Box F or Box L: report on Part II with box F or box L checked all long-term transactions for which you can't check box D, E, J, or K because you didn't receive a Form 1099-B or Form 1099-DA (or substitute statement). Do not use box F to report digital asset transactions. Use box L.[2]
Form 8949 isn't required for certain transactions: you may be able to aggregate them and report them directly on either line 1a (for short-term transactions) or line 8a (for long-term transactions) of Schedule D. This option applies only to transactions (other than sales of collectibles) for which you received a Form 1099-B (or substitute statement) that shows basis was reported to the IRS and doesn't show any adjustments in box 1f or 1g; the Ordinary box in box 2 on Form 1099-B isn't checked; you received a Form 1099-DA (or substitute statement) that shows basis was reported to the IRS and doesn't show any adjustments in box 1h or 1i; the Ordinary box in box 6 on Form 1099-DA isn't checked; you don't need to make any adjustments to the basis or type of gain (or loss) reported on Form 1099-B or Form 1099-DA (or substitute statement), or to your gain (or loss); and you aren't electing to defer income due to an investment in a QOF and aren't terminating deferral from an investment in a QOF.[2]
If you checked Box A or Box G but the basis reported to the IRS was incorrect, enter in column (e) the basis as reported to the IRS, and enter an adjustment in column (g) to correct the basis.
File Form 8949 with the Schedule D for the return you are filing.[2]
[1] Form 8949 (2025), Sales and Other Dispositions of Capital Assets, Internal Revenue Service (the Official source link on this page).
[2] Instructions for Form 8949 (2025), Internal Revenue Service.