
Updated:
Get Form Now
IRS Form 8889 is a U.S. tax form used for Health Savings Accounts (HSAs). This form is necessary for taxpayers with an HSA who must report contributions to the account, calculate the tax deduction, and report distributions (withdrawals) from the HSA.
Form 8889 also helps determine if the distributions were used for qualified medical expenses, which are tax-free, or for other purposes, which may be taxable and subject to additional penalties. By filling out Form 8889, taxpayers ensure that they comply with the tax rules related to HSAs, maximize their deductions, and accurately report any taxable distributions.
What it is: Form 8889, Health Savings Accounts (HSAs), attaches to Form 1040, 1040-SR, or 1040-NR. Use Form 8889 to report contributions to your HSA and report distributions from HSAs.[2]
You must file Form 8889 if any of the following applies: you, your employer, or someone else made contributions to your HSA; your HSA made a distribution; you failed to be an "eligible individual" during a "testing period" and must recognize income; or you acquired an interest in an HSA because of the death of the account beneficiary.[2]
Complete Form 8853, Archer MSAs and Long-Term Care Insurance Contracts, if required.
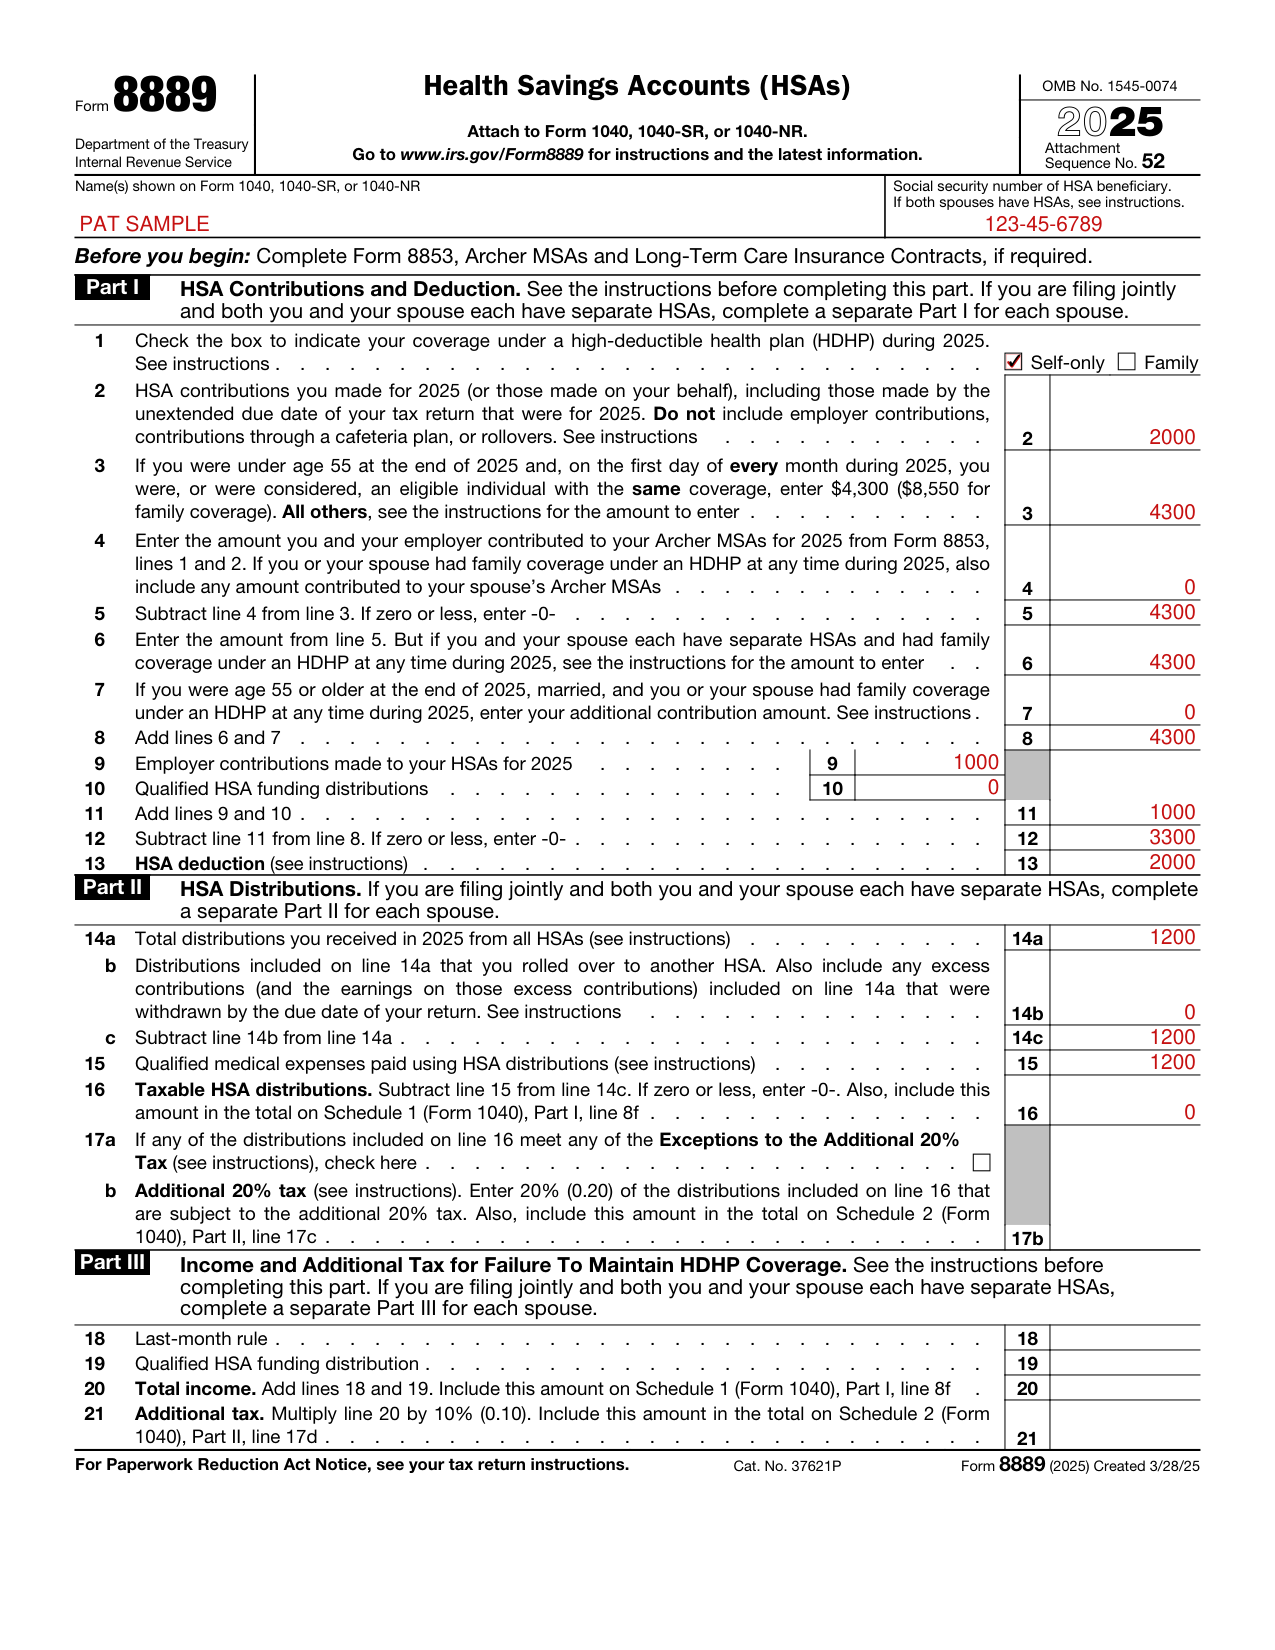
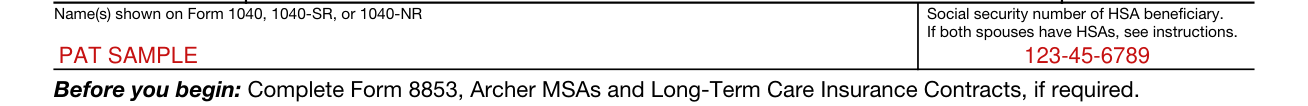
Enter your name(s) as shown on Form 1040, 1040-SR, or 1040-NR and the SSN of the HSA account beneficiary. If both spouses have HSAs, see instructions.
If married filing jointly and both you and your spouse have HSAs, complete a separate Form 8889 for each of you.[2]
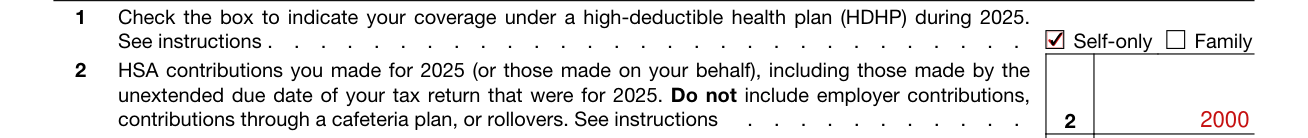
Check the box to indicate your coverage under a high-deductible health plan (HDHP) during 2025.
Line 1: If you were covered, or considered covered, by a self-only HDHP and a family HDHP at different times during the year, check the box for the plan that was in effect for a longer period.
If, on the first day of the last month of your tax year (December 1 for most taxpayers), you had family coverage, check the "family" box.[2]
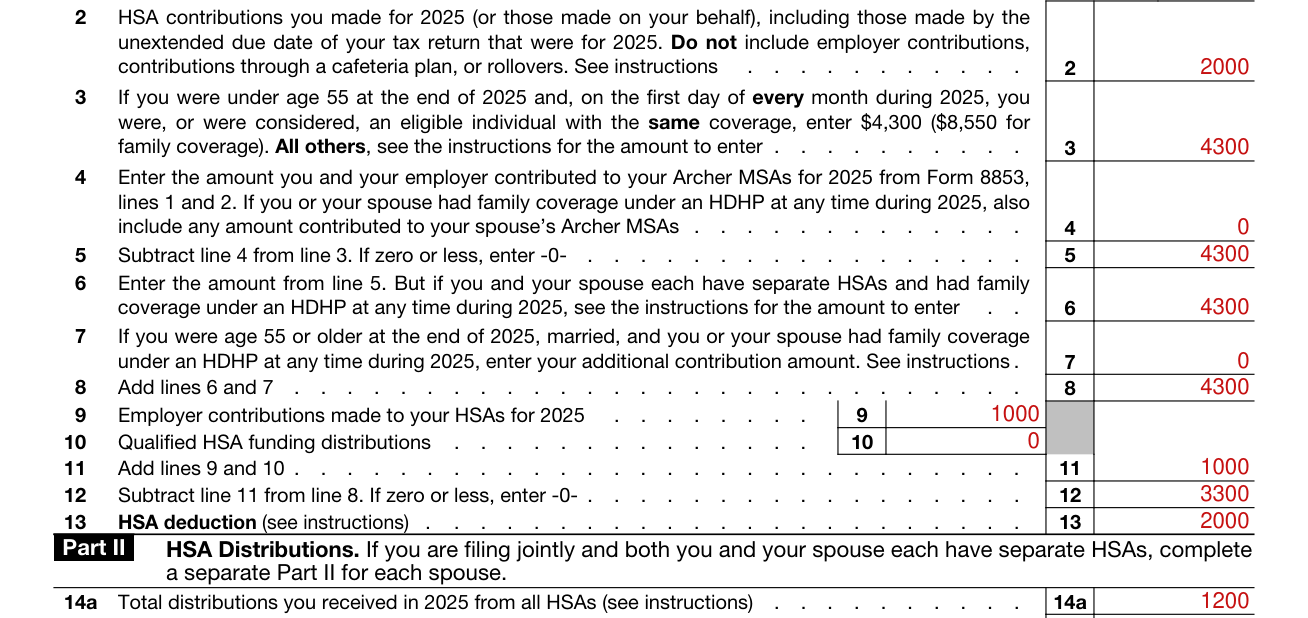
Part I is HSA Contributions and Deduction. If you are filing jointly and both you and your spouse each have separate HSAs, complete a separate Part I for each spouse.
Line 2: Include on line 2 only those amounts you, or others on your behalf, contributed to your HSA for 2025. Do not include employer contributions, contributions through a cafeteria plan, or rollovers.
Line 3: If you were under age 55 at the end of 2025 and, on the first day of every month during 2025, you were, or were considered, an eligible individual with the same coverage, enter $4,300 ($8,550 for family coverage). All others, see the instructions for the amount to enter (checked October 31, 2026).
Use the family coverage amount if you or your spouse had an HDHP with family coverage. Disregard any plan with self-only coverage.
Line 4: Enter the amount you and your employer contributed to your Archer MSAs for 2025 from Form 8853, lines 1 and 2.
Line 5: Subtract line 4 from line 3. If zero or less, enter -0-.
Line 6: Enter the amount from line 5. But if you and your spouse each have separate HSAs and had family coverage under an HDHP at any time during 2025, see the instructions for the amount to enter.
Line 7: If you were age 55 or older at the end of 2025, married, and you or your spouse had family coverage under an HDHP at any time during 2025, enter your additional contribution amount. See instructions.
Line 8: Add lines 6 and 7.
Line 9: Employer contributions (including employee payroll contributions through a cafeteria plan) include any amount an employer contributes to any HSA for you for 2025. These contributions should be shown on Form W-2, box 12, code W.
Line 10: A distribution from your traditional IRA or Roth IRA to your HSA in a direct trustee-to-trustee transfer is called an HSA funding distribution. Enter this amount on line 10.
Line 11: Add lines 9 and 10. Line 12: Subtract line 11 from line 8. If zero or less, enter -0-.
Line 13: Generally, enter the smaller of line 2 or line 12 on line 13 and on Schedule 1 (Form 1040), Part II, line 13.
However, if the amount on line 2 is more than the amount on line 13, you, your employer, or someone else contributed more to your HSA than is allowable and you may have to pay an additional tax on the excess contributions.[2]
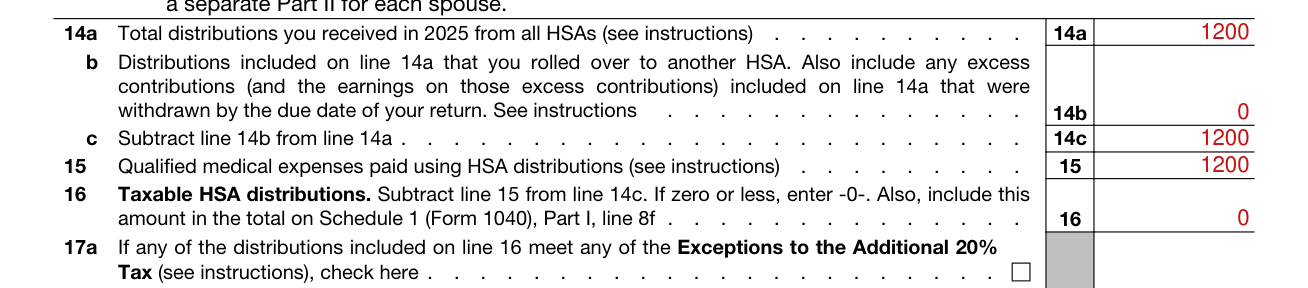
Line 14a: Enter the total distributions your HSAs made in 2025. These amounts should be shown on Form 1099-SA, box 1.
Line 14b: Include on line 14b any distributions your HSA made in 2025 that qualified as a rollover contribution to another HSA. Also include any excess contributions (and the earnings on those excess contributions) included on line 14a that were withdrawn by the due date, including extensions, of your return.
Line 14c: Subtract line 14b from line 14a.
Line 15: Only include on line 15 distributions from your HSA that were used to pay you for qualified medical expenses not reimbursed by insurance or other coverage and that you incurred after the HSA was established.
Line 16: Taxable HSA distributions. Subtract line 15 from line 14c. If zero or less, enter -0-. Also, include this amount in the total on Schedule 1 (Form 1040), Part I, line 8f.[2]
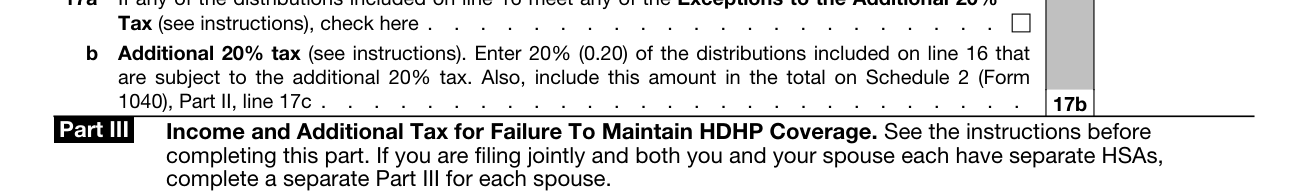
HSA distributions included in income (line 16) are subject to an additional 20% tax unless one of the following exceptions applies. If any of the exceptions apply to any of the distributions included on line 16, check the box on line 17a. Enter on line 17b only 20% (0.20) of any amount included on line 16 that does not meet any of the exceptions.
The additional 20% tax does not apply to distributions made after the account beneficiary dies, becomes disabled or turns age 65.[2]
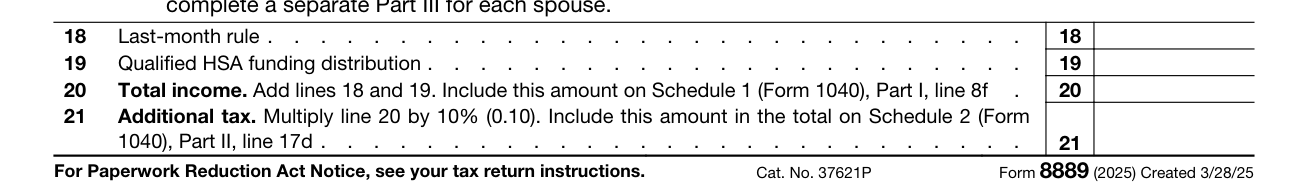
Line 18: Enter on line 18 the excess of the amount contributed over the redetermined amount.
Line 19: Enter the total of any qualified HSA funding distribution (see line 10).
Line 20: Total income. Add lines 18 and 19. Include this amount on Schedule 1 (Form 1040), Part I, line 8f.
Line 21: Additional tax. Multiply line 20 by 10% (0.10). Include this amount in the total on Schedule 2 (Form 1040), Part II, line 17d.[2]
If you and your spouse are both eligible individuals and either of you has an HDHP with family coverage, you both are treated as having only the family coverage plan. If both you and your spouse have HSAs, complete a separate Form 8889 for each spouse. Combine the amounts on line 13 of both Forms 8889 and enter this amount on Schedule 1 (Form 1040), line 13. Be sure to attach both Forms 8889 to your paper tax return.[2]
The testing period begins with the last month of your tax year and ends on the last day of the 12th month following that month (for example, December 1, 2025 - December 31, 2026). If you fail to remain an eligible individual during this period, other than because of death or becoming disabled, you will have to include in income the total contributions made that would not have been made except for the last-month rule.[2]
Form 8889, Health Savings Accounts (HSAs), attaches to Form 1040, 1040-SR, or 1040-NR. Use Form 8889 to report contributions to your HSA and report distributions from HSAs. Use Form 8889 to figure your HSA deduction and figure amounts you must include in income and additional tax you may owe if you fail to be an eligible individual.[2]
If you (or your spouse, if filing jointly) received HSA distributions in 2025, you must file Form 8889 with Form 1040, Form 1040-SR, or Form 1040-NR, even if you have no taxable income or any other reason for filing Form 1040, Form 1040-SR, or Form 1040-NR.[2]
Also, include amounts contributed for 2025 made in 2026 by the unextended deadline for filing your 2025 federal income tax return, April 15, 2026.[2]
[1] Form 8889 (2025), Health Savings Accounts (HSAs), Internal Revenue Service (the Official source link on this page).
[2] Instructions for Form 8889 (2025), Internal Revenue Service.