
Updated:
Get Form Now
Form 8840 is used by nonresident aliens to assert a closer connection to a foreign country than to the United States despite having spent a significant amount of time in the U.S. This form is relevant for individuals who need to determine their tax residency status under the substantial presence test. The substantial presence test calculates whether they have been in the U.S. enough days over three years to be considered a tax resident. Form 8840 allows eligible individuals to claim they are not U.S. tax residents due to closer connections to a foreign country where they have their tax home.
Form 8840 allows nonresident aliens to avoid being treated as U.S. residents for tax purposes, which can significantly impact their U.S. tax liabilities. By completing this form, individuals can demonstrate that their social, economic, and personal ties to another country are stronger than those to the U.S., thus exempting them from the need to report global income to the IRS.
Other IRS Forms for Individuals
If you are neither a U.S. citizen nor legal permanent resident, you might want to get familiar with some other IRS forms that might be of help to you.
What it is: Form 8840 is the Closer Connection Exception Statement for Aliens.
Where and when to file: If you are filing a 2025 Form 1040-NR, attach Form 8840 to it.
Use Form 8840 to claim the closer connection to a foreign country(ies) exception to the substantial presence test.
If you are an alien individual and you meet the closer connection exception to the substantial presence test, you must file Form 8840 with the IRS to establish your claim that you are a nonresident of the United States by reason of that exception.
Each alien individual must file a separate Form 8840 to claim the closer connection exception.
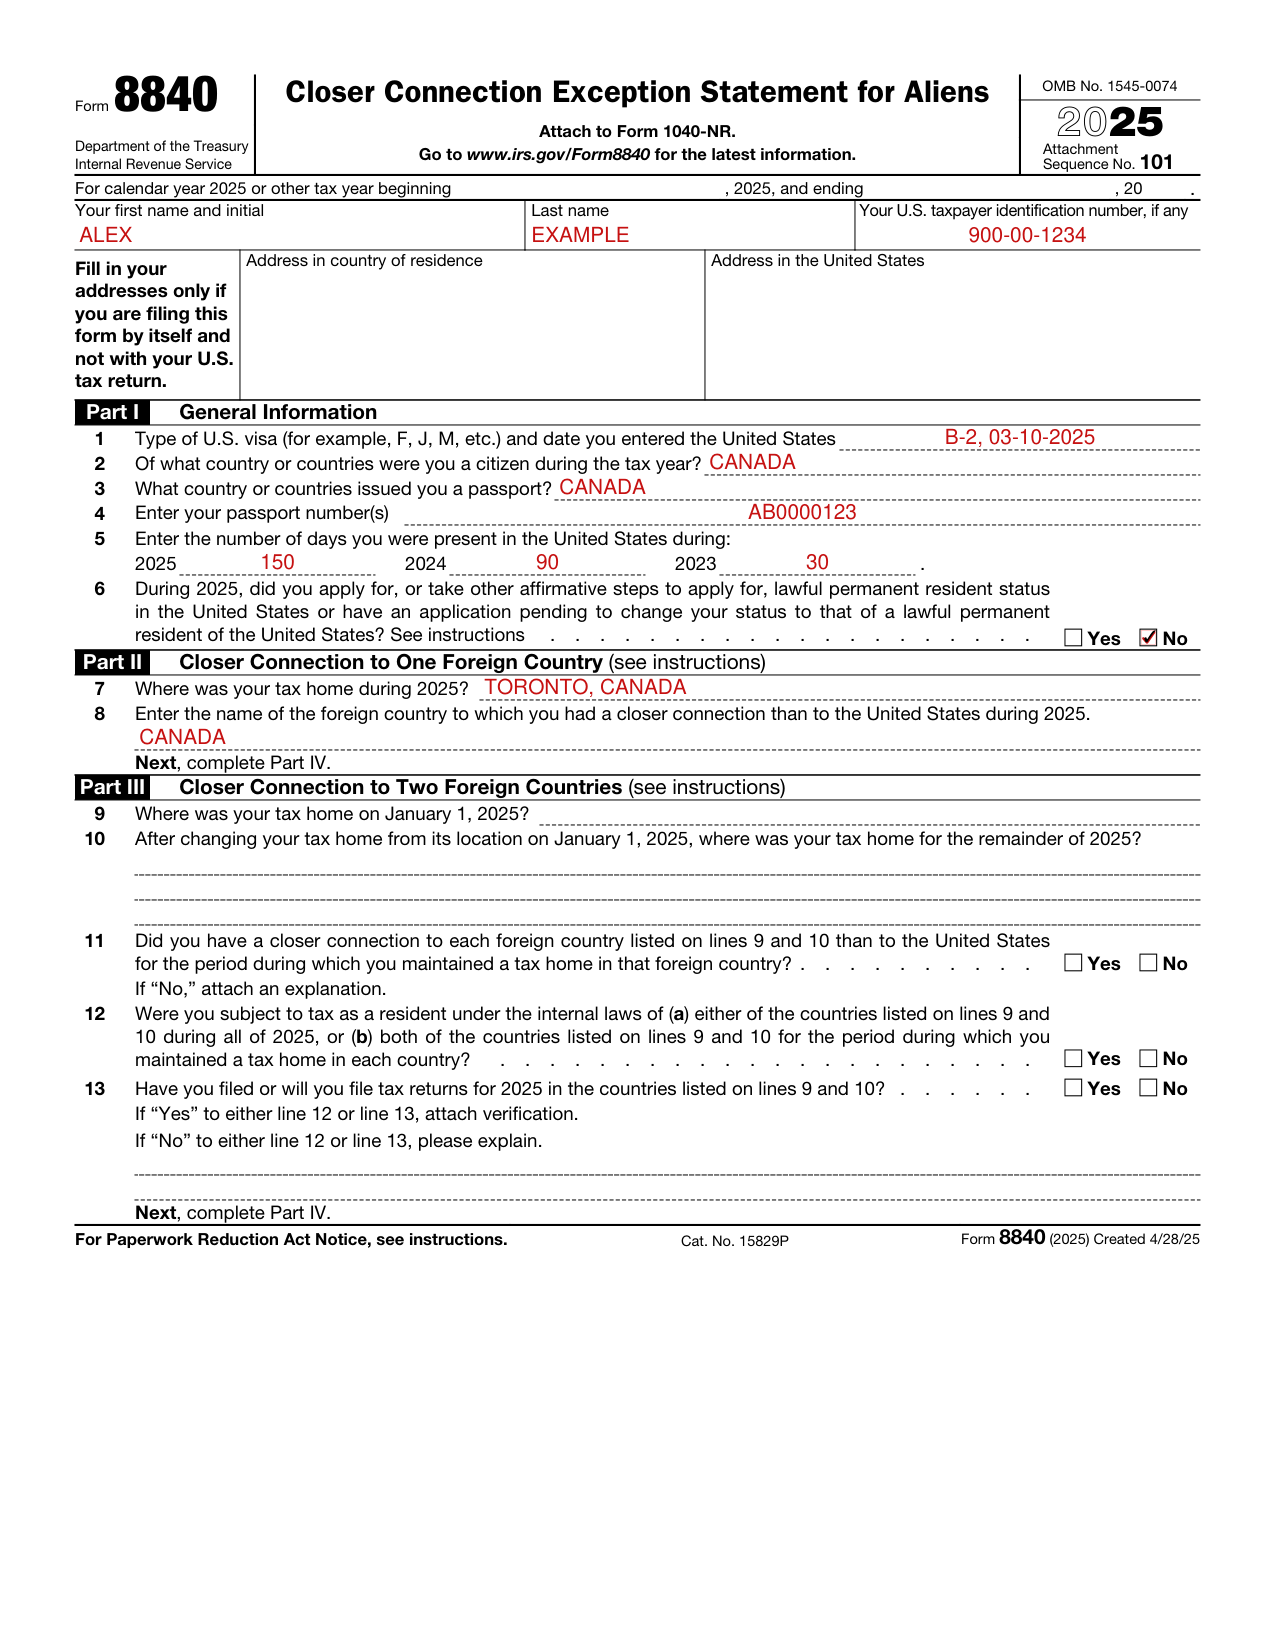

Enter your first name and initial, your last name and your U.S. taxpayer identification number, if any.
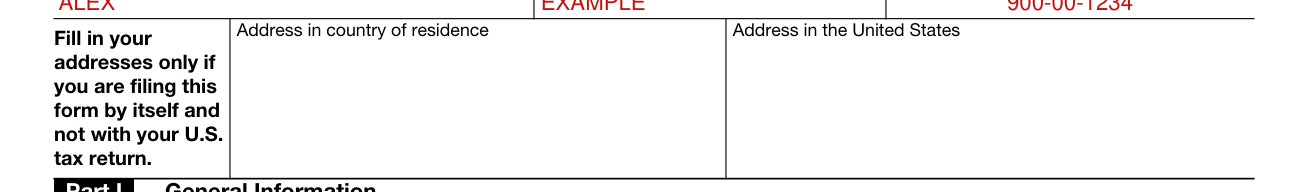
Fill in your addresses only if you are filing this form by itself and not with your U.S. tax return.
Even though you would otherwise meet the substantial presence test, you will not be treated as a U.S. resident for 2025 if: You were present in the United States for fewer than 183 days during 2025; You establish that, during 2025, you had a tax home in a foreign country; and You establish that, during 2025, you had a closer connection to one foreign country in which you had a tax home than to the United States, unless you had a closer connection to two foreign countries.

If you had a visa on the last day of the tax year, enter your visa type and the date you entered the United States.
If you do not have a visa, enter your U.S. immigration status on the last day of the tax year and the date you entered the United States.
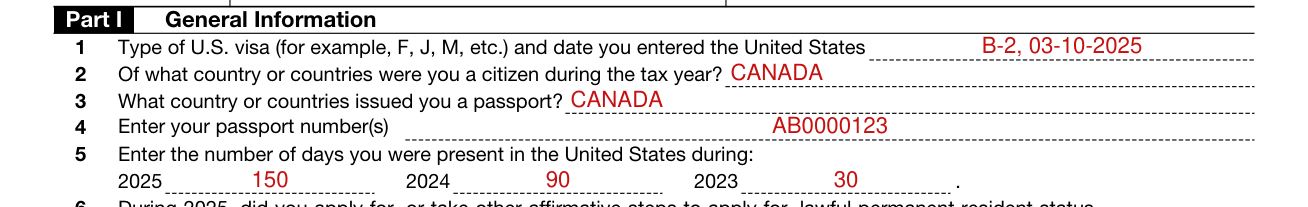
Of what country or countries were you a citizen during the tax year?
What country or countries issued you a passport? Enter your passport number(s).
Enter the number of days you were present in the United States during: 2025 2024 2023.
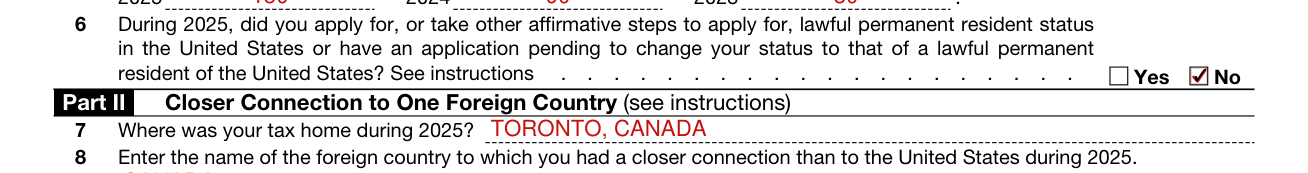
If you checked the “Yes” box on line 6, do not file Form 8840.
During 2025, did you apply for, or take other affirmative steps to apply for, lawful permanent resident status in the United States or have an application pending to change your status to that of a lawful permanent resident of the United States?
If you had a tax home in the United States at any time during the year, do not file Form 8840. You are not eligible for the closer connection exception. Otherwise, complete Part II or Part III (but not both) depending on the number of countries to which you are claiming a closer connection.
If you are claiming a closer connection to one country, complete Part II.
If you are claiming a closer connection to two countries, complete Part III.
After completing Part II or Part III, complete Part IV.
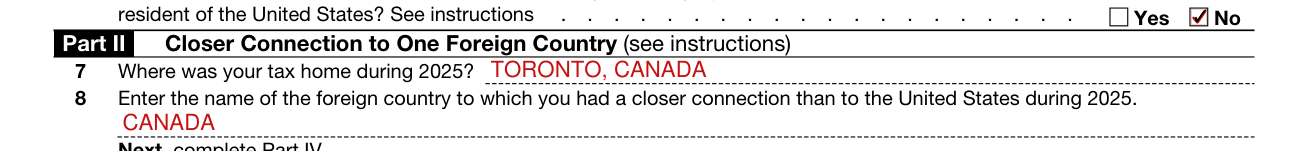
Your tax home is the general area of your main place of business, employment, or post of duty, regardless of where you maintain your family home.
Where was your tax home during 2025?
Enter the name of the foreign country to which you had a closer connection than to the United States during 2025.
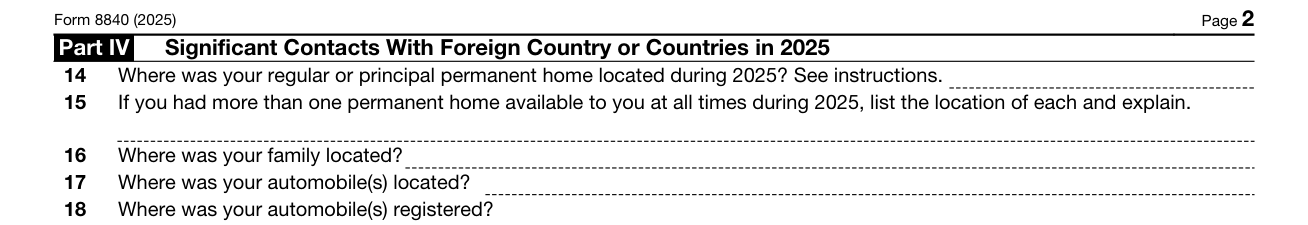
Form 8840 (2025) Part IV Significant Contacts With Foreign Country or Countries in 2025 14 Where was your regular or principal permanent home located during 2025?
A “permanent home” is a dwelling unit (whether owned or rented, and whether a house, an apartment, or a furnished room) that is available at all times, continuously and not solely for short stays.
15 If you had more than one permanent home available to you at all times during 2025, list the location of each and explain.
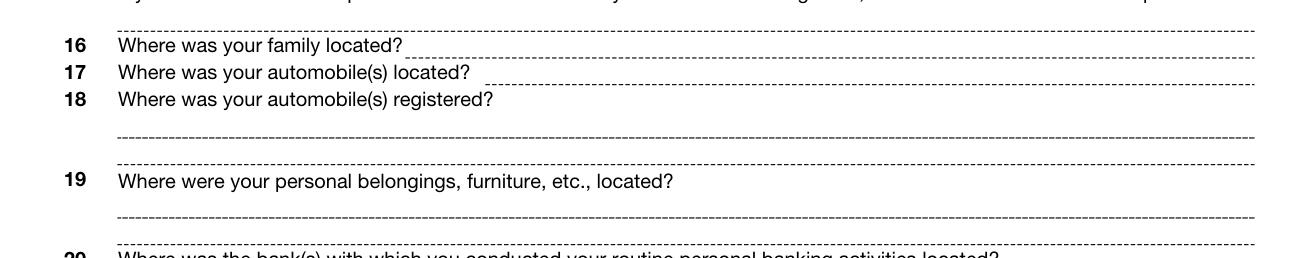
Where was your family located? Where was your automobile(s) located? Where was your automobile(s) registered?
Where were your personal belongings, furniture, etc., located?

Where was the bank(s) with which you conducted your routine personal banking activities located?
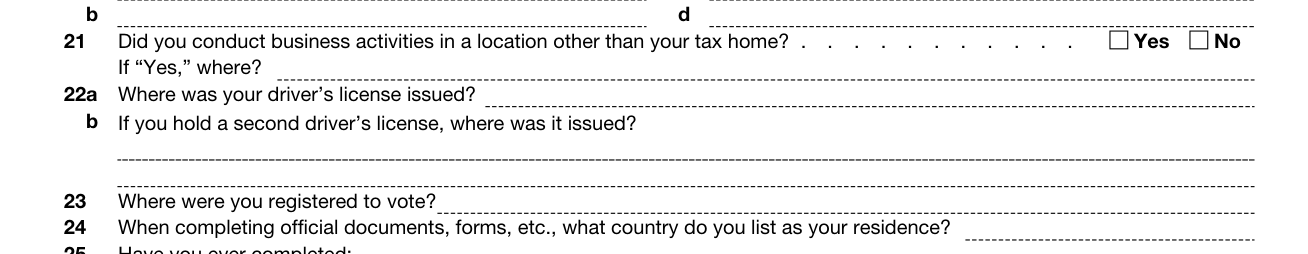
Did you conduct business activities in a location other than your tax home? If “Yes,” where?
Where was your driver's license issued? If you hold a second driver's license, where was it issued?
Where were you registered to vote? When completing official documents, forms, etc., what country do you list as your residence?
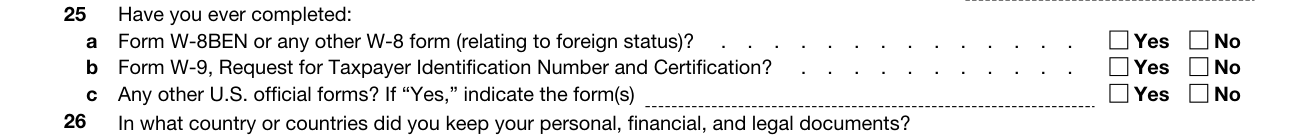
Have you ever completed: Form W-8BEN or any other W-8 form (relating to foreign status)? Form W-9, Request for Taxpayer Identification Number and Certification? Any other U.S. official forms? If “Yes,” indicate the form(s).
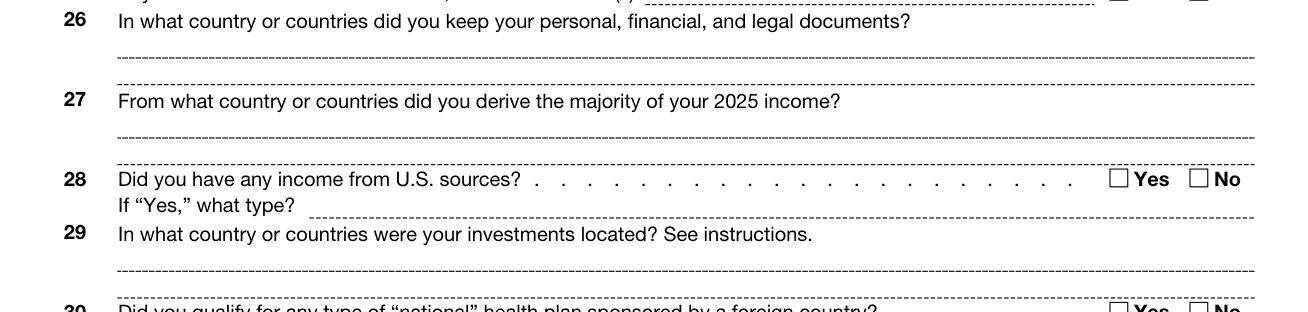
In what country or countries did you keep your personal, financial, and legal documents?
From what country or countries did you derive the majority of your 2025 income?
28 Did you have any income from U.S. sources? Yes No If “Yes,” what type?
29 In what country or countries were your investments located?
For stocks and bonds, indicate the country of origin of the stock company or debtor.
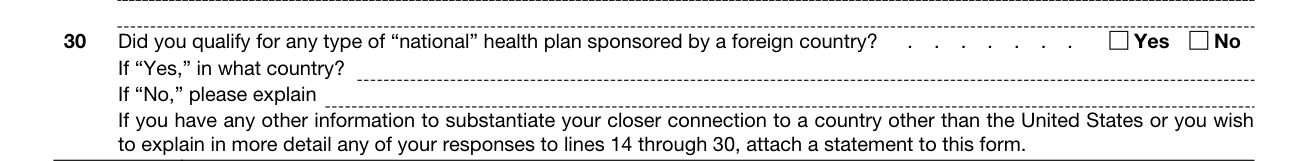
30 Did you qualify for any type of “national” health plan sponsored by a foreign country? Yes No If “Yes,” in what country?
If “No,” please explain. If you have any other information to substantiate your closer connection to a country other than the United States or you wish to explain in more detail any of your responses to lines 14 through 30, attach a statement to this form.
Sign here only if you are filing this form by itself and not with your U.S. tax return.
Under penalties of perjury, I declare that I have examined this form and the accompanying attachments, and to the best of my knowledge and belief, they are true, correct, and complete.
Note: You are not eligible for the closer connection exception if any of the following apply.
You were present in the United States 183 days or more in calendar year 2025.
You are a lawful permanent resident of the United States (that is, you are a green card holder).
You have applied for, or taken other affirmative steps to apply for, a green card; or have an application pending to change your status to that of a lawful permanent resident of the United States.
If you do not timely file Form 8840, you will not be eligible to claim the closer connection exception and may be treated as a U.S. resident.
You will not be penalized if you can show by clear and convincing evidence that you took reasonable actions to become aware of the filing requirements and significant steps to comply with those requirements.
Mail your tax return by the due date (including extensions) to the address shown in your tax return instructions.
If you do not have to file a 2025 tax return, mail Form 8840 to the Department of the Treasury, Internal Revenue Service Center, Austin, TX 73301-0215 by the due date (including extensions) for filing Form 1040-NR.
[1] Form 8840 (2025), Closer Connection Exception Statement for Aliens, Department of the Treasury, Internal Revenue Service (the Official source link on this page).