

Form 51A158 at a glance
What it is: Form 51A158 (9-21) is the Farm Exemption Certificate of the Commonwealth of Kentucky Department of Revenue.
Who signs: Sign on the Farmer's Signature line and enter the Date.
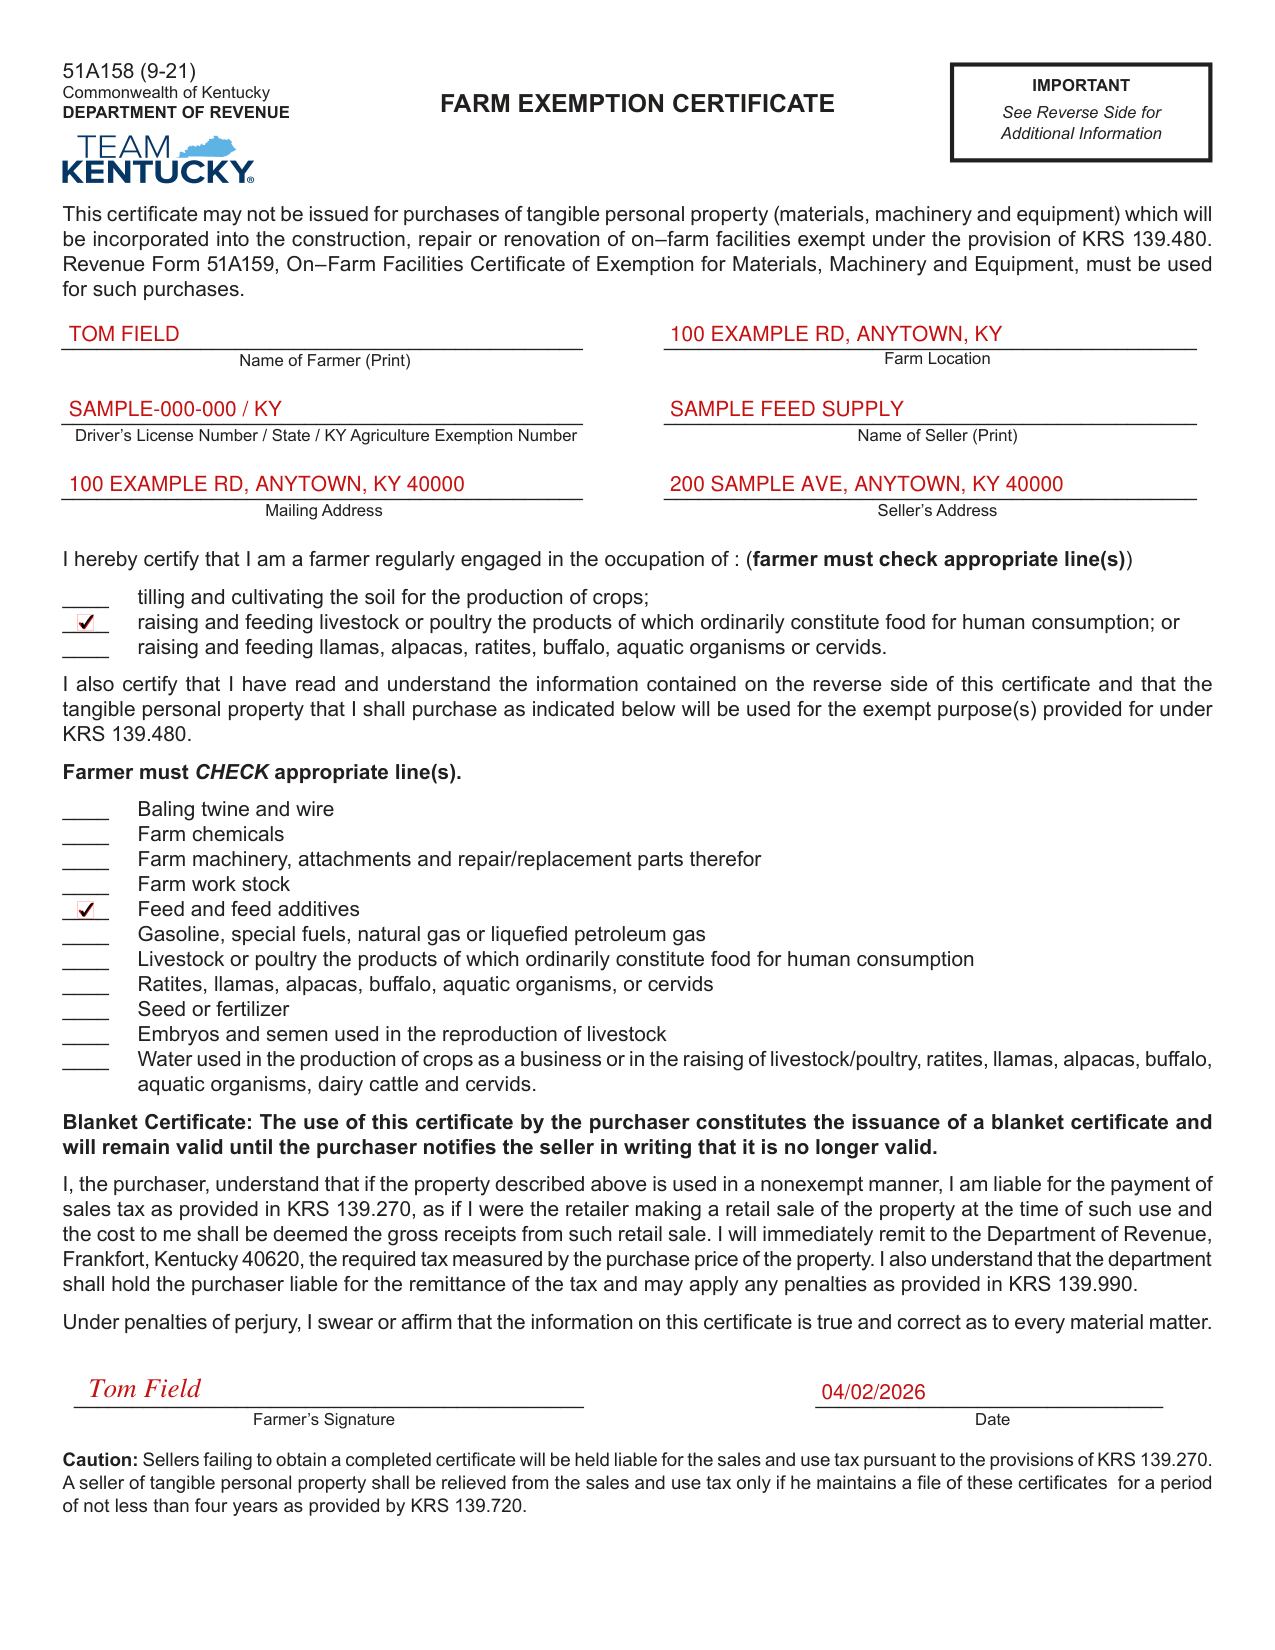
A filled-in Form 51A158 example: a livestock farmer buys feed
How to fill out Form 51A158, box by box
Farmer and seller
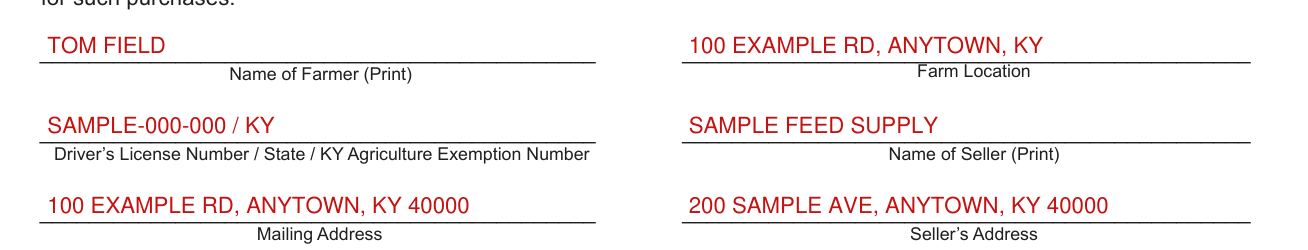
Print the Name of Farmer and enter the Farm Location.
Enter the Driver's License Number / State / KY Agriculture Exemption Number.
Print the Name of Seller.
Enter the Mailing Address and the Seller's Address.
Occupation
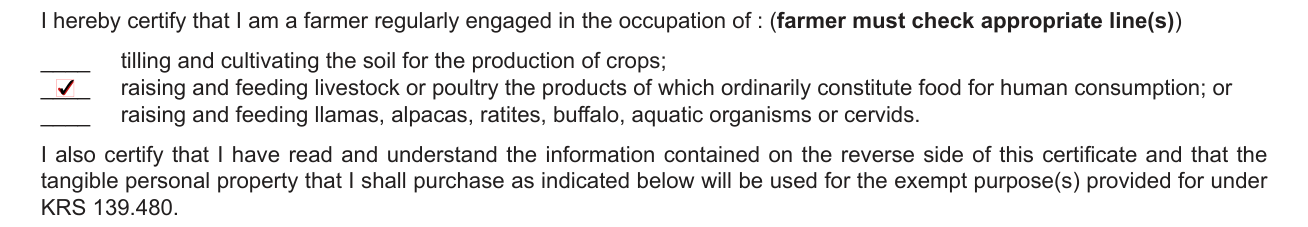
You certify that you are a farmer regularly engaged in the occupation of tilling and cultivating the soil for the production of crops; raising and feeding livestock or poultry the products of which ordinarily constitute food for human consumption; or raising and feeding llamas, alpacas, ratites, buffalo, aquatic organisms or cervids; the farmer must check appropriate line(s).
Property you will buy
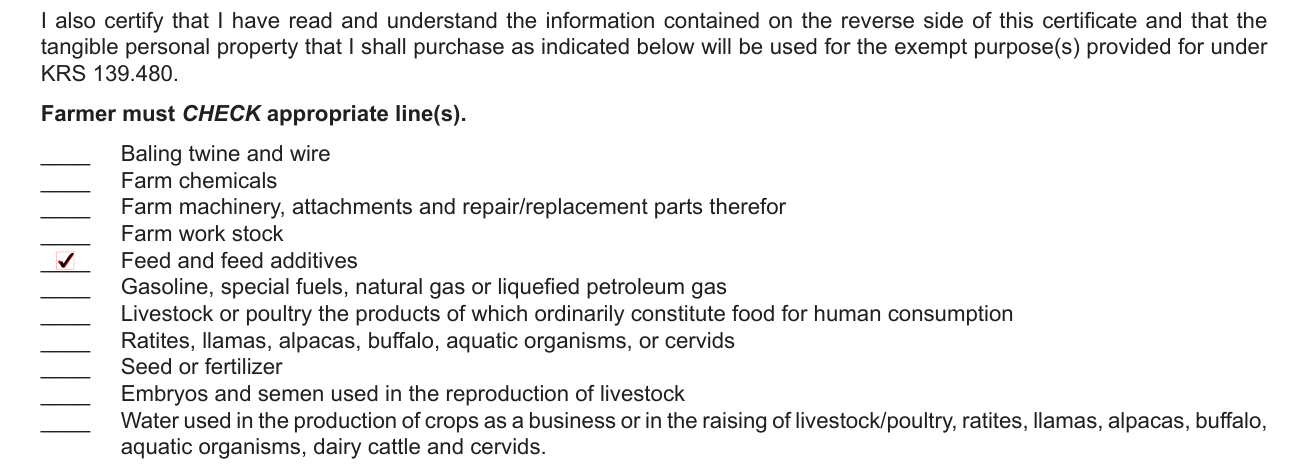
You also certify that you have read and understand the information contained in the reverse side of this certificate and that the tangible personal property that you shall purchase as indicated in the Property you will buy section will be used for the exempt purpose(s) provided for under KRS 139.480.
Farmer must CHECK appropriate line(s): Baling twine and wire; Farm chemicals; Farm machinery, attachments and repair/replacement parts therefor; Farm work stock; Feed and feed additives; Gasoline, special fuels, natural gas or liquefied petroleum gas; Livestock or poultry the products of which ordinarily constitute food for human consumption; Ratites, llamas, alpacas, buffalo, aquatic organisms, or cervids; Seed or fertilizer; Embryos and semen used in the reproduction of livestock; Water used in the production of crops as a business or in the raising of livestock/poultry, ratites, llamas, alpacas, buffalo, aquatic organisms, dairy cattle and cervids.
Baling twine and baling wire are for the baling of hay and straw.
Under KRS 139.480(26), farm chemicals are insecticides, fungicides, herbicides, rodenticides, and other farm chemicals to be used in the production of crops as a business, or in the raising and feeding of livestock or poultry the products of which ordinarily constitute food for human consumption, ratites, llamas and alpacas, buffalo, aquatic organisms, or cervids.
Under KRS 139.480(8), the term farm machinery means machinery used exclusively and directly in the occupation of tilling the soil for the production of crops as a business, or in the occupation of raising and feeding livestock or poultry or of producing milk for sale. The term farm machinery includes machinery, attachments, and replacements therefor, repair parts, and replacement parts which are used or manufactured for use on, or in the operation of farm machinery and which are necessary to the operation of the machinery, and are customarily so used; but this exemption shall not include automobiles, trucks, trailers, and truck-trailer combinations.
Farm work stock is for use in farming operations.
Under KRS 139.480(6), feed, including pre-mixes and feed additives, is for livestock or poultry of a kind the products of which ordinarily constitute food for human consumption, ratites, llamas and alpacas, buffalo, aquatic organisms, or cervids. Under KRS 139.480(9), this exemption does not include feed or feed additives for farm work stock.
Gasoline, special fuels, liquefied petroleum gas, and natural gas are used exclusively and directly to operate farm machinery, on-farm grain/soybean facilities, on-farm poultry, livestock, ratite, llama, alpaca, dairy, or aquaculture facilities.
Under KRS 139.480(15), livestock is of a kind the products of which ordinarily constitute food for human consumption provided the sales are made for breeding or dairy purposes and by or to a person regularly engaged in the business of farming. Under KRS 139.480(4), poultry is for use in breeding and egg production.
Under KRS 139.480(5), ratites, llamas, alpacas, buffalo, aquatic organisms, or cervids are used in an agricultural pursuit.
Under KRS 139.480(23), (25), (28), (29), (30), seeds, the products of which ordinarily constitute food for human consumption or are to be sold in the regular course of business, and commercial fertilizer to be applied on land, the products from which are to be used for food for human consumption or are to be sold in the regular course of business; provided such sales are made to farmers who are regularly engaged in the occupation of tilling and cultivating the soil for the production of crops as a business, or who are regularly engaged in the occupation of raising and feeding livestock or poultry or producing milk for sale; and provided further that tangible personal property so sold is to be used only by those persons so designated who are so purchasing.
Under KRS 139.480(7), embryos and semen are used in the reproduction of livestock, if the products of these embryos and semen ordinarily constitute food for human consumption, and if the sale is to a person engaged in the business of farming.
Under KRS 139.480(24), water is used in the production of crops as a business or in the raising of livestock/poultry, ratites, llamas, alpacas, buffalo, aquatic organisms, cervids, and dairy cattle.
Signature and date
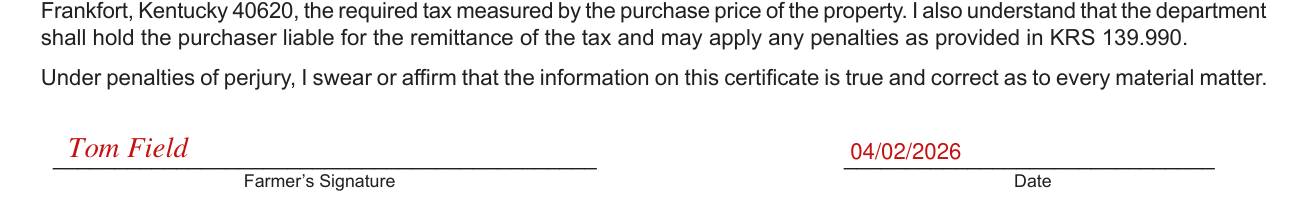
Under penalties of perjury, you swear or affirms that the information on this certificate is true and correct as to every material matter.
Sign on the Farmer's Signature line and enter the Date.
If the property described in the Property you will buy section is used in a nonexempt manner, the purchaser is liable for the payment of sales tax as provided in KRS 139.270, as if the purchaser were the retailer making a retail sale of the property at the time of such use and the cost to the purchaser shall be deemed the gross receipts from such retail sale. The purchaser will immediately remit to the Department of Revenue, Frankfort, Kentucky 40620, the required tax measured by the purchase price of the property. The department shall hold the purchaser liable for the remittance of the tax and may apply any penalties as provided in KRS 139.990.
More rules for Form 51A158
The use of this certificate by the purchaser constitutes the issuance of a blanket certificate and will remain valid until the purchaser notifies the seller in writing that it is no longer valid.
Sellers failing to obtain a completed certificate will be held liable for the sales and use tax pursuant to the provisions of KRS 139.270. A seller of tangible personal property shall be relieved from the sales and use tax only if the seller maintains a file of these certificates for a period of not less than four years as provided by KRS 139.720.
Under KRS 139.480(27), questions should be directed to the Division of Sales and Use Tax, (502) 564-5170.
Common questions about Form 51A158
When is this form not the right one?
This certificate may not be issued for purchases of tangible personal property (materials, machinery and equipment) which will be incorporated into the construction, repair or renovation of on-farm facilities exempt under the provision of KRS 139.480. Revenue Form 51A159, On-Farm Facilities Certificate of Exemption for Materials, Machinery and Equipment, must be used for such purchases.
Sources
[1] Form 51A158 (9-21), Farm Exemption Certificate, Commonwealth of Kentucky Department of Revenue (the Official source link on this page).