

Form CDTFA-230-J at a glance
What it is: CDTFA-230-J is the California Department of Tax and Fee Administration's partial exemption certificate for blanket qualified sales and purchases of teleproduction or other postproduction service equipment.
Who signs: By signing you certify that you are a qualified person primarily engaged in teleproduction or other postproduction services as described in Regulation 1532 and that the property purchased or leased will be used primarily in teleproduction or other postproduction services or to maintain, repair, measure or test any such property. You understand that if such property is used outside the State of California or leased to a non-qualified person in the aggregate for more than one half of the one year period following the date of purchase or lease, or if such property is converted for use in a manner not qualifying for the exemption, that you are required by the Revenue and Taxation Code to report and pay the state sales/use tax measured by the sales price of the property to/by you. You sign on the SIGNATURE line, with the PRINT NAME, TITLE and COMPANY NAME entered.
A filled-in Form CDTFA-230-J example: a postproduction company with no seller's permit
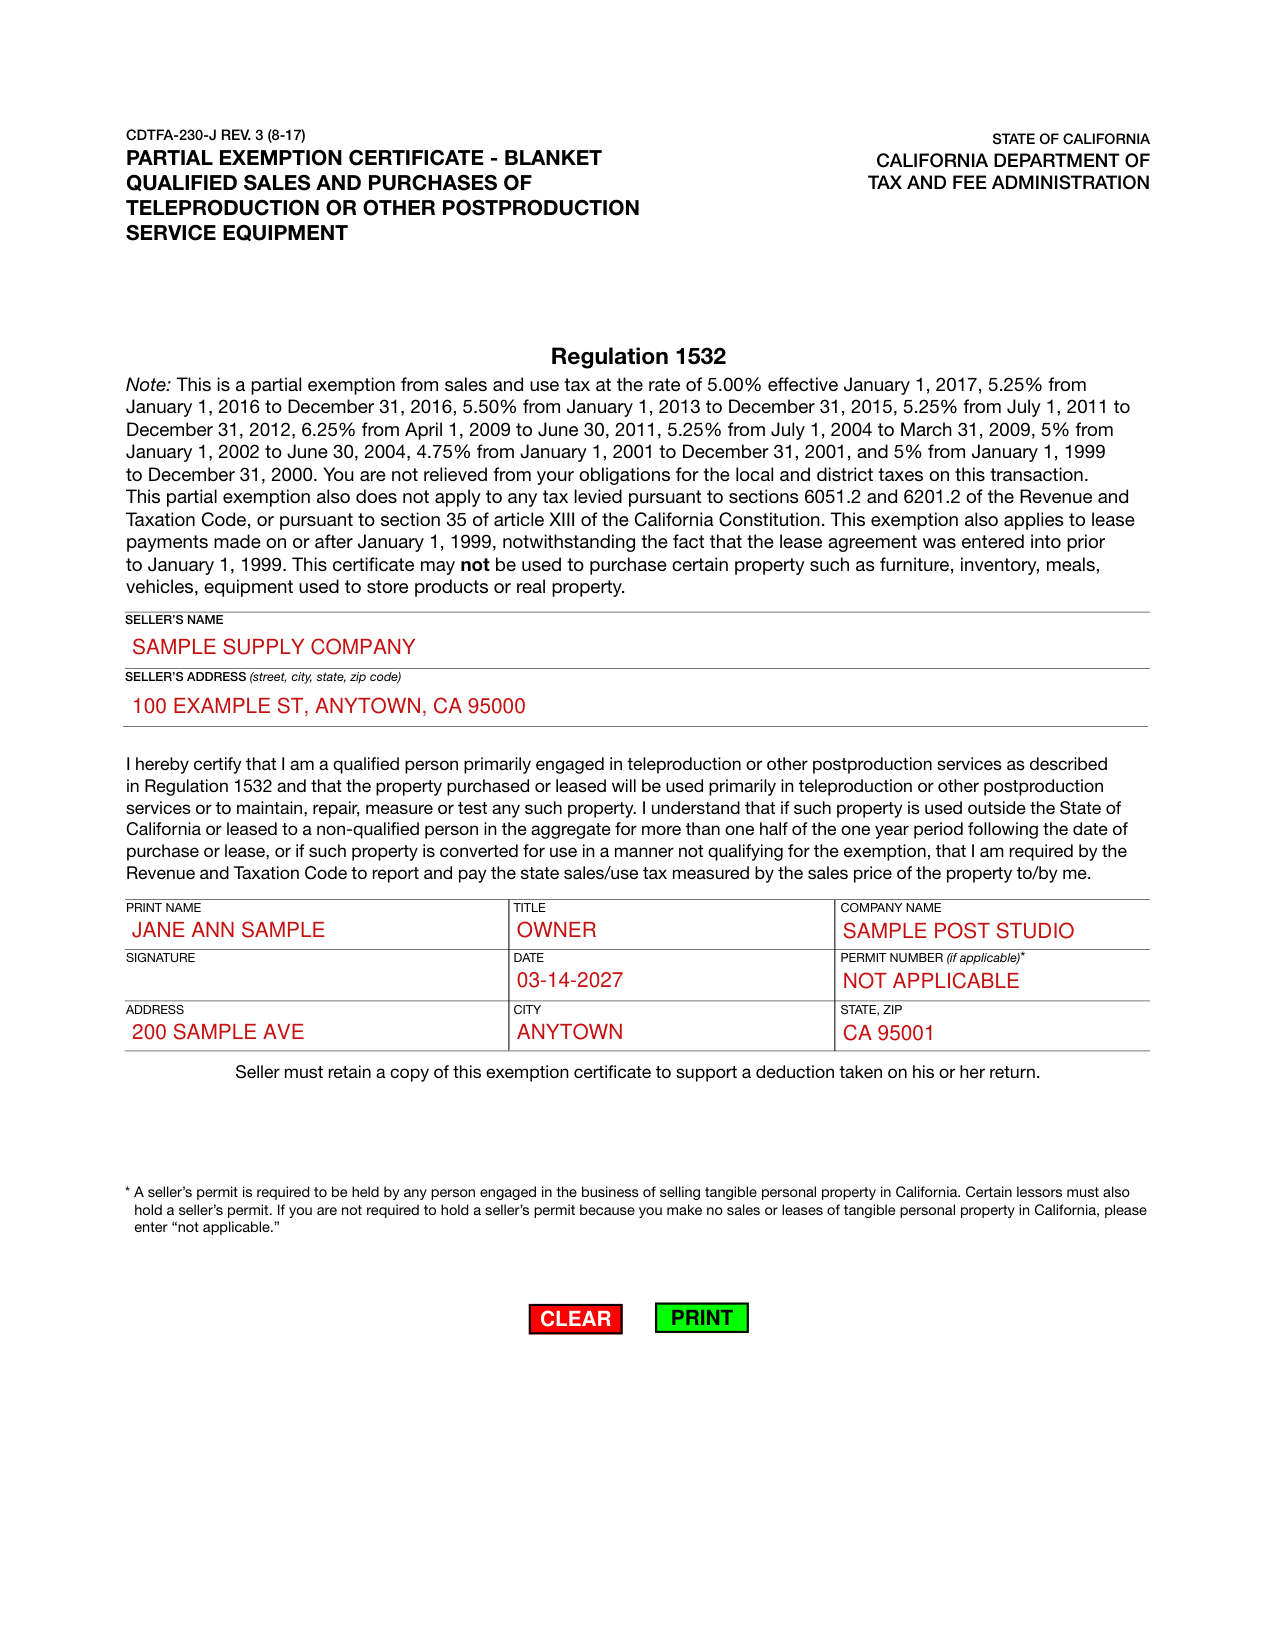
How to fill out Form CDTFA-230-J, box by box
SELLER'S NAME and SELLER'S ADDRESS
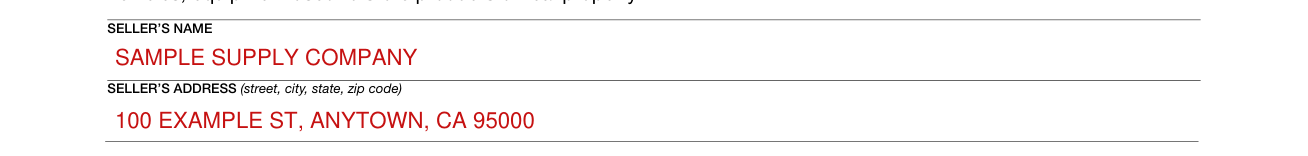
Enter the SELLER'S NAME and the SELLER'S ADDRESS (street, city, state, zip code).
PRINT NAME, TITLE, COMPANY NAME, SIGNATURE, DATE and ADDRESS
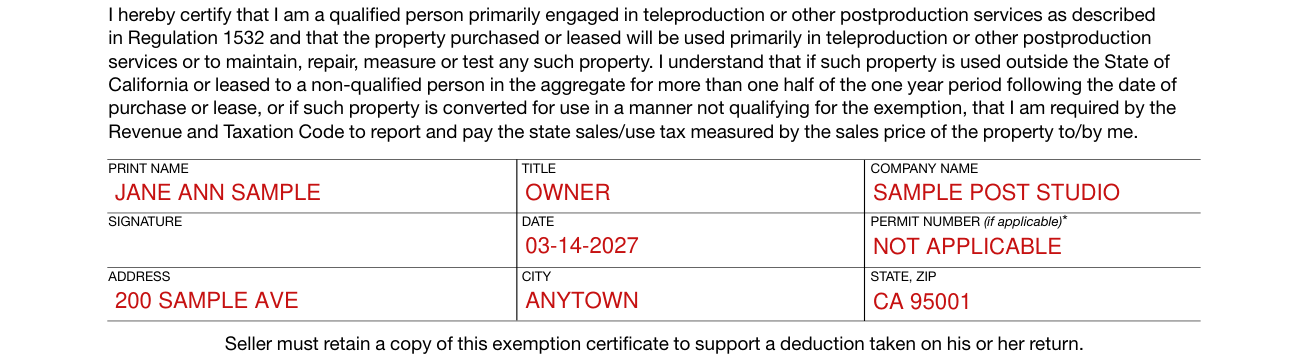
Enter PRINT NAME, TITLE and COMPANY NAME.
Enter the DATE.
Enter your ADDRESS, CITY and STATE, ZIP.
PERMIT NUMBER (if applicable)

With SIGNATURE and DATE, enter PERMIT NUMBER (if applicable)*. For the * after PERMIT NUMBER (if applicable): A seller's permit is required to be held by any person engaged in the business of selling tangible personal property in California. Certain lessors must also hold a seller's permit. If you are not required to hold a seller's permit because you make no sales or leases of tangible personal property in California, please enter “not applicable.”
More rules for Form CDTFA-230-J
Seller must retain a copy of this exemption certificate to support a deduction taken on his or her return.
Common questions about Form CDTFA-230-J
When is this form not the right one?
Regulation 1532 Note: This is a partial exemption from sales and use tax at the rate of 5.00% effective January 1, 2017, 5.25% from January 1, 2016 to December 31, 2016, 5.50% from January 1, 2013 to December 31, 2015, 5.25% from July 1, 2011 to December 31, 2012, 6.25% from April 1, 2009 to June 30, 2011, 5.25% from July 1, 2004 to March 31, 2009, 5% from January 1, 2002 to June 30, 2004, 4.75% from January 1, 2001 to December 31, 2001, and 5% from January 1, 1999 to December 31, 2000. You are not relieved from your obligations for the local and district taxes on this transaction. This partial exemption also does not apply to any tax levied pursuant to sections 6051.2 and 6201.2 of the Revenue and Taxation Code, or pursuant to section 35 of article XIII of the California Constitution. This exemption also applies to lease payments made on or after January 1, 1999, notwithstanding the fact that the lease agreement was entered into prior to January 1, 1999. This certificate may not be used to purchase certain property such as furniture, inventory, meals, vehicles, equipment used to store products or real property.
Sources
[1] Form CDTFA-230-J (8-17), Partial Exemption Certificate, California Department of Tax and Fee Administration (the Official source link on this page).