
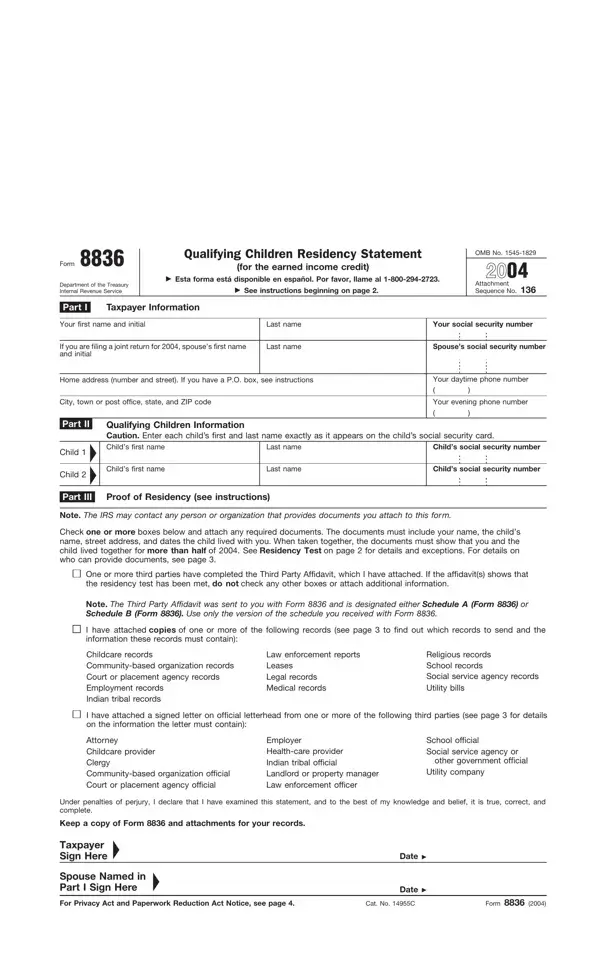

Form 8836 at a glance
What it is: Form 8836 is the Qualifying Children Residency Statement (for the earned income credit).
Where and when to file: You may still file your tax return electronically. If you do so, send Form 8836 and all required attachments to: Internal Revenue Service Stop 4300, Annex R2 Kansas City, MO 64999-0065. Call 1-800-294-2723 if you need help completing this form or you cannot get the documents you need to send with this form.
Use Form 8836 if the IRS sent this form to you and you have a qualifying child for the earned income credit (EIC) for 2004.
File this form only if you are claiming or expect to claim the EIC with a qualifying child for 2004.
What to bring and attach to Form 8836
If you send an official record or letter, it must clearly show: ●Your name, your child's name, or both names, and ●A street address and the dates that you or your child lived at that address during 2004, and ●The name, address, and phone number of the person or organization that provided the record or letter.
Do not send any original records.
A filled-in Form 8836 example: a parent shows one child lived with her
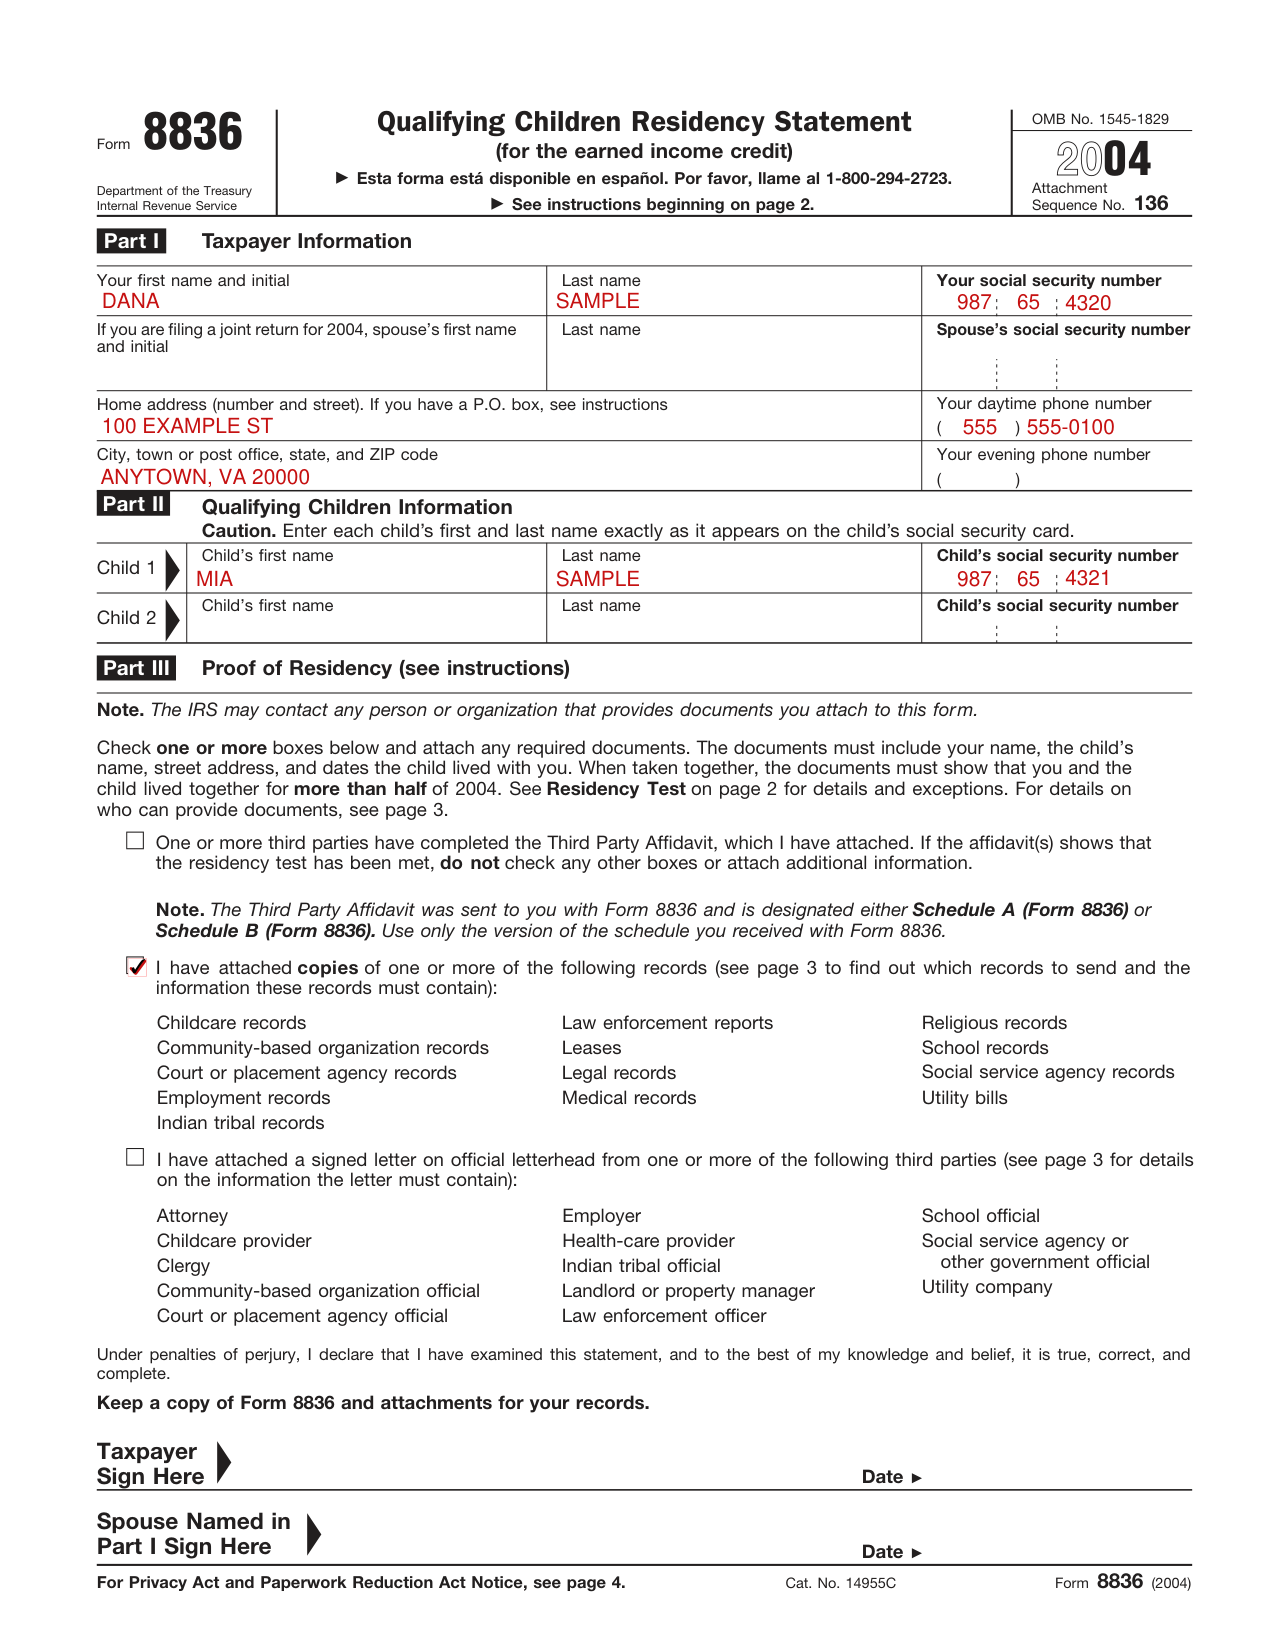
How to fill out Form 8836, box by box
Taxpayer Information
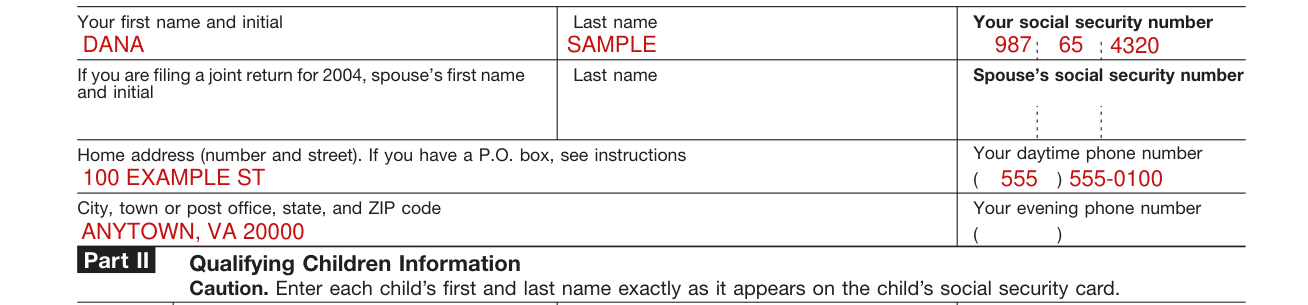
Taxpayer Information Your first name and initial Last name Your social security number.
Enter your box number only if your post office does not deliver mail to your home. Otherwise, enter your home street address.
Providing your daytime and evening phone numbers may help speed the processing of this form.
You may list a mobile phone number as your daytime or evening phone number (or both).
If you are filing a joint return, spouse's first name and initial and social security number

If you are filing a joint return for 2004, spouse's first name and initial Spouse's social security number.
If you and your spouse are filing a joint return, you only need to show that your child lived with one of you for more than half of 2004.
Qualifying Children Information
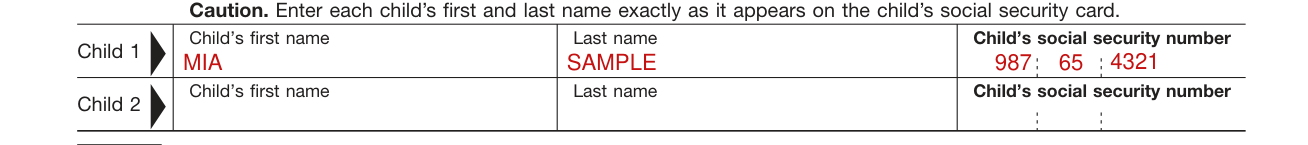
Enter each child's first and last name exactly as it appears on the child's social security card.
Your qualifying child must have a valid social security number (SSN), unless the child was born and died in 2004.
If the qualifying child was born and died in 2004 and did not have an SSN, attach a copy of that child's birth certificate to Form 8836 and enter “Died” instead of the child's SSN.
Be sure that any child named on this form is your qualifying child and you are listing or expect to list that child on Schedule EIC of your 2004 tax return.
Proof of Residency
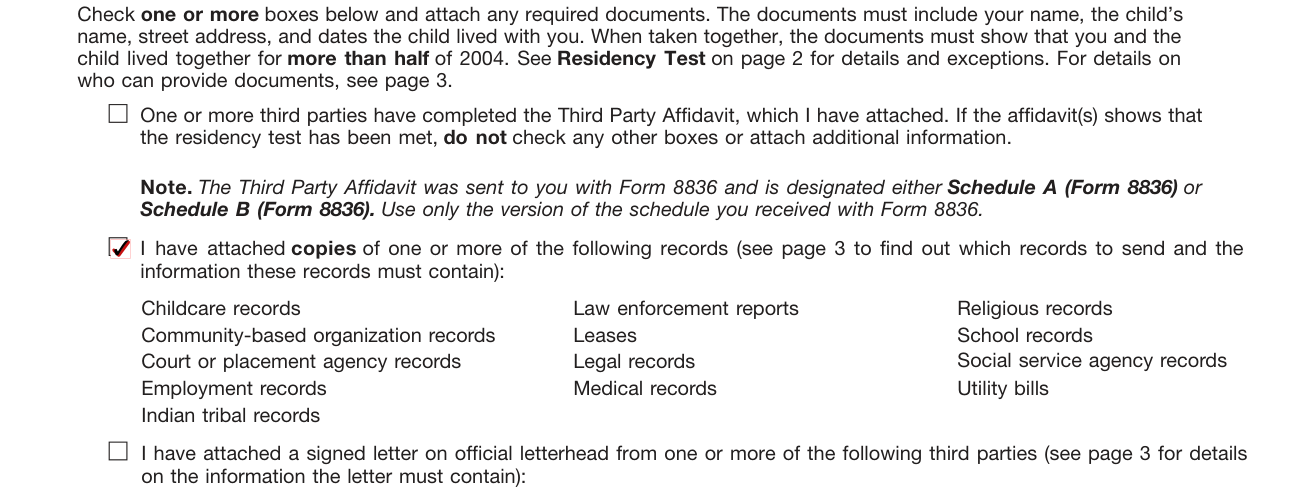
Proof of Residency (see instructions). Check one or more boxes in Part III and attach any required documents. The documents must include your name, the child's name, street address, and dates the child lived with you. When taken together, the documents must show that you and the child lived together for more than half of 2004. See Residency Test on page 2 for details and exceptions. For details on who can provide documents, see page 3.
One or more third parties have completed the Third Party Affidavit, which I have attached. If the affidavit(s) shows that the residency test has been met, do not check any other boxes or attach additional information.
You can submit a Third Party Affidavit from any third party eligible to complete it.
Use only the version of the affidavit (schedule) you received with Form 8836.
I have attached copies of one or more of the following records (see page 3 to find out which records to send and the information these records must contain): Childcare records, Community-based organization records, Court or placement agency records, Employment records, Indian tribal records, Law enforcement reports, Legal records, Leases, Medical records, Religious records, School records, Social service agency records, Utility bills.
I have attached a signed letter on official letterhead from one or more of the following third parties (see page 3 for details on the information the letter must contain): Attorney, Childcare provider, Clergy, Community-based organization official, Court or placement agency official, Employer, Health-care provider, Indian tribal official, Landlord or property manager, School official, Social service agency or other government official, Utility company, Law enforcement officer.
Attach documents if you and your child were temporarily living apart due to special circumstances and you need to count the temporary absences to prove that your child met the residency test.
You can submit any combination of the documents listed as long as they show, when taken together, that your child lived with you for more than half of 2004.
In some cases, a single document will show that you and your child lived at the same address. In other cases, you may need to provide one document showing your name and address as well as a second document showing your child's name with the same address.
You may need more than one document to show that your address and your child's address were the same for more than half of 2004.
More rules for Form 8836
A qualifying child is one who meets the age, relationship, and residency tests for the EIC.
Your child must have lived with you in the United States for more than half of 2004 (at least 184 days).
Include any time that you and your child were temporarily living apart due to special circumstances, such as military service, school attendance, hospitalization, or juvenile detention.
A child is considered to have lived with you for more than half of 2004 if the child was born or died in 2004 and your home was the child's home for the entire time he or she was alive in 2004.
You cannot file Form 8836 electronically.
You can file Form 8836 before January 1, 2005. If you file the form during this period, you may be able to avoid a delay in receiving the EIC part of your tax refund for 2004.
The IRS will send you a letter to let you know if your child has met the residency test.
If you move after you file Form 8836, notify the IRS in writing of your new address.
Keep a copy of Form 8836 and attachments for your records.
Help is available Monday through Friday from 8:00 a.m. to 11:00 p.m. Eastern time.
It does not matter where you lived with your child. For example, you may live with your child in a homeless shelter.
If one or more of your children do not meet the residency test, the IRS will send you a letter to let you know. The IRS will not allow the EIC based on that child.
If you are required to, but do not file Form 8836, the IRS will not allow the EIC with a qualifying child for 2004.
Common questions about Form 8836
Who signs it?
You must sign and date Part III under penalties of perjury before you send it to the IRS with the documents.
Is there a deadline?
You cannot file your tax return by fax. You can file Form 8836 either before January 1, 2005, or after December 31, 2004, but no later than the date you file your 2004 tax return.
Where do I file it?
Send Form 8836 to: Internal Revenue Service, Stop 4300, Annex R2, Kansas City, MO 64999-0065. After December 31, 2004, you can file it at that address. You can also file Form 8836 and any supporting documents by fax at 1-913-266-9640 (not a toll-free number).
Is there a penalty?
Criminal penalties may be imposed for making a false statement.
What am I certifying when I sign?
Under penalties of perjury, I declare that I have examined this statement, and to the best of my knowledge and belief, it is true, correct, and complete.
When is this form not the right one?
Do not file Form 8836 if your child does not meet the residency test for 2004, because the IRS will not allow the EIC based on a qualifying child.
Sources
[1] Form 8836 (2004), Qualifying Children Residency Statement, Internal Revenue Service (the Official source link on this page).