

California Schedule R at a glance
What it is: California Schedule R is the Apportionment and Allocation of Income for Taxable Year 2025.
Where and when to file: Attach this schedule behind the California tax return and prior to the supporting schedules.
What to bring and attach to California Schedule R
Water's-Edge Filers Only: If controlled foreign corporations are included in the combined report, attach form FTB 2416.
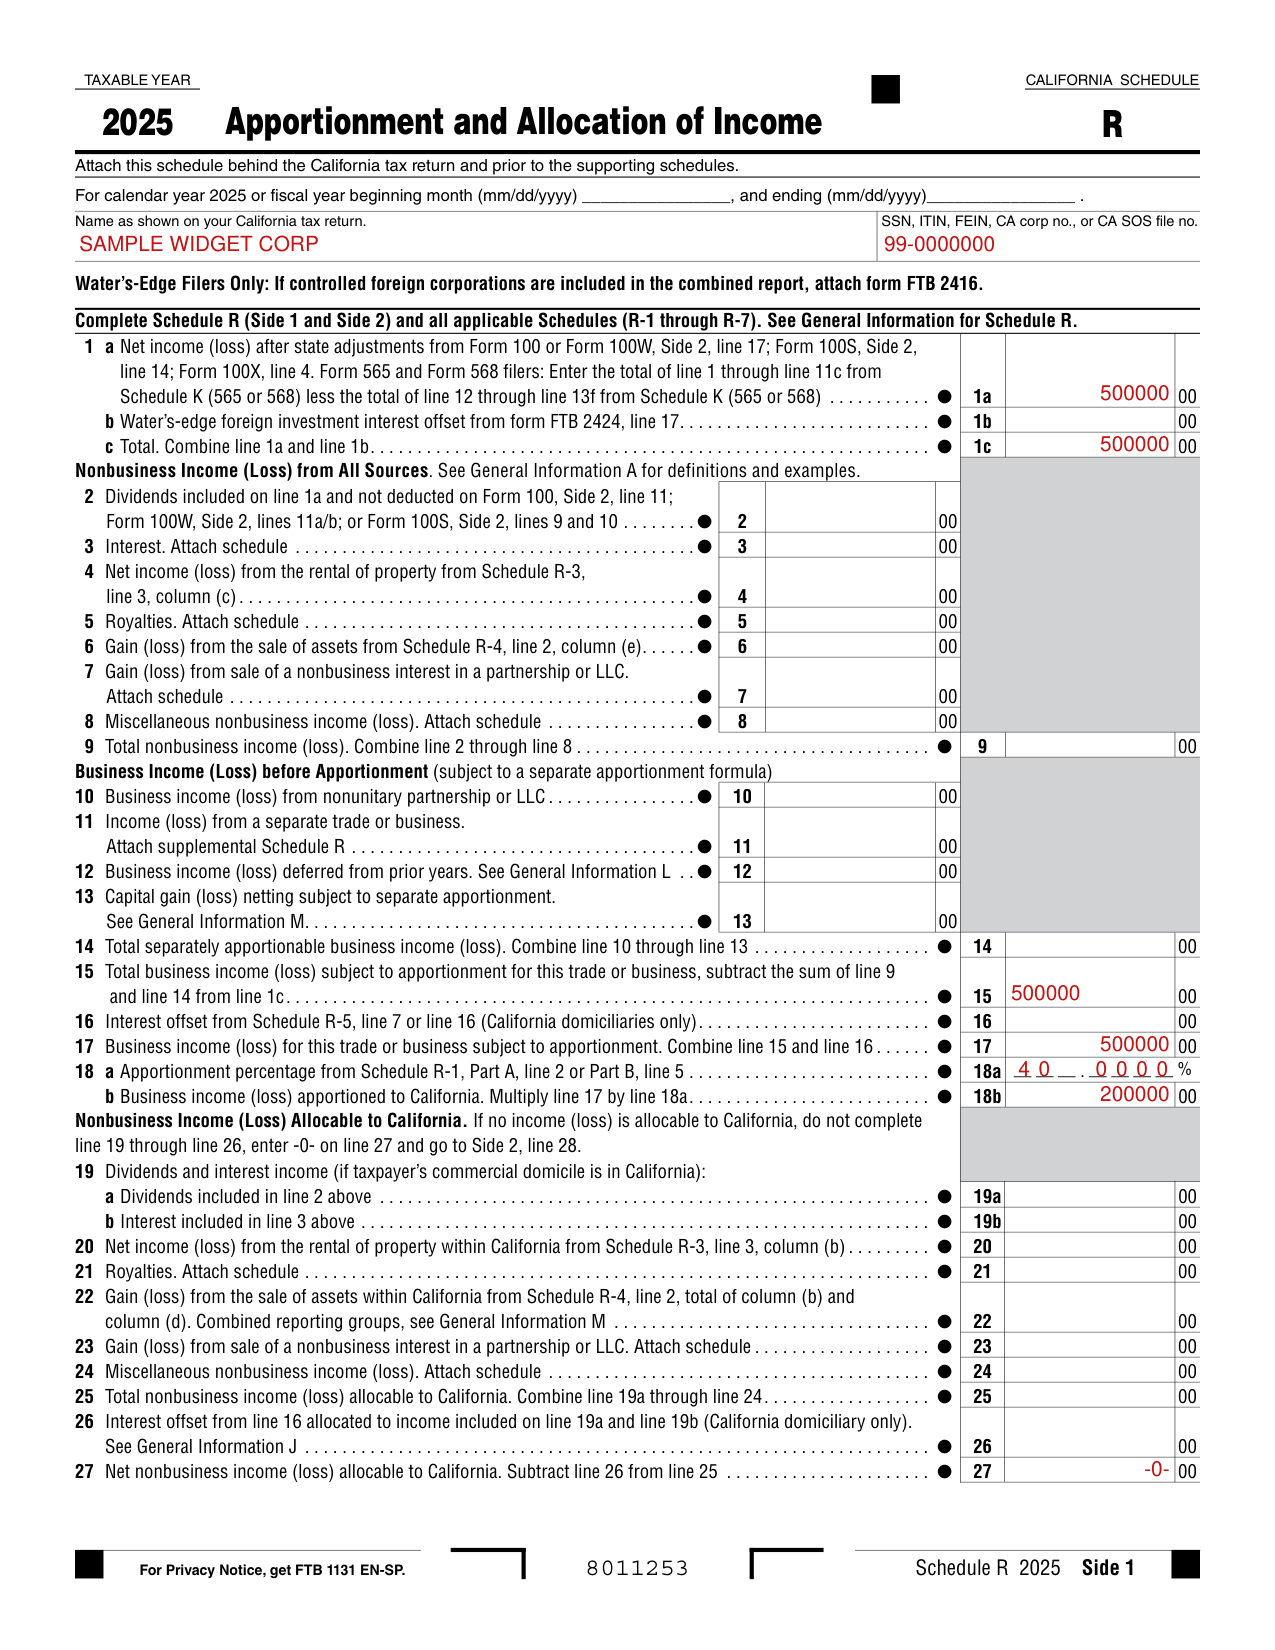
A filled-in California Schedule R example: a corporation with no nonbusiness income computes its apportioned income
How to fill out California Schedule R, box by box
Calendar year or fiscal year, and the name on your return

For calendar year 2025 or fiscal year, enter the fiscal year beginning month (mm/dd/yyyy) and ending (mm/dd/yyyy).
Enter the name as shown on your California tax return and the SSN, ITIN, FEIN, CA corp no., or CA SOS file no.
Net income (loss) after state adjustments
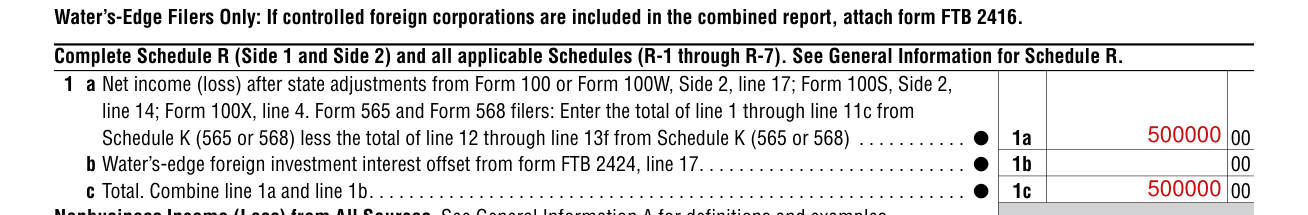
On line 1a, enter the net income (loss) after state adjustments from Form 100 or Form 100W, Side 2, line 17; Form 100S, Side 2, line 14; Form 100X, line 4.
Form 565 and Form 568 filers: Enter the total of line 1 through line 11c from Schedule K (565 or 568) less the total of line 12 through line 13f from Schedule K (565 or 568).
On line 1b, enter the water's-edge foreign investment interest offset from form FTB 2424, line 17.
Line 1c is the Total: combine line 1a and line 1b.
Nonbusiness Income (Loss) from All Sources
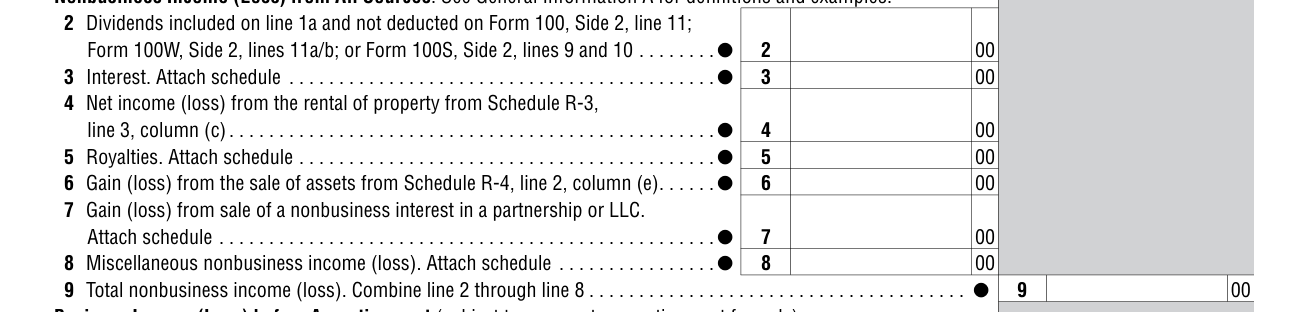
Line 2: Dividends included on line 1a and not deducted on Form 100, Side 2, line 11; Form 100W, Side 2, lines 11a/b; or Form 100S, Side 2, lines 9 and 10. Line 3: Interest. Attach schedule.
Line 4: Net income (loss) from the rental of property from Schedule R-3, line 3, column (c). Line 5: Royalties. Attach schedule. Line 6: Gain (loss) from the sale of assets from Schedule R-4, line 2, column (e).
Line 7: Gain (loss) from sale of a nonbusiness interest in a partnership or LLC. Attach schedule. Line 8: Miscellaneous nonbusiness income (loss). Attach schedule.
Line 9, Total nonbusiness income (loss): combine line 2 through line 8.
Business Income (Loss) before Apportionment
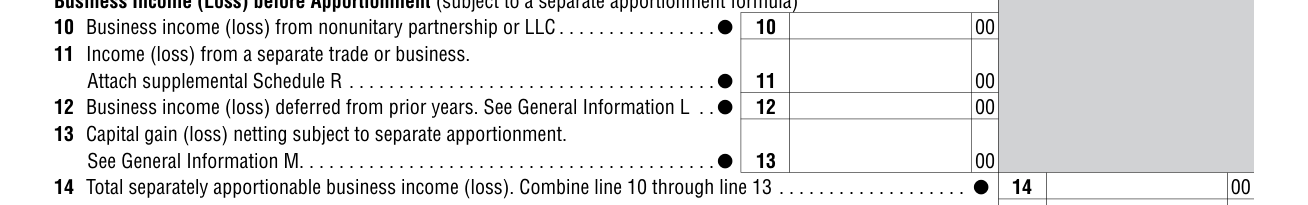
Line 10: Business income (loss) from nonunitary partnership or LLC. Line 11: Income (loss) from a separate trade or business. Attach supplemental Schedule R.
Line 12: Business income (loss) deferred from prior years. See General Information L. Line 13: Capital gain (loss) netting subject to separate apportionment. See General Information M.
Line 14, Total separately apportionable business income (loss): combine line 10 through line 13.
Business income (loss) subject to apportionment
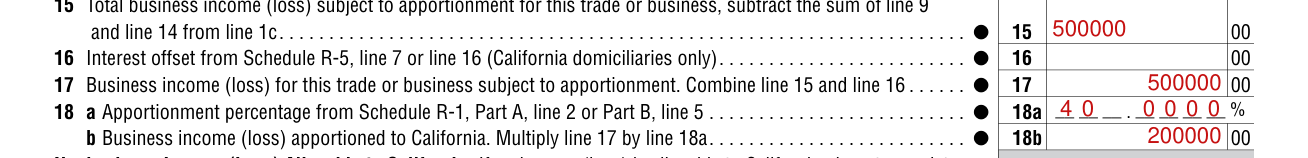
Line 15: Total business income (loss) subject to apportionment for this trade or business, subtract the sum of line 9 and line 14 from line 1c.
Line 16: Interest offset from Schedule R-5, line 7 or line 16 (California domiciliaries only).
Line 17: Business income (loss) for this trade or business subject to apportionment. Combine line 15 and line 16.
Line 18a: Apportionment percentage from Schedule R-1, Part A, line 2 or Part B, line 5. Line 18b: Business income (loss) apportioned to California. Multiply line 17 by line 18a.
Nonbusiness Income (Loss) Allocable to California
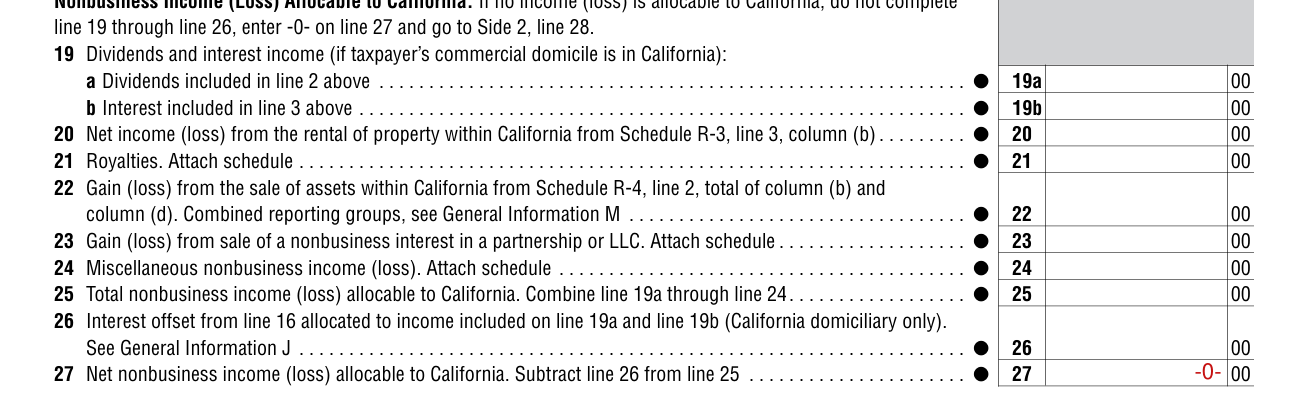
If no income (loss) is allocable to California, do not complete line 19 through line 26, enter -0- on line 27 and go to Side 2, line 28.
Line 19 Dividends and interest income (if taxpayer's commercial domicile is in California): a Dividends included in line 2, b Interest included in line 3.
Line 20: Net income (loss) from the rental of property within California from Schedule R-3, line 3, column (b). Line 21: Royalties. Attach schedule. Line 22: Gain (loss) from the sale of assets within California from Schedule R-4, line 2, total of column (b) and column (d). Combined reporting groups, see General Information M.
Line 23: Gain (loss) from sale of a nonbusiness interest in a partnership or LLC. Attach schedule. Line 24: Miscellaneous nonbusiness income (loss). Attach schedule. Line 25: Total nonbusiness income (loss) allocable to California. Combine line 19a through line 24.
Line 26: Interest offset from line 16 allocated to income included on line 19a and line 19b (California domiciliary only). See General Information J. Line 27: Net nonbusiness income (loss) allocable to California. Subtract line 26 from line 25.
Net Income (Loss) for California Purposes
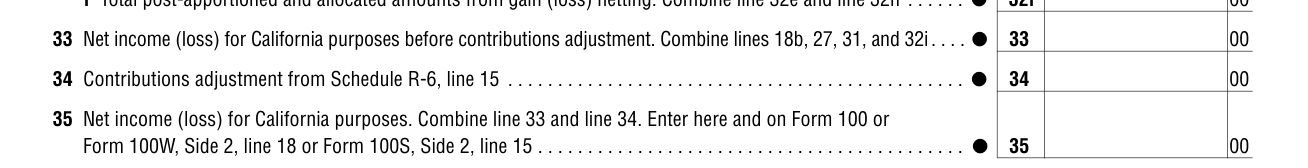
Line 33: Net income (loss) for California purposes before contributions adjustment. Combine lines 18b, 27, 31, and 32i.
Line 34: Contributions adjustment from Schedule R-6, line 15.
Line 35: Net income (loss) for California purposes. Combine line 33 and line 34. Enter on Form 100 or Form 100W, Side 2, line 18 or Form 100S, Side 2, line 15.
Complete the applicable Schedules R-1 through R-7, starting on Side 3.
Schedule R-1 Part A Standard Method, Single-Sales Factor Formula
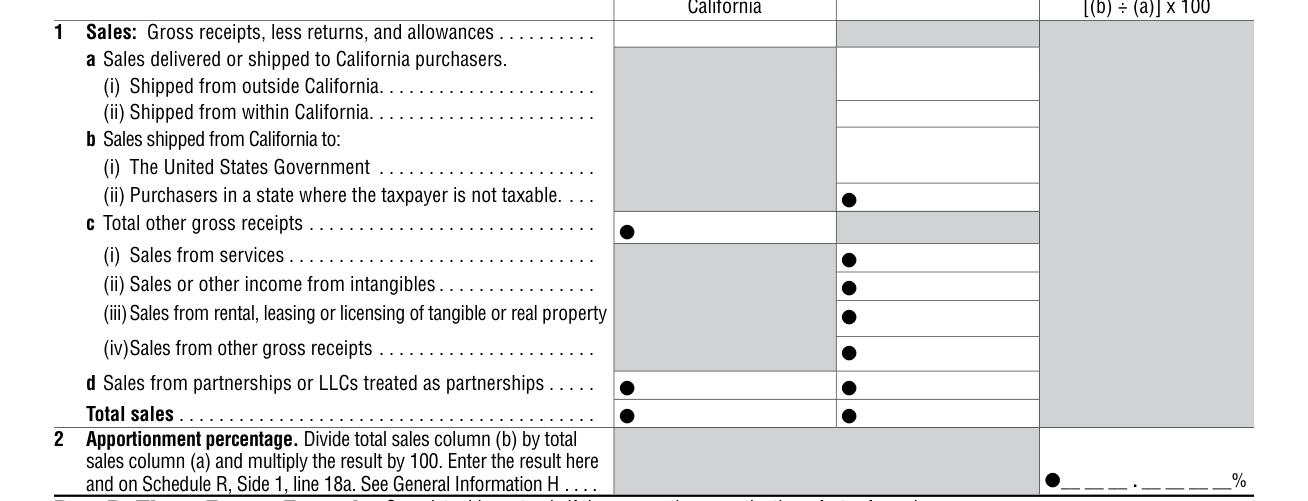
Part A Standard Method, Single-Sales Factor Formula: Complete this part only if the corporation uses the single-sales factor formula.
Line 1 Sales: Gross receipts, less returns, and allowances. a Sales delivered or shipped to California purchasers: (i) Shipped from outside California. (ii) Shipped from within California. b Sales shipped from California to: (i) The United States Government. (ii) Purchasers in a state where the taxpayer is not taxable. c Total other gross receipts: (i) Sales from services. (ii) Sales or other income from intangibles. (iii) Sales from rental, leasing or licensing of tangible or real property. (iv) Sales from other gross receipts. d Sales from partnerships or LLCs treated as partnerships. Total sales.
Line 2 Apportionment percentage: Divide total sales column b by total sales column a and multiply the result by 100. Enter the result on Schedule R, Side 1, line 18a.
Schedule R-1 Part B Three-Factor Formula
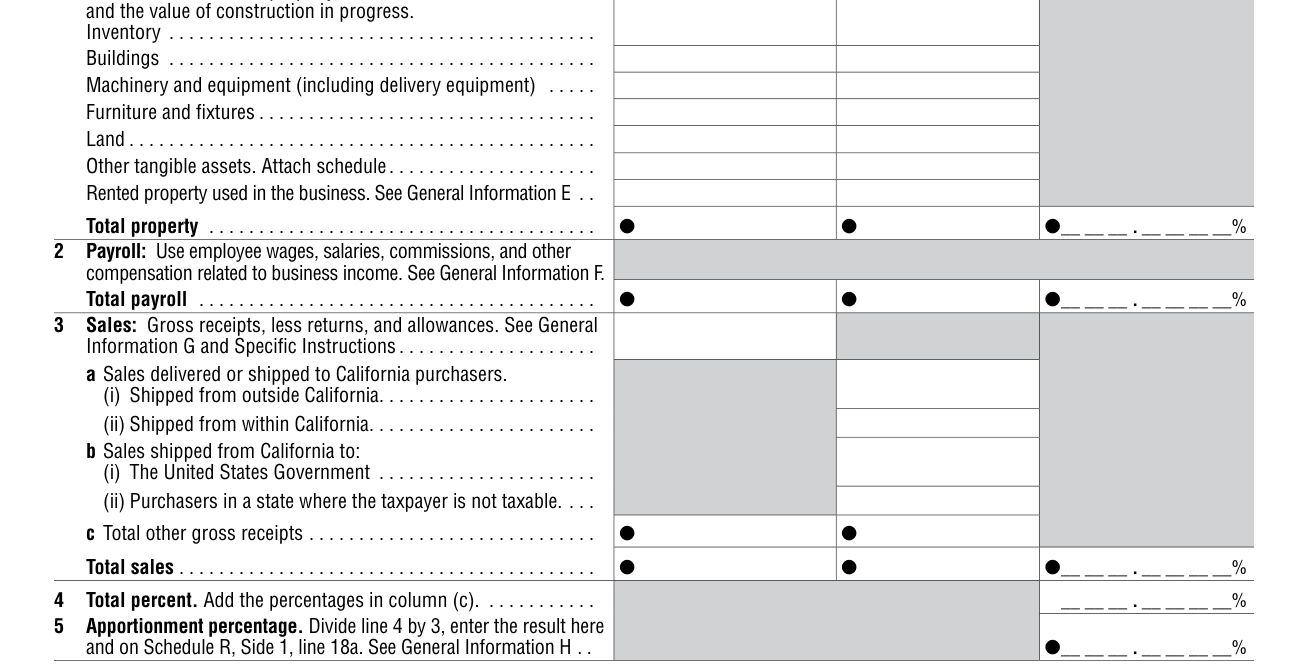
Part B Three-Factor Formula: Complete this part only if the corporation uses the three-factor formula.
Line 4 Total percent: Add the percentages in column (c). Line 5 Apportionment percentage: Divide line 4 by 3, enter the result on Schedule R, Side 1, line 18a.
More rules for California Schedule R
Complete Schedule R (Side 1 and Side 2) and all applicable Schedules (R-1 through R-7).
If your situation is different
You make the Schedule R-7 election
Signing the California tax return is an acknowledgement that the key corporation and its electing affiliates agree to comply with the terms and conditions contained in this Schedule R-7 Election.
Fill out the Schedule R-7 Election completely to make a valid election.
Check box A if the electing member is incorporated, organized, qualified, or registered to do business in California. Check box B if the electing member has any property, payroll, sales in California, or derives income from sources within California, but is not doing business in California. Check box C if the corporation is a new electing member for this current group.
If the information in Part I, Section A, is not filled out completely, the electing member(s) Schedule R-7 election may be disallowed. If an electing member(s) Schedule R-7 election is disallowed, they must file a separate California return.
Note: Schedule R-7, Part I, Section A, should only contain information of corporations that are required to file a return in California, and who are subject to California income or franchise tax. If a corporation does not have a California return filing requirement, the entity should not be listed in this Part I, Section A. The entity should be listed in Part II, Other Affiliated Corporations.
To be eligible, each corporation must meet all of the following: 1) Be a taxpayer required to file a return in California. 2) Be a member of a combined report for its entire taxable year. 3) Have the same taxable year as the key corporation or have a taxable year that is wholly included within the taxable year of the key corporation. 4) Have the same statutory filing date as the key corporation for the taxable year.
Common questions about California Schedule R
Where do I file it?
Attach this schedule behind the California tax return and prior to the supporting schedules.
Sources
[1] California Schedule R, Taxable Year 2025, Apportionment and Allocation of Income, Franchise Tax Board (the Official source link on this page).