

Form CERT-104 at a glance
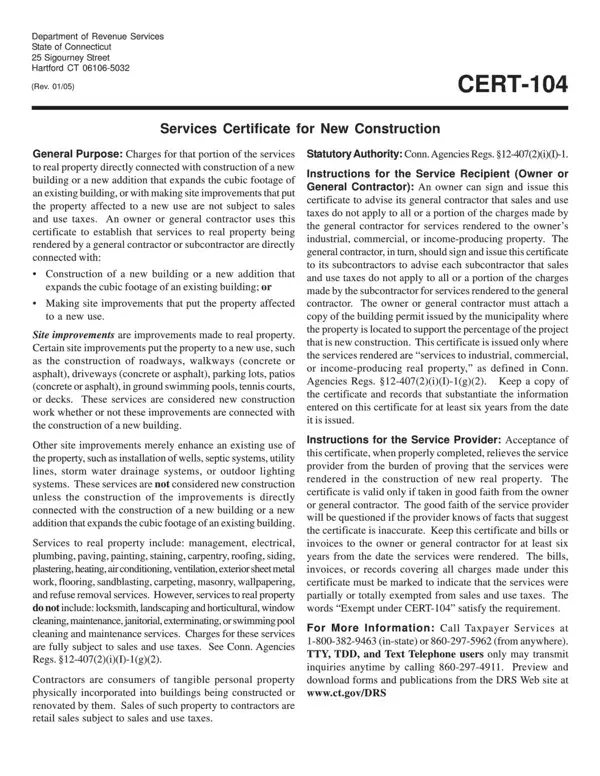
What it is: The Services Certificate for New Construction: an owner or general contractor uses it to establish that services to real property are directly connected with new construction and not subject to sales and use taxes.
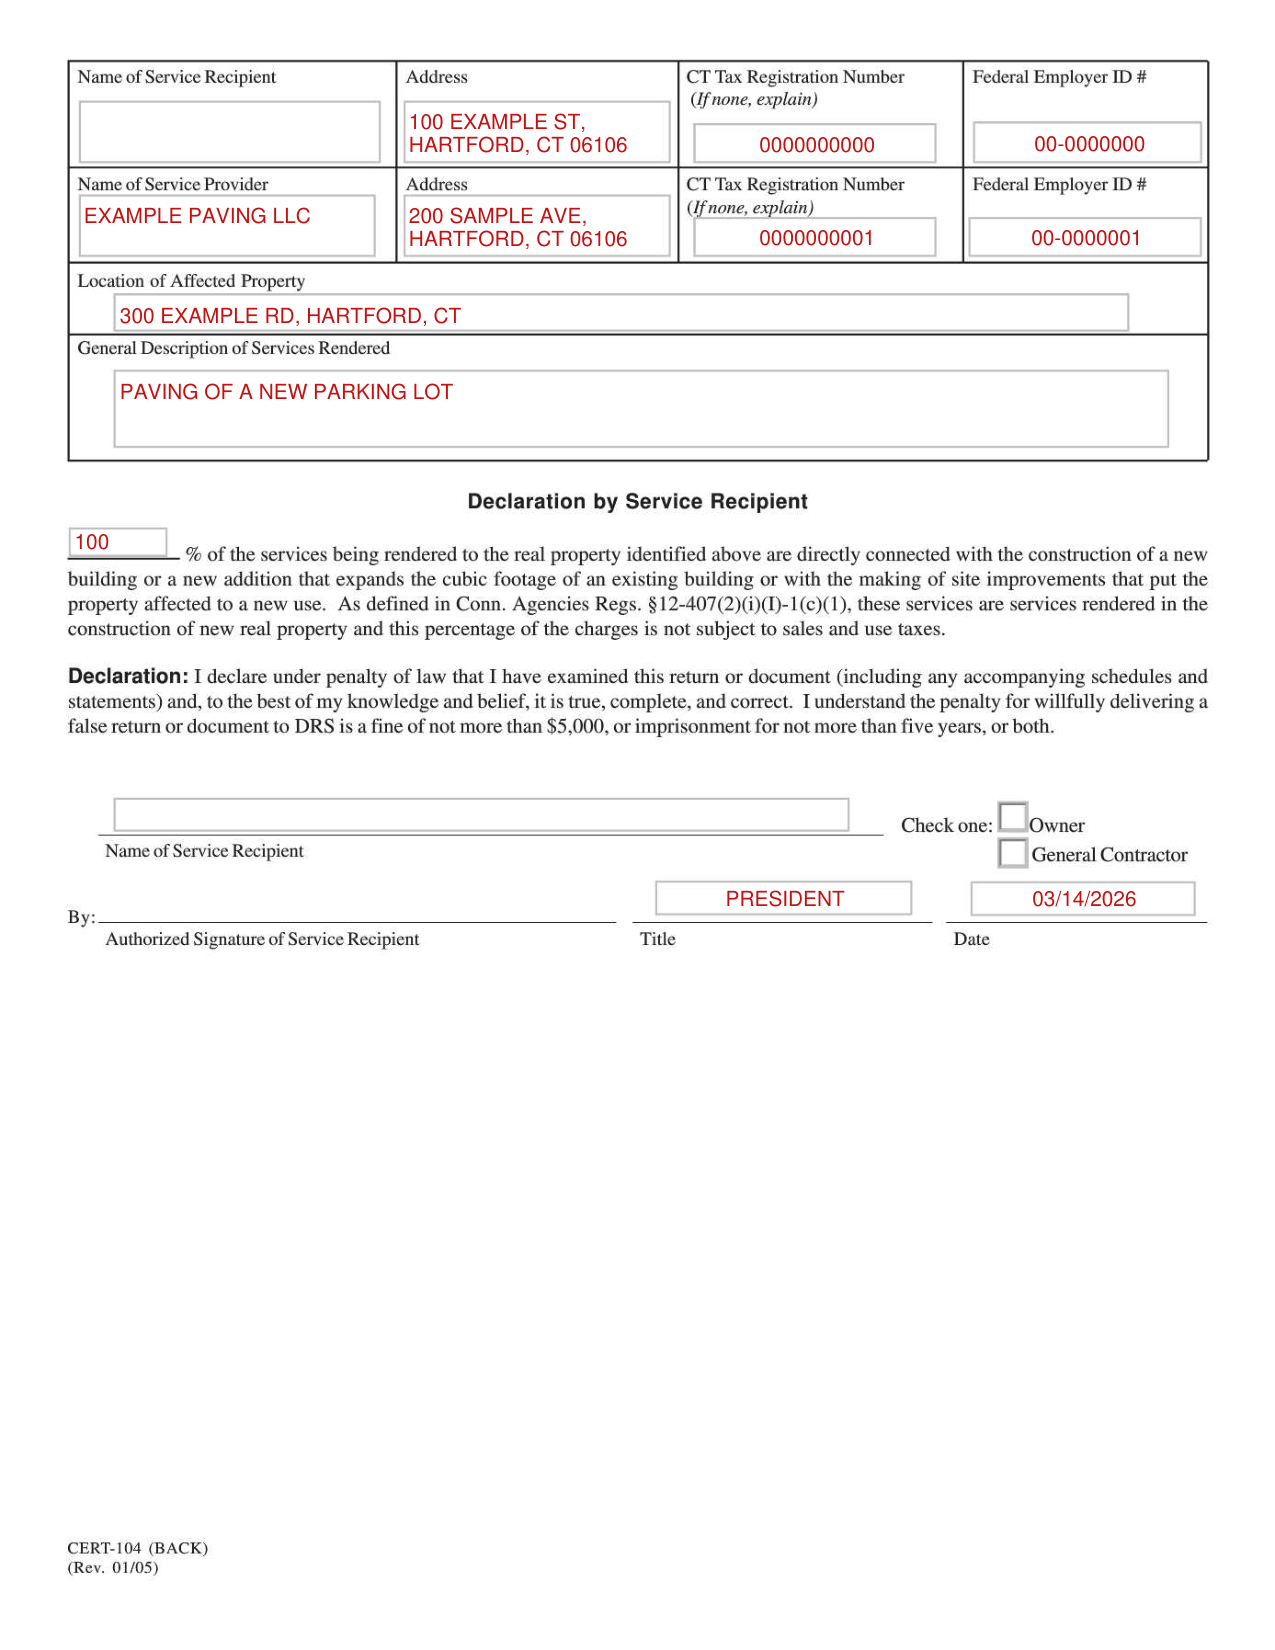
Who signs: Sign By: Authorized Signature of Service Recipient, then enter the Title and Date.
An owner can sign and issue this certificate to advise its general contractor that sales and use taxes do not apply to all or a portion of the charges made by the general contractor for services rendered to the owner's industrial, commercial, or income-producing property. The general contractor, in turn, should sign and issue this certificate to its subcontractors to advise each subcontractor that sales and use taxes do not apply to all or a portion of the charges made by the subcontractor for services rendered to the general contractor.
What to bring and attach to Form CERT-104
The owner or general contractor must attach a copy of the building permit issued by the municipality where the property is located to support the percentage of the project that is new construction. This certificate is issued only where the services rendered are services to industrial, commercial, or income-producing real property, as defined in Conn. Agencies Regs. Keep a copy of the certificate and records that substantiate the information entered on this certificate for at least six years from the date it is issued.
A filled-in Form CERT-104 example: a general contractor certifies new paving
How to fill out Form CERT-104, box by box
Name of Service Recipient and Name of Service Provider
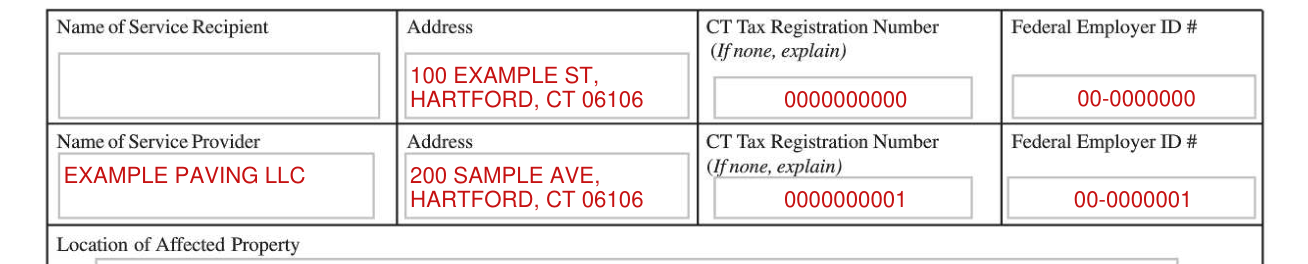
Enter the Name of Service Recipient and the Name of Service Provider, each with Address, CT Tax Registration Number and Federal Employer ID #.
Location of Affected Property and services rendered
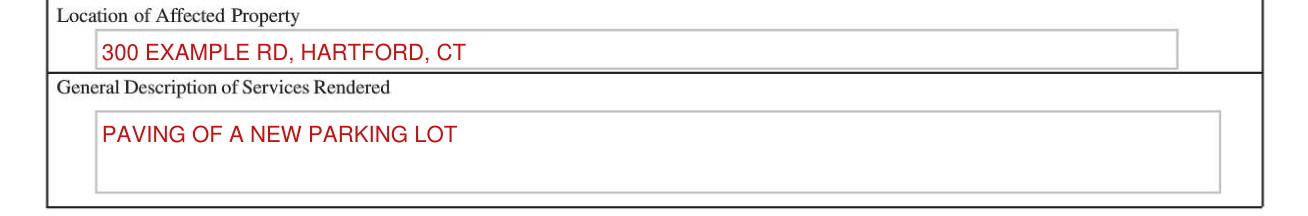
Enter the Location of Affected Property and the General Description of Services Rendered.
Percentage and Declaration
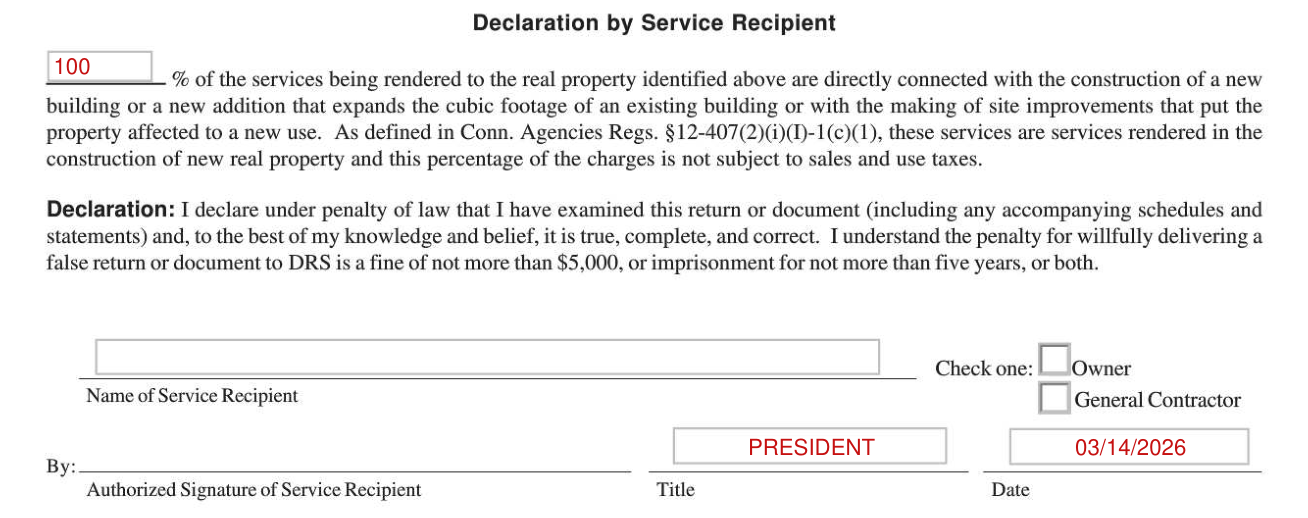
Enter the percentage of the services being rendered to the real property identified under Location of Affected Property that are directly connected with the construction of a new building or a new addition that expands the cubic footage of an existing building or with the making of site improvements that put the property affected to a new use. As defined in Conn. Agencies Regs. §12-407(2)(i)(D-1(c)(1), these services are services rendered in the construction of new real property and this percentage of the charges is not subject to sales and use taxes.
"I declare under penalty of law that I have examined this return or document (including any accompanying schedules and statements) and, to the best of my knowledge and belief, it is true, complete, and correct."
If your situation is different
The services are site improvements
Certain site improvements put the property to a new use, such as the construction of roadways, walkways (concrete or asphalt), driveways (concrete or asphalt), parking lots, patios (concrete or asphalt), in ground swimming pools, tennis courts, or decks. These services are considered new construction work whether or not these improvements are connected with the construction of a new building.
Other site improvements merely enhance an existing use of the property, such as installation of wells, septic systems, utility lines, storm water drainage systems, or outdoor lighting systems. These services are not considered new construction unless the construction of the improvements is directly connected with the construction of a new building or a new addition that expands the cubic footage of an existing building.
Common questions about Form CERT-104
Is there a penalty?
I understand the penalty for willfully delivering a false return or document to DRS is a fine of not more than $5,000, or imprisonment for not more than five years, or both. (checked November 13, 2026)
Sources
[1] Form CERT-104 (Rev. 01/05), Services Certificate for New Construction, Connecticut Department of Revenue Services (the Official source link on this page).