

Form IT-631 at a glance
What it is: Form IT-631 is the Claim for Security Officer Training Tax Credit of the Department of Taxation and Finance, under Tax Law Sections 26 and 606(ii).
Where and when to file: File this form with your personal income tax return, Form IT-201, IT-203, IT-204, or IT-205.
Taxpayers subject to tax under Article 22 should complete Form IT-631.
You may be eligible to claim the security officer training tax credit on Form IT-631 if you have received a certificate of tax credit from the New York State DHSES, are subject to tax under Article 22, and are classified as one of the following taxpayers: individual (including sole proprietor), fiduciary of an estate or trust, partner in a partnership (including member of a limited liability company (LLC) if the LLC is treated as a partnership for federal tax purposes), shareholder of a New York S corporation, or beneficiary.
For tax years beginning on or after January 1, 2005, Tax Law sections 26 and 606(ii) provide for a security officer training tax credit for qualified building owners employing qualified security officers.
The security officer training tax credit is available to taxpayers subject to tax under Article 22 (personal income tax); Article 9 (corporation tax); Article 9-A (franchise tax on business corporations); or Article 33 (franchise taxes on insurance corporations).
What to bring and attach to Form IT-631
Complete a separate Form IT-631 for each certificate of tax credit, and submit a copy of the certificate with the form.
A filled-in Form IT-631 example: a sole proprietor claims one certificate
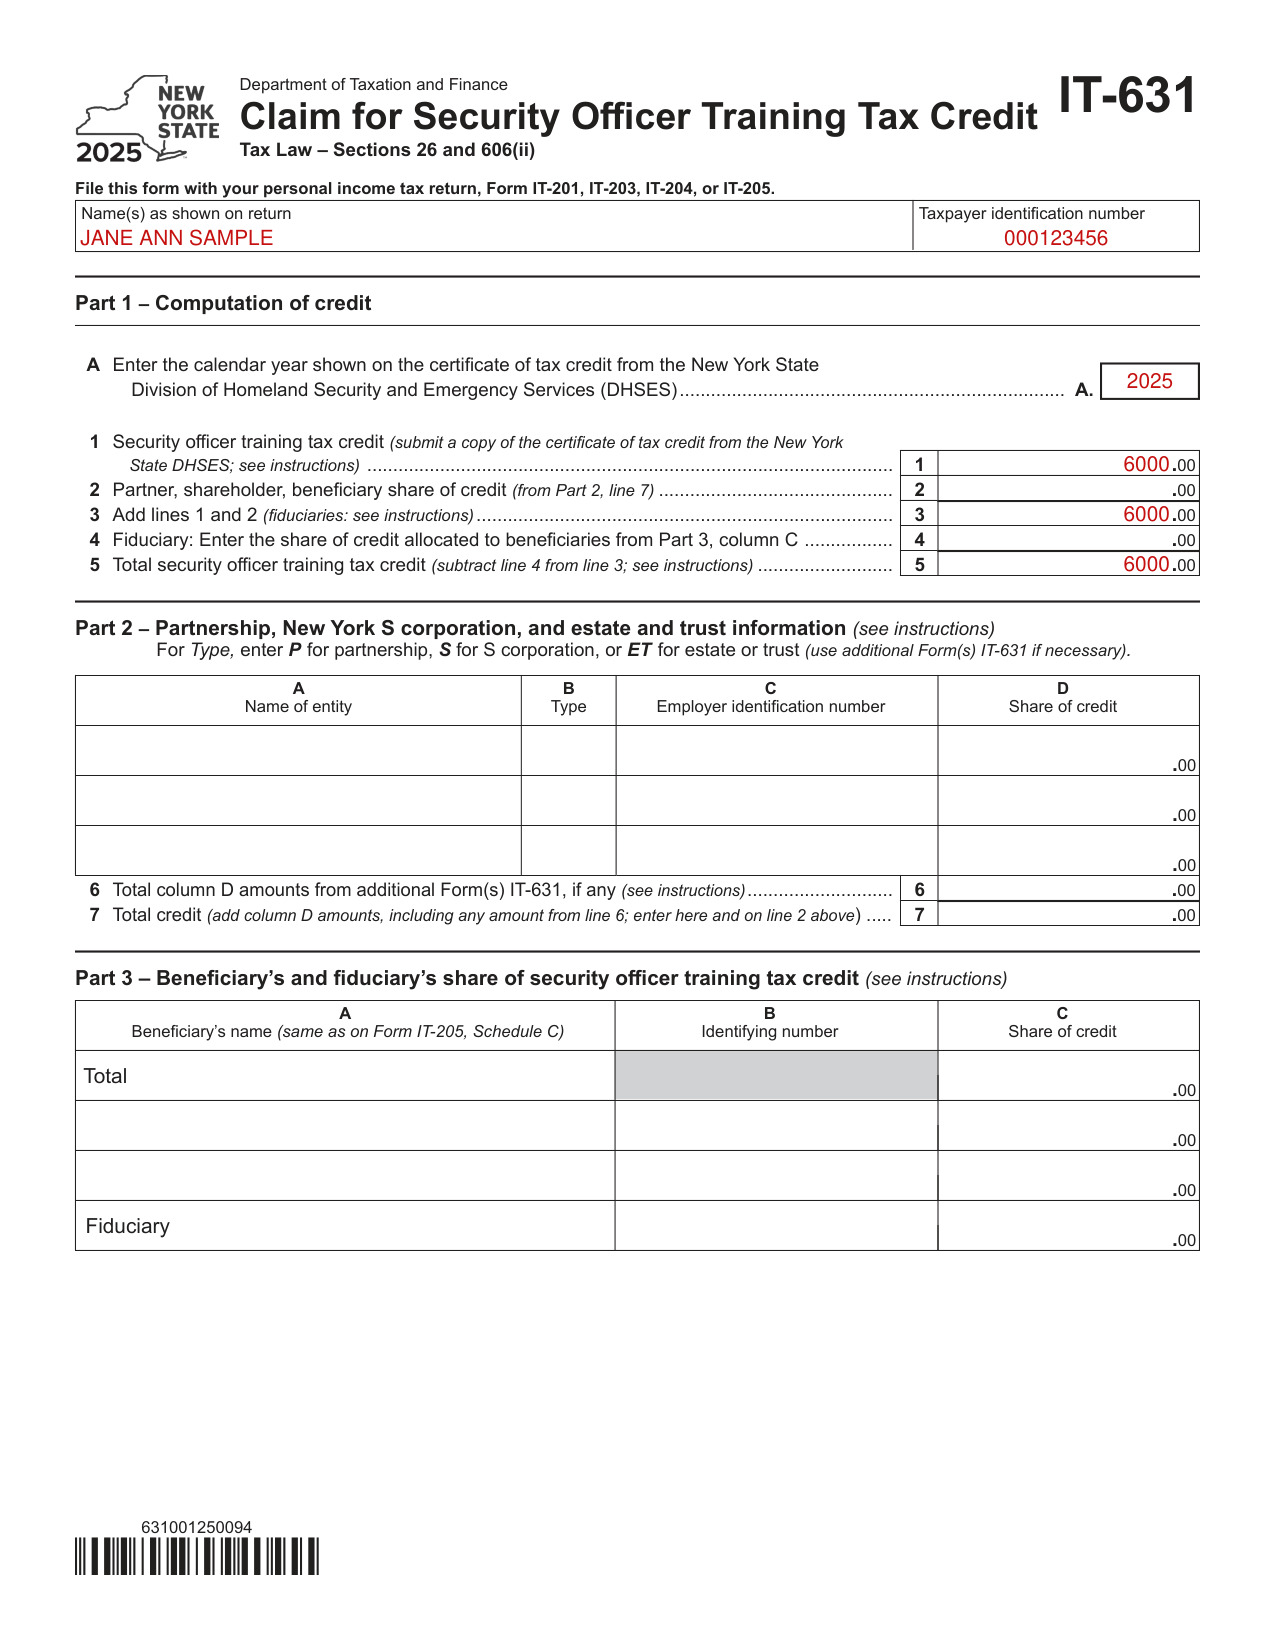
How to fill out Form IT-631, box by box
Which parts to complete
Individual (including sole proprietor) and partnership: Complete Part 1, line A, and lines 1 through 5.
Partner in a partnership, shareholder of a New York S corporation, and beneficiary of an estate or trust: Complete Part 1, lines 2 through 5, and Part 2.
Fiduciary: Complete Part 1, line A, and lines 1 through 5, and Part 3.
If more than one of these applies to you, complete all appropriate parts on one Form IT-631.
Name(s) as shown on return and taxpayer identification number

Enter your name(s) as shown on return and your taxpayer identification number.
Part 1, Computation of credit
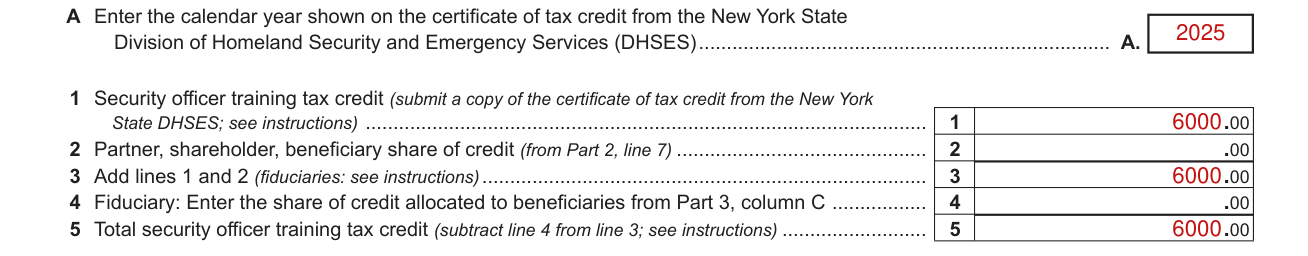
On line A, enter the calendar year shown on the certificate of tax credit from the New York State Division of Homeland Security and Emergency Services (DHSES).
On line 1, enter the amount shown on your certificate of tax credit issued by the New York State DHSES.
On line 2, enter the partner, shareholder, beneficiary share of credit from Part 2, line 7.
On line 3, add lines 1 and 2.
Fiduciaries: Enter the line 3 amount on the Total line of Part 3, column C; then complete Part 3 before completing lines 4 and 5.
Fiduciary: On line 4, enter the share of credit allocated to beneficiaries from Part 3, column C.
On line 5, the total security officer training tax credit, subtract line 4 from line 3.
Add the line 5 amounts from all Forms IT-631, and enter the total on your return as instructed at line 5.
Partnerships: Enter the line 5 amount and code 631 on Form IT-204, line 147.
All others: Enter the amount from line 5 and code 631 on Form IT-201-ATT, line 12, or Form IT-203-ATT, line 12, or include it on Form IT-205, line 33.
Part 2, Partnership, New York S corporation, and estate and trust information
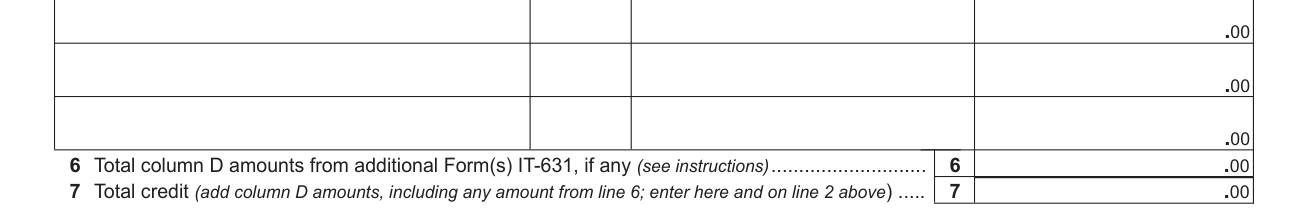
In Part 2, enter the appropriate information for each partnership, S corporation, or estate or trust from which you received a share of the security officer training tax credit.
In each row of Part 2, enter the name of entity, the type, the employer identification number and the share of credit. For Type, enter P for partnership, S for S corporation, or ET for estate or trust (use additional Form(s) IT-631 if necessary).
If you need more space, enter your name and taxpayer identification number, and complete only Part 2 on additional Forms IT-631.
Place the extra forms behind the first Form IT-631.
Include on line 6 of the first Form IT-631 the total of column D from all additional Forms IT-631.
On line 7, the total credit, add column D amounts, including any amount from line 6, and enter it here and on line 2 of Part 1.
Part 3, Beneficiary's and fiduciary's share of security officer training tax credit
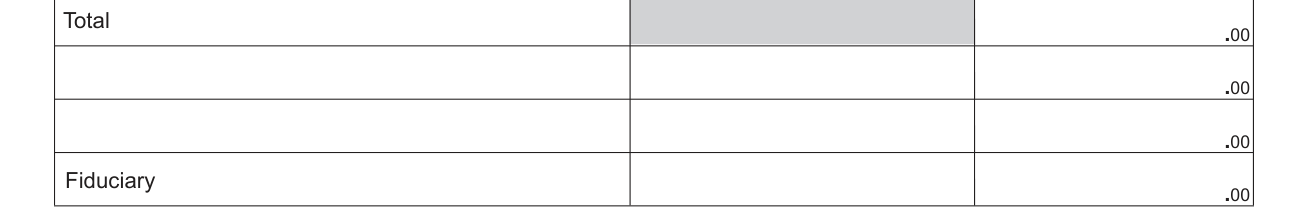
Enter the beneficiary's name (same as on Form IT-205, Schedule C), the identifying number and the share of credit.
In Part 3, if an estate or trust allocates or assigns the credit to its beneficiaries, base the division on each beneficiary's proportionate share of the income of the estate or trust.
Provide your beneficiaries with their proportionate amount of the credit.
More rules for Form IT-631
The credit amount equals $3,000 multiplied by the sum of the number of qualified security officers providing protection for a building or buildings owned by a taxpayer. (checked October 19, 2026)
In the case of a qualified security officer not employed for a full year, the amount of the credit is prorated to reflect the length of employment.
If the credit exceeds the tax for that tax year, the excess credit is treated as an overpayment to be credited or refunded without interest.
The amount of credit allowed for the current tax year is allocated by the New York State Division of Homeland Security and Emergency Services (DHSES).
If your situation is different
You are subject to tax under Article 9, 9-A, or 33
Taxpayers subject to tax under Article 9, 9-A, or 33 should complete Form CT-631, Claim for Security Officer Training Tax Credit.
You are a married couple with an IRC 761(f) election
A married couple in a business enterprise that made an IRC 761(f) election to file two federal Schedule C forms instead of a partnership return: If you file jointly, compute your credit amount as if you were filing one federal Schedule C for the business.
You are an estate or trust that divides the credit
If you are an estate or trust that divides the credit among itself and its beneficiaries, submit all Forms IT-631 with Form IT-205, Fiduciary Income Tax Return, showing each beneficiary's share of credit.
Common questions about Form IT-631
Where do I file it?
File this form with your personal income tax return, Form IT-201, IT-203, IT-204, or IT-205.
Where to get help with Form IT-631
For rules and regulations regarding the credit, access the New York State DHSES website at www.dhses.ny.gov.
Sources
[1] Form IT-631 (2025), Claim for Security Officer Training Tax Credit, New York State Department of Taxation and Finance (the Official source link on this page).