
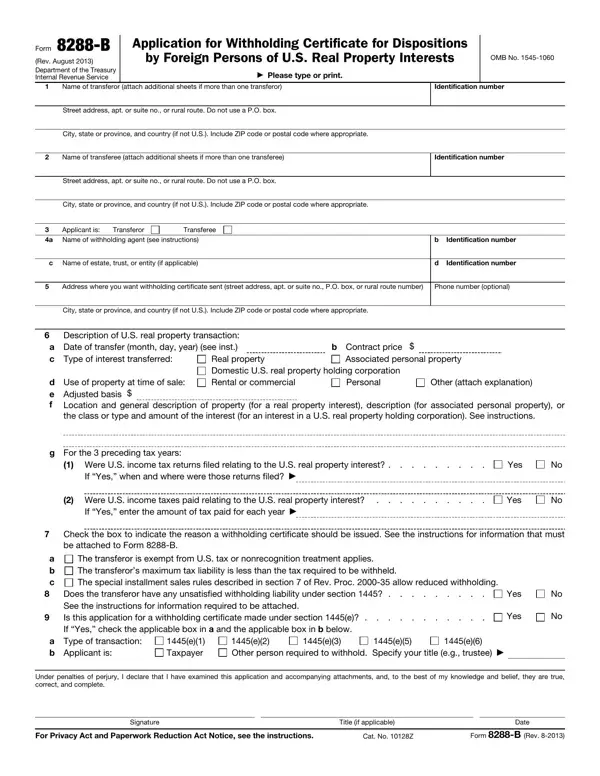
Form 8288-B at a glance
What it is: Form 8288-B is the Application for Withholding Certificate for Dispositions by Foreign Persons of U.S. Real Property Interests.
Who signs: The application must be signed by an individual, a responsible corporate officer, a general partner of a partnership, or a trustee, executor, or other fiduciary of a trust or estate.
Form 8288-B is used to apply for a withholding certificate to reduce or eliminate withholding on dispositions of U.S. real property interests by foreign persons, but only if the application is based on: A claim that the transferor is entitled to nonrecognition treatment or is exempt from tax. A claim solely on a calculation that shows the transferor's maximum tax liability is less than the tax otherwise required to be withheld. A claim that the special installment sales rules described in section 7 of Rev. Proc. 2000-35 allowed reduced withholding.
Either the transferee or the transferor (or other authorized person) can file this application.
A filled-in Form 8288-B example: a foreign seller applies on the maximum tax liability
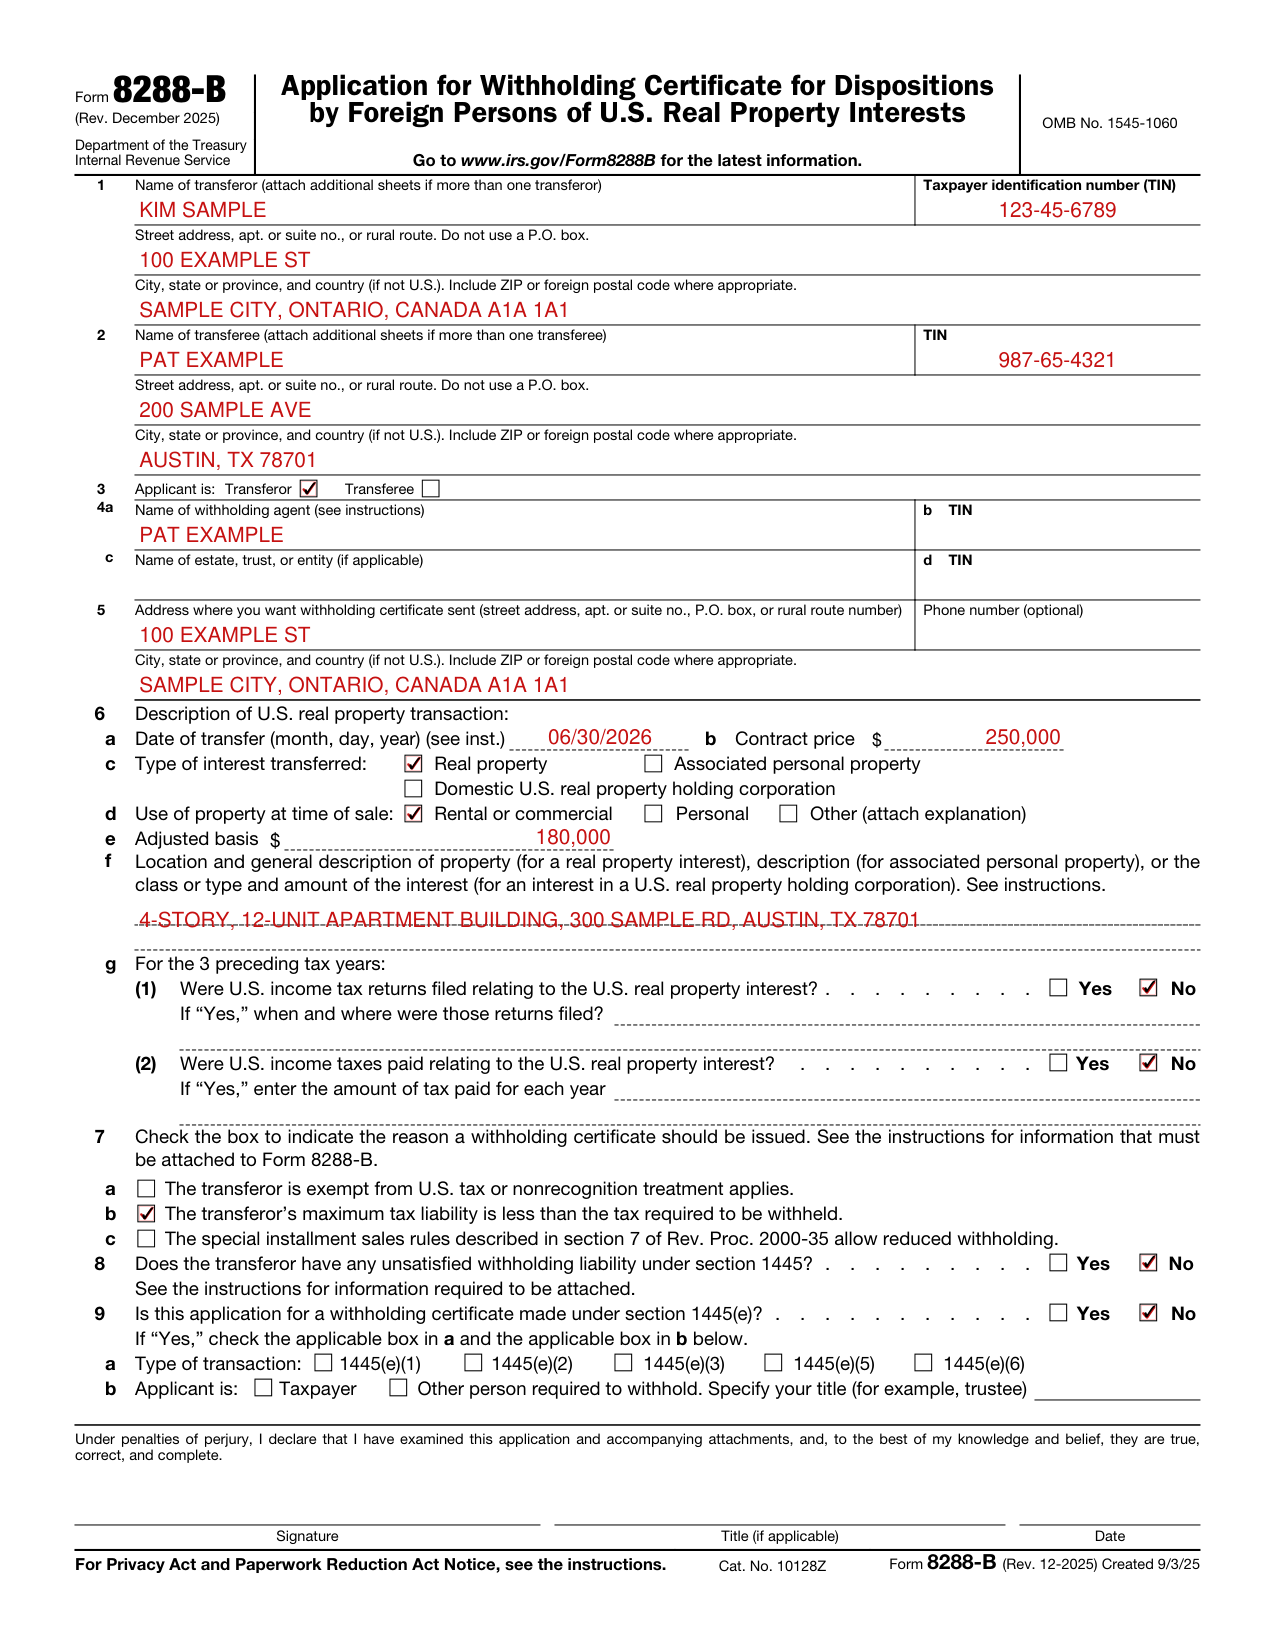
How to fill out Form 8288-B, box by box
Lines 1 and 2, the transferor and the transferee
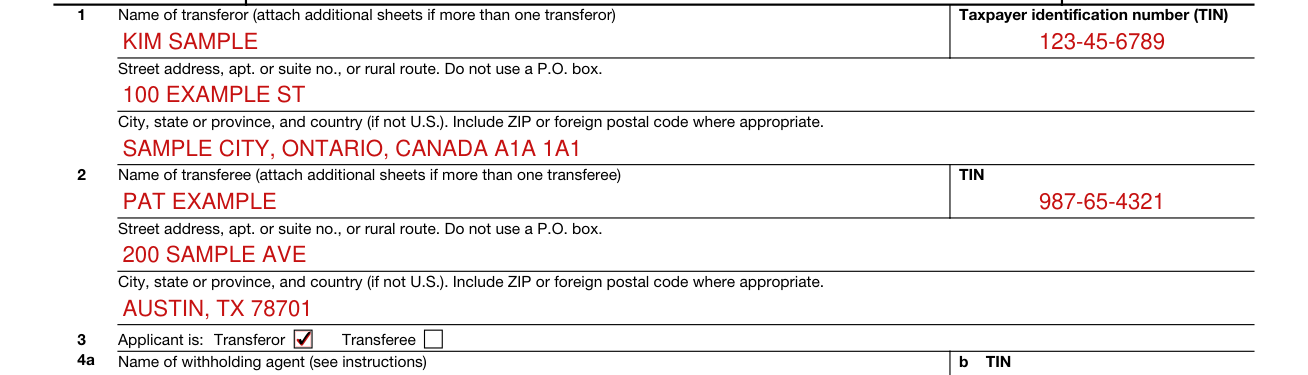
On line 1, enter the name, street address, and TIN of the transferor.
On line 2, enter the name, street address, and TIN of the transferee.
On lines 1 and 2, if there are multiple transferors or transferees, attach additional sheets giving the required information about each one.
On lines 1 and 2, enter the street address, apt. or suite no., or rural route, and do not use a P.O. box.
On lines 1 and 2, enter the city, state or province, and country (if not U.S.), and include the ZIP or foreign postal code where appropriate.
For U.S. individuals, the TIN is a social security number (SSN). For all other entities, it is an employer identification number (EIN).
Lines 3 and 4, the applicant and the withholding agent
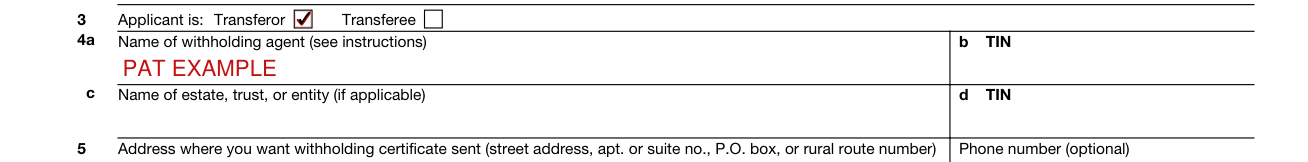
On line 3, mark Transferor or Transferee as the applicant.
On line 4a, the withholding agent will normally be the buyer or other transferee as described in section 1445(d)(4).
On line 4b, if you are not applying for this withholding certificate in your personal capacity, enter your SSN or ITIN.
On line 4c, if you are acting on behalf of an estate or trust, or are signing as an authorized person for an entity other than an individual (for example, a corporation, qualified investment entity, or partnership), enter the name of the estate, trust, or entity.
On line 4d, enter the EIN of the estate, trust, or entity.
Line 5, the address for the withholding certificate

On line 5, enter the address you want the IRS to use for purposes of returning the withholding certificate, with the city, state or province, and country (if not U.S.).
On line 5, the phone number is optional, and the address can be a street address, apt. or suite no., P.O. box, or rural route number.
Line 6, the U.S. real property transaction
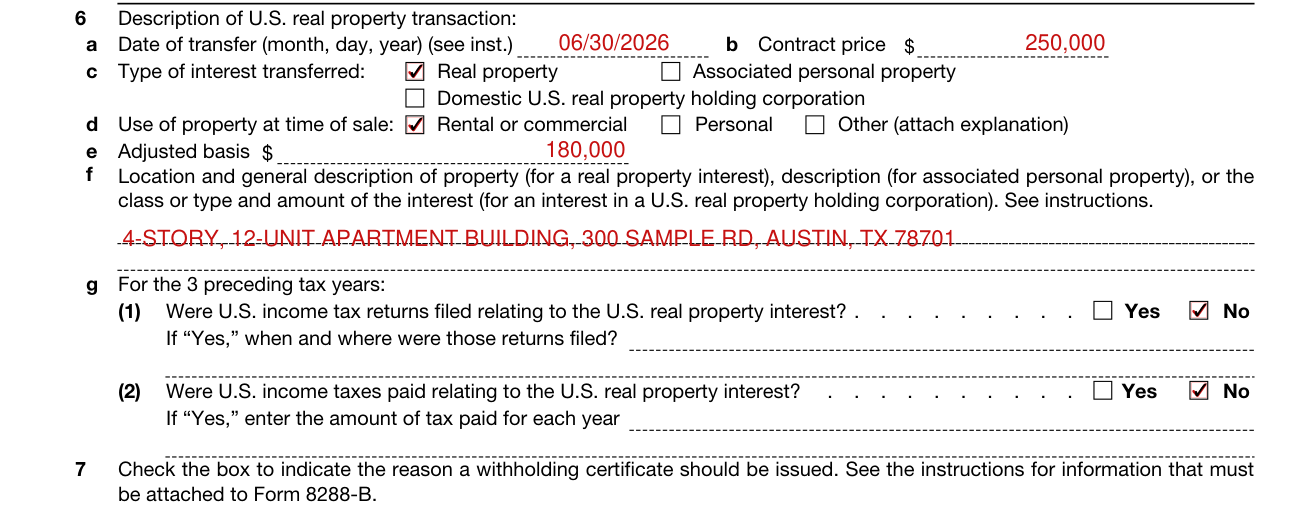
On line 6a, enter the date of transfer (month, day, year), with the year as a four-digit number (for example, “2025”).
Common mistake: An application that is not substantially complete when submitted will be rejected. For example, an application without a specific or estimated date of transfer will not be considered to be substantially complete.
On lines 6b and 6e, enter the contract price and the adjusted basis.
On line 6c, mark the type of interest transferred: real property, associated personal property, or domestic U.S. real property holding corporation. “Associated personal property” means property (for example, furniture) sold with a building.
On line 6d, mark the use of property at the time of sale: rental or commercial, personal, or other (attach explanation). Check “Other” if the property was used for both personal and rental use and attach an explanation.
On line 6f, enter the address and description of the property (for example, “10-story, 100-unit luxury apartment building”).
On line 6f, for a real estate holding corporation interest transferred, enter the class or type and amount of the interest (for example, “10,000 shares Class A Preferred Stock XYZ Corporation”).
On line 6g, for the 3 preceding tax years, mark Yes or No for (1): were U.S. income tax returns filed relating to the U.S. real property interest? If “Yes,” enter when and where those returns were filed. Mark Yes or No for (2): were U.S. income taxes paid relating to the U.S. real property interest? If “Yes,” enter the amount of tax paid for each year.
Line 7, the reason a withholding certificate should be issued
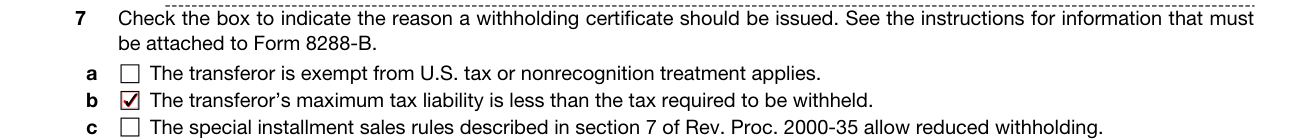
On line 7, check the box to indicate the reason a withholding certificate should be issued. See the instructions for information that must be attached to Form 8288-B.
Line 7a is for this reason: the transferor is exempt from U.S. tax, or nonrecognition treatment applies.
If you checked the box on line 7a, attach: A brief description of the transfer. A summary of the law. Facts supporting the claim of exemption or nonrecognition. Evidence that the transferor has no unsatisfied withholding liability. The most recent assessed value for state or local property tax purposes of the interest to be transferred, or other estimate of its fair market value.
A nonresident alien or foreign corporation must also attach a statement of the adjusted basis of the property immediately before the distribution or transfer.
Line 7b is for this reason: the transferor's maximum tax liability is less than the tax required to be withheld.
If you checked the box on line 7b, attach a calculation of the maximum tax that can be imposed on the disposition. You must also include a statement signed by the transferor under penalties of perjury that the calculation and all supporting evidence is true and correct to the best knowledge of the transferor.
Line 7c is for this reason: the special installment sales rules described in section 7 of Rev. Proc. 2000-35 allow reduced withholding.
Line 8, unsatisfied withholding liability
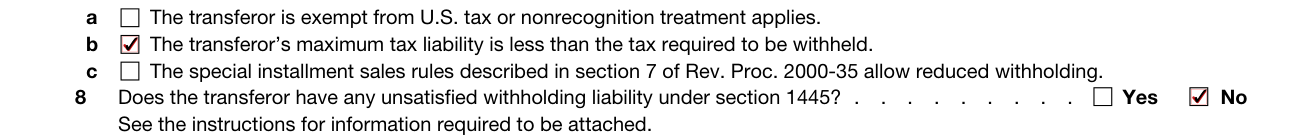
On line 8, mark Yes or No: does the transferor have any unsatisfied withholding liability under section 1445?
On line 8, you must provide a calculation of the transferor's unsatisfied withholding liability or evidence that it does not exist.
Line 9, applications under section 1445(e)

On line 9, mark Yes or No: is this application for a withholding certificate made under section 1445(e)? If “Yes,” check the applicable box in 9a and the applicable box in 9b.
On line 9a, if the transaction is subject to withholding under section 1445(e), check the box to indicate which provision of section 1445(e) applies: 1445(e)(1), 1445(e)(2), 1445(e)(3), 1445(e)(5) or 1445(e)(6).
On line 9b, indicate whether the applicant is the taxpayer or the person required to withhold, and in what capacity that person is required to withhold. For another person required to withhold, specify your title (for example, trustee).
Signature, Title (if applicable) and Date
Under penalties of perjury, you declare that you have examined this application and accompanying attachments, and, to the best of your knowledge and belief, they are true, correct, and complete.
Sign on the Signature line, and enter the Title (if applicable) and the Date.
The application may also be signed by an authorized agent with a power of attorney. Form 2848, Power of Attorney and Declaration of Representative, can be used for this purpose.
Applying as the transferor
You are the transferor and apply for a withholding certificate
A transferor that applies for a withholding certificate must notify the transferee in writing that the certificate has been applied for on the day of or prior to the transfer.
The IRS will normally act on an application within 90 days of receipt of all information necessary to make a proper determination.
Common questions about Form 8288-B
Where do I file it?
Form 8288-B and other applications for a withholding certificate must be sent to the Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409.
Is there a penalty?
Failure to provide this information in a timely manner, or providing false information, may subject you to penalties.
When is this form not the right one?
Do not use this form for applications based on an agreement for the payment of tax with conforming security, for blanket withholding certificates under Rev. Proc. 2000-35, or other than the three types described.
Sources
[1] Form 8288-B (Rev. December 2025), Department of the Treasury, Internal Revenue Service (the Official source link on this page).