

Form BOE-100-B at a glance
What it is: BOE-100-B is the State of California Board of Equalization Statement of Change in Control and Ownership of Legal Entities.
Where and when to file: Submit completed form to: State Board of Equalization, County-Assessed Properties Division (MIC:64), PO Box 942879, Sacramento, CA 94279-0064.
INSTRUCTIONS FOR COMPLETING BOE-100-B STATEMENT OF CHANGE IN CONTROL AND OWNERSHIP OF LEGAL ENTITIES Filing Requirements for Legal Entities Whenever there is a change in control (CIC) pursuant to section 64(c) of the Revenue and Taxation Code (R&TC) or a change in ownership (CIO) pursuant to R&TC section 64(d) of a legal entity, and the legal entity owned or leased interests in real property located in California as of that date, the person or legal entity acquiring ownership control or the legal entity that has undergone a CIO must file the BOE-100-B, Statement of Change in Control and Ownership of Legal Entities (statement), with the Board of Equalization (BOE) within 90 days of the CIC or ownership (R&TC sections 480.1 and 480.2).[2]
A filled-in Form BOE-100-B example: a legal entity answers a written request from the BOE
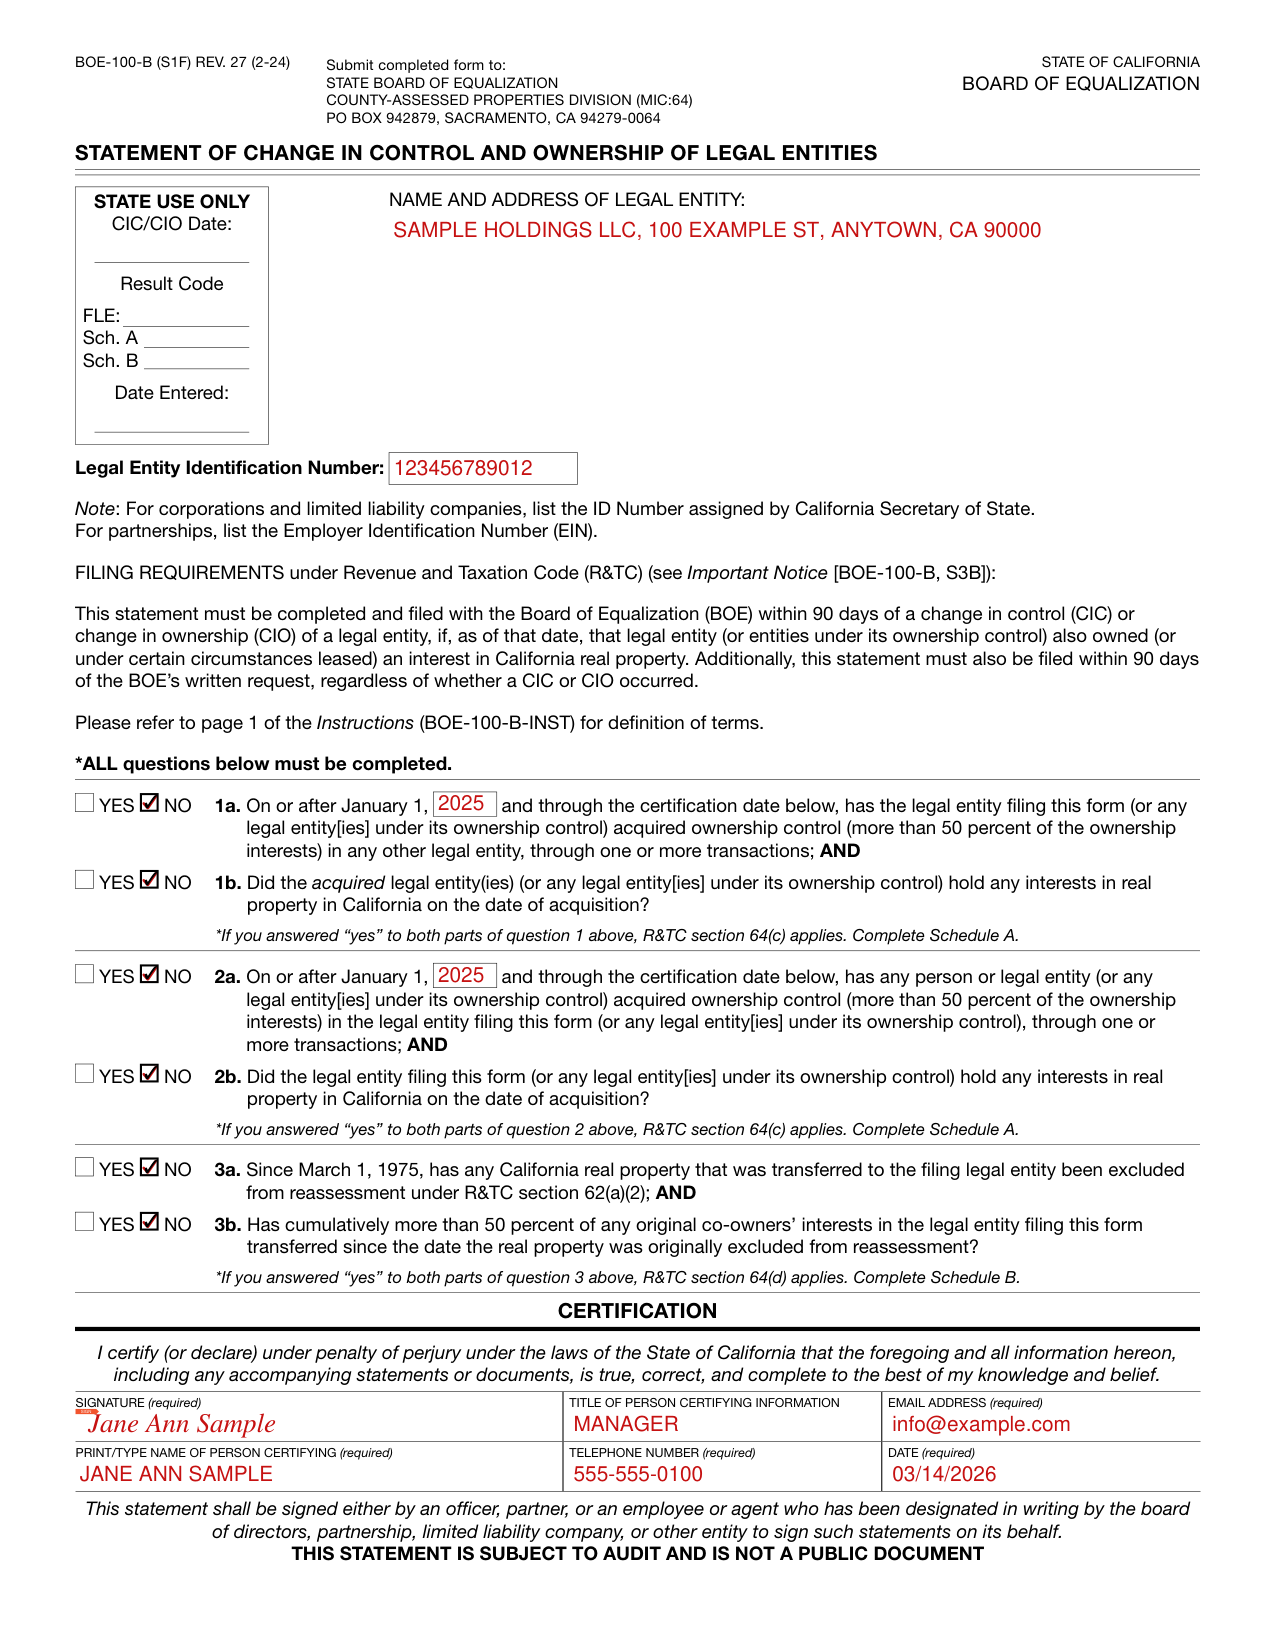
How to fill out Form BOE-100-B, box by box
Name and address of legal entity, and Legal Entity Identification Number
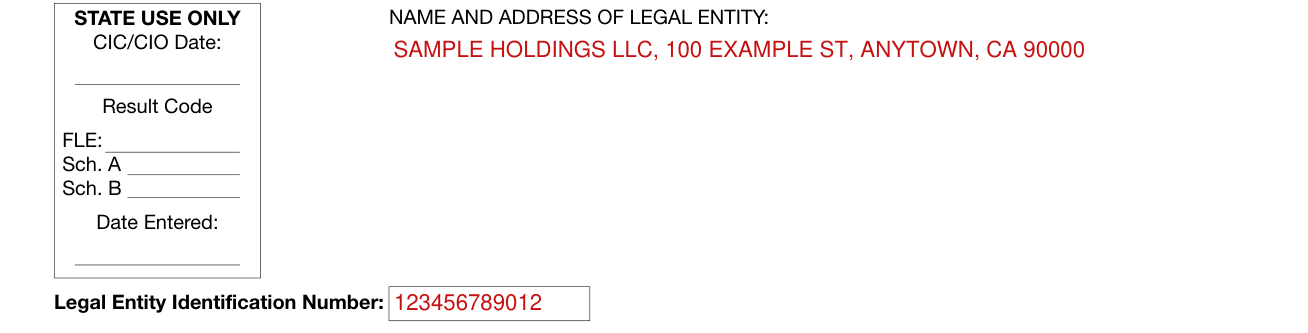
Box 3, Name and Address of Legal Entity: Provide the name and address of the legal entity filing the statement.
Box 3, Legal Entity Identification Number: For domestic and foreign (out of state or country) corporations and limited liability companies, provide the identification number assigned by the California Secretary of State; for partnerships, provide the Employer Identification Number (EIN).[2]
Questions 1a and 1b: acquired ownership control in another legal entity
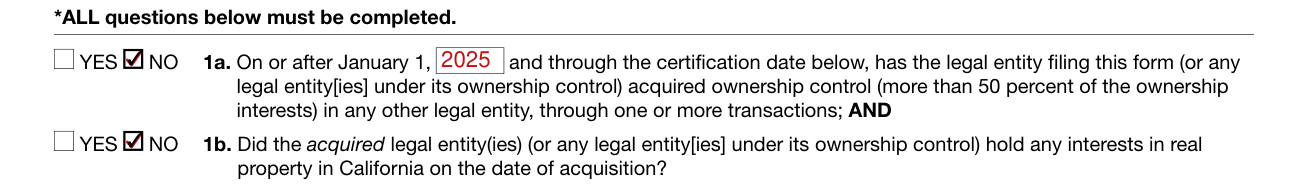
*If you answered “yes” to both parts of question 1 above, R&TC section 64(c) applies. Complete Schedule A.
1a. Indicate if the filing legal entity (or any legal entity[ies] under its ownership control) acquired more than 50 percent of the ownership interest in any other legal entity(ies) since the indicated date.
1b. Indicate if the acquired legal entity(ies) (or any legal entity[ies] under its ownership control) held an interest in California real property, as of the date of acquisition.
If the BOE sent a written request to file a BOE-100-B, the preprinted year represents the period for which information is being sought.[2]
Questions 2a and 2b: acquired ownership control in the legal entity filing this form
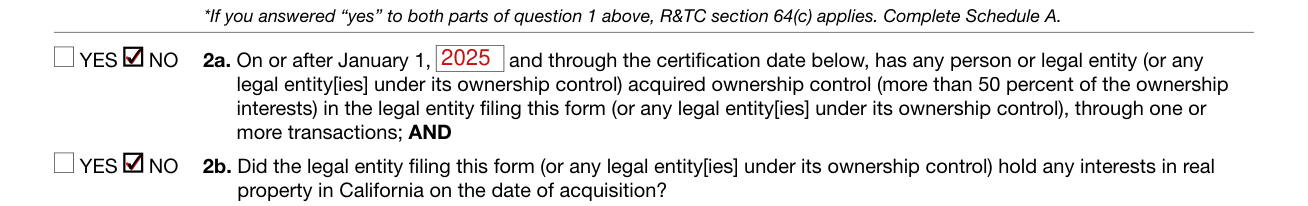
*If you answered “yes” to both parts of question 2 above, R&TC section 64(c) applies. Complete Schedule A.
2a. Indicate if a person or a legal entity obtained more than 50 percent of the ownership interest in the filing legal entity (or any legal entity[ies] under its ownership control) since the indicated date.
2b. Indicate if the acquired (filing) legal entity(ies) (or any legal entity[ies] under its ownership control) held an interest in California real property as of the date of acquisition.[2]
Questions 3a and 3b: real property excluded from reassessment under R&TC section 62(a)(2)
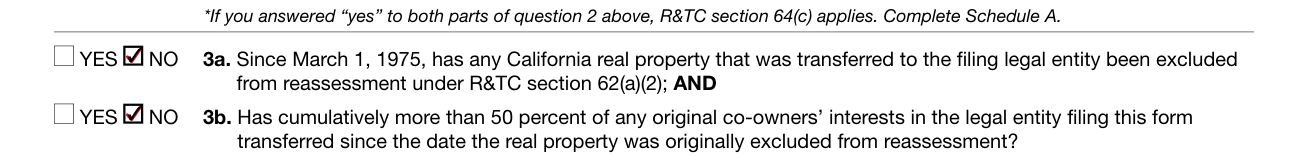
*If you answered “yes” to both parts of question 3 above, R&TC section 64(d) applies. Complete Schedule B.
3a. Since March 1, 1975, an interest in real property has been transferred to the filing legal entity in a transaction that was excluded from reassessment pursuant to R&TC section 62(a)(2); and Revenue and Taxation Code Section 62(a)(2) Under this provision, a transfer of real property to a legal entity does not result in a reassessment if the transfer results in merely a change in the method of holding title and the proportional ownership interests in the real property are exactly the same before and after the transfer.
3b. After such transfer, the original co-owners have cumulatively transferred in one or more transactions more than 50 percent of their interests in the filing legal entity.[2]
Certification: signature, title, email address, telephone number and date
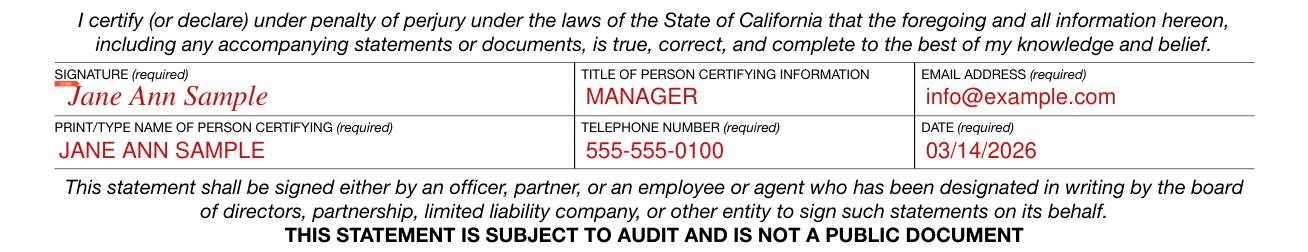
Certification Complete the certification by signing the statement. Include the title of the person certifying, email address, telephone number, and the date signed.
Box 3, Note: An unsigned, electronic, or faxed statement is not considered complete and you may be subject to penalty.[2]
More rules for Form BOE-100-B
Change in Control-R&TC section 64(c)-A change in control occurs when any person or legal entity obtains more than 50 percent of the ownership interest in a legal entity; control may be obtained directly or indirectly.[2]
Schedule A, Schedule B and other situations
You answered “yes” to both parts of question 1 or question 2: complete Schedule A
Complete this schedule if you answered “yes” to both parts of either question 1 or 2 on the certification page (S1F)
Complete one Schedule A for each directly acquired entity and each entity or subsidiary under the control of each directly acquired entity (see page 3 of the Instructions [BOE-100-B-INST]).
Item 1a: Provide the requested information pertaining to the acquired legal entity and any entity under its ownership control. Include the legal entity identification number for each entity involved in the transfer.
Item 1b: Provide the requested information pertaining to the acquiring person or legal entity.
Item 2a: Provide the date ownership control was obtained (for example, date of acquisition).
Item 2b: Provide a description of the transaction.
Item 2c: Provide the name of the entity or subsidiary, the identification number, and a description of the relationship for all indirectly acquired entities.
Item 3: Provide the name of the person or legal entity and the percentage interest held by each before and after the date of acquisition in the acquired legal entity.
Documentation Required for 4b and 4c: Submit organizational charts that show the ownership interests in the entity before and after the date it underwent a CIC or CIO. If an indirect change has occurred, identify all entities involved.
Item 5-Real Property Schedule (Table a): Identify the interest in real property (refer back to page 1 of the instructions for the definition of interest in real property) in California owned or leased by the acquired legal entity (or any legal entity[ies] under its ownership control) as of the date of the CIC.[2]
You answered “yes” to both parts of question 3: complete Schedule B
If you answered “yes” to both parts of question 3 on the certification page (S1F), complete this schedule; however, if you answered “yes” to both parts of questions 2 and 3 on the certification page (S1F), you are required to complete both Schedule A and Schedule B.
SCHEDULE B Item 1: Provide the date(s) of transfer(s) and a description of the transaction in which the real property(ies) was transferred to the filing legal entity that was previously excluded from reassessment under R&TC section 62(a)(2), which created the original co-owner status.
Item 3a: Provide a description of the transfer(s) that cumulatively resulted in a transfer of more than 50 percent of the original co-owners' interests in the filing legal entity, since the date original co-owner status was created.
Item 3b: Provide the date(s) the original co-owner(s) transferred interest in the legal entity, name of the original co-owner(s), percentage interest transferred by the original co-owner(s), name of the current owner(s), and the percentage interest held by the current owner(s).[2]
Common questions about Form BOE-100-B
What is boe 100?
BOE-100-B is the State of California Board of Equalization Statement of Change in Control and Ownership of Legal Entities. Legal Entity Information and Resources Statements are processed by staff in the BOE's Legal Entity Ownership Program (LEOP).[2]
Who signs it?
This statement shall be signed either by an officer, partner, or an employee or agent who has been designated in writing by the board of directors, partnership, limited liability company, or other entity to sign such statements on its behalf.
Is there a deadline?
This statement must be completed and filed with the Board of Equalization (BOE) within 90 days of a change in control (CIC) or change in ownership (CIO) of a legal entity, if, as of that date, that legal entity (or entities under its ownership control) also owned (or under certain circumstances leased) an interest in California real property. Additionally, this statement must also be filed within 90 days of the BOE's written request, regardless of whether a CIC or CIO occurred. In addition, any legal entity is required to file a statement with the BOE within 90 days of the date of the BOE's request, regardless of whether a change in control or ownership of the legal entity has occurred.[2]
Where do I file it?
Submit completed form to: State Board of Equalization, County-Assessed Properties Division (MIC:64), PO Box 942879, Sacramento, CA 94279-0064.
Is there a penalty?
Penalty Information If a person or legal entity fails to file the statement timely with the BOE, as required by R&TC section 480.1 and 480.2, the penalty pursuant to R&TC section 482 is (1) 10 percent of the taxes applicable to the new base year value reflecting the CIC or CIO of the real property owned by the corporation, partnership, limited liability company, or legal entity, or (2) 10 percent of the current year's taxes on that property, if no CIC or CIO occurred.[2]
Where to get help with Form BOE-100-B
You may also contact the LEOP staff at 1-916-274-3410.[2]
Sources
[1] Form BOE-100-B (2-24), Statement of Change in Control and Ownership of Legal Entities, California State Board of Equalization (the Official source link on this page).