

PA Schedule C (Form PA-40 C) at a glance
What it is: PA Schedule C, Profit or Loss from Business or Profession (Sole Proprietorship), PA-40 C, from the PA Department of Revenue.
Where and when to file: Include with Form PA-40 or PA-41.
Use PA Schedule C to report income or loss from a business you operate or a profession you practice as a sole proprietor.
If you are a sole member of an LLC, complete PA Schedule C.
If you own or operate more than one business, you must submit a separate PA Schedule C for each business operation.
Even if you have no differences between your federal and Pennsylvania expenses, you must complete and include PA Schedule C to report your income for Pennsylvania personal income tax purposes.
What to bring and attach to PA Schedule C (Form PA-40 C)
Enter the name of the business owner.
Enter the SSN of the business owner.
A filled-in PA Schedule C (Form PA-40 C) example: a freelance designer with one expense
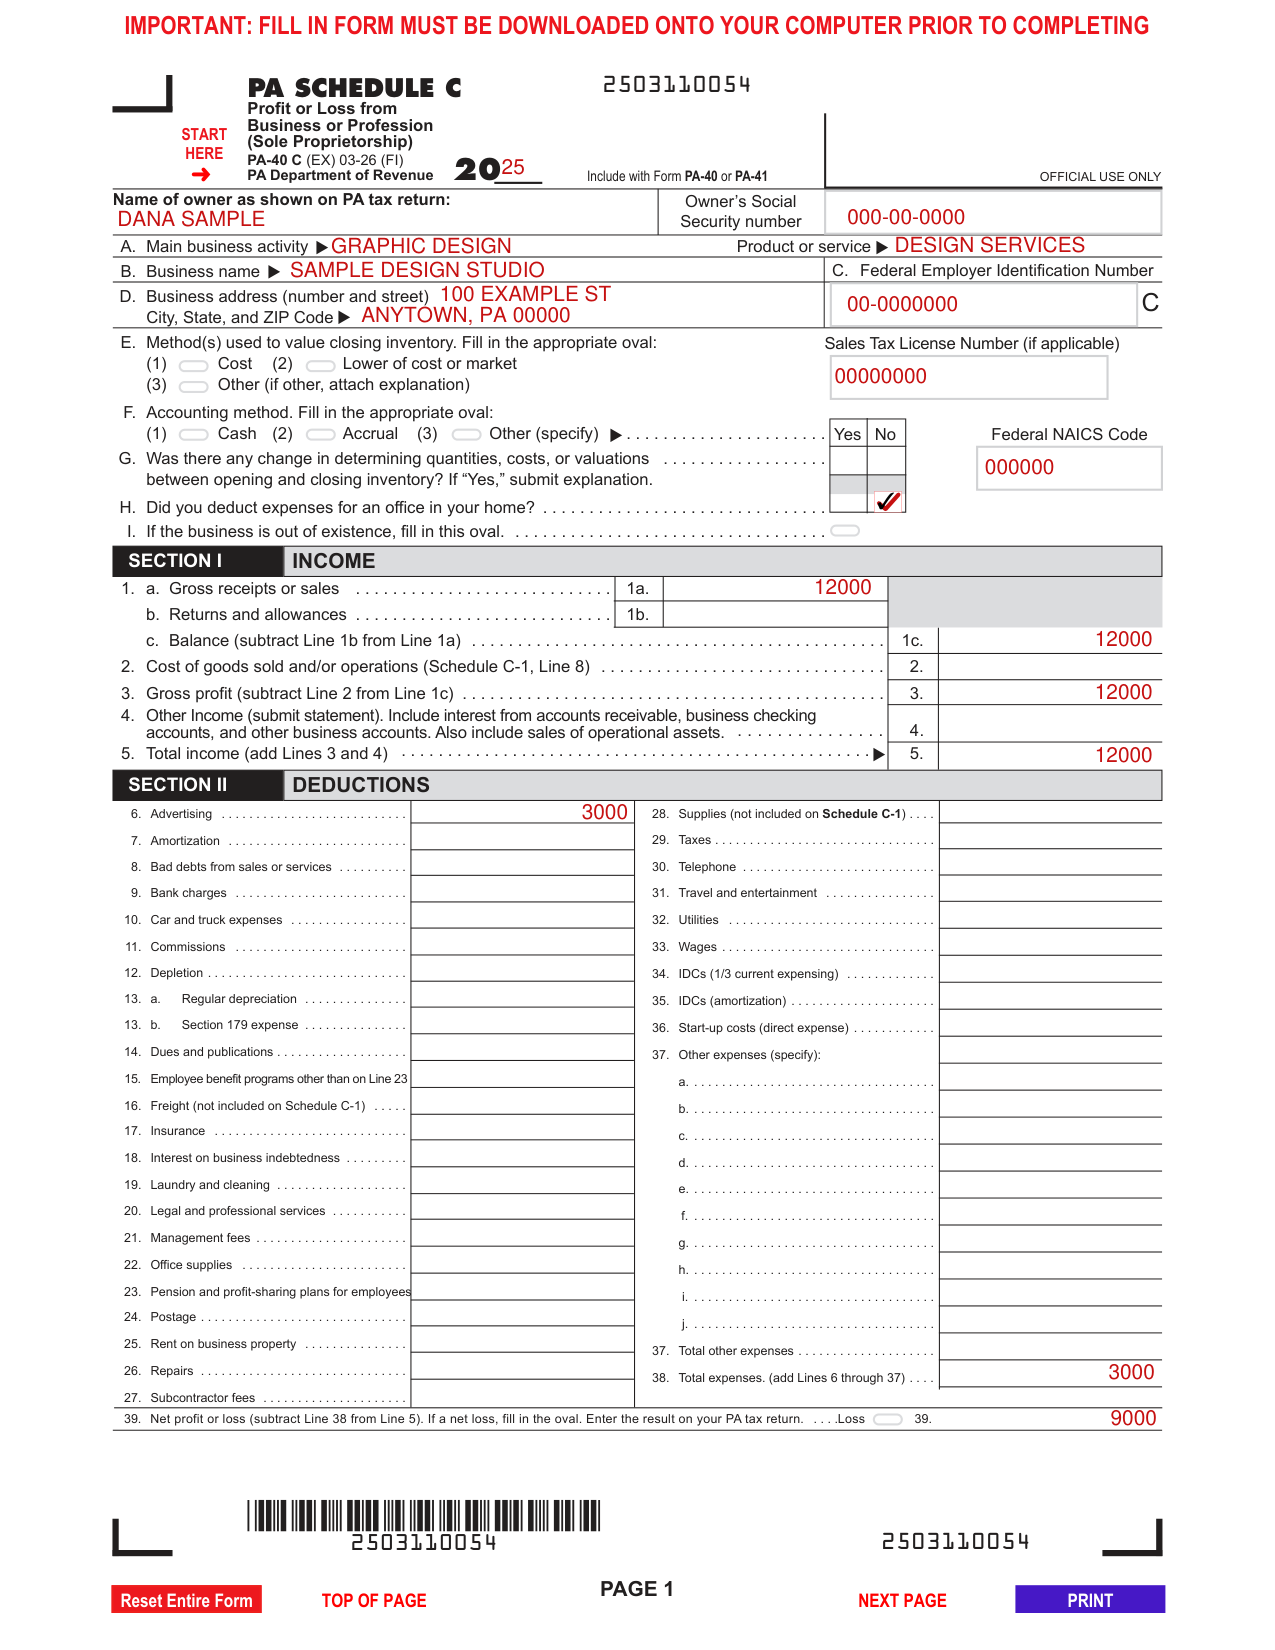
How to fill out PA Schedule C (Form PA-40 C), box by box
Business activity, name, FEIN and address (Lines A to D)
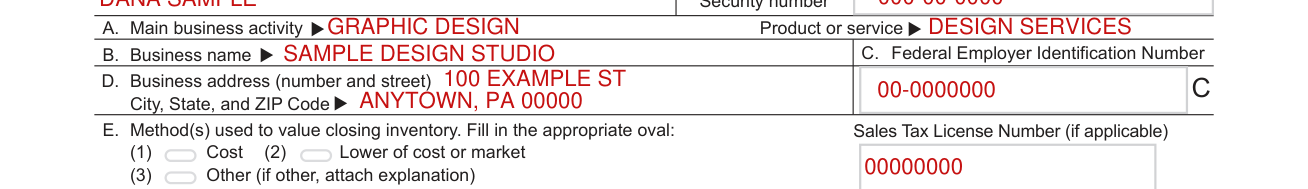
Line A, main business activity: Describe the business or professional activity that provided your principal source of income for Line 1. Use the same description you use for your Federal Schedule C. Enter the principal business or professional code you use on your Federal Schedule C.
Line B, business name: Enter the name of the business as you registered with the IRS.
Line C, Federal Employer Identification Number: Enter the Federal Employer Identification Number (FEIN) assigned to the business. If you do not have an FEIN for your federal Schedule C, leave this space blank.
Line D, business address: Enter the complete address of the business.
Closing inventory valuation and sales tax license number (Line E)

Line E, closing inventory valuation: Fill in the appropriate oval. Submit an explanation if necessary.
Enter your Pennsylvania Sales Tax License Number if you have one. Otherwise, leave this space blank.
Accounting method, inventory changes and Federal NAICS code (Lines F and G)

Line F, accounting method: Fill in the oval for the accounting method you use for this business. Submit an explanation if necessary.
Line G, inventory changes: Check “Yes” or “No” for this question. Submit an explanation if necessary.
Provide your Federal NAICS Code as identified on your Federal Schedule C.
Office in-home and out of business (Lines H and I)

Line H, office in-home: Check “Yes” if you deduct expenses for an office in-home. Check “No” if you do not deduct expenses for an office in-home.
Line I, out of business: If the business is out-of-existence at the end of the tax year for which you are filing, fill in the oval.
Income (Section I)
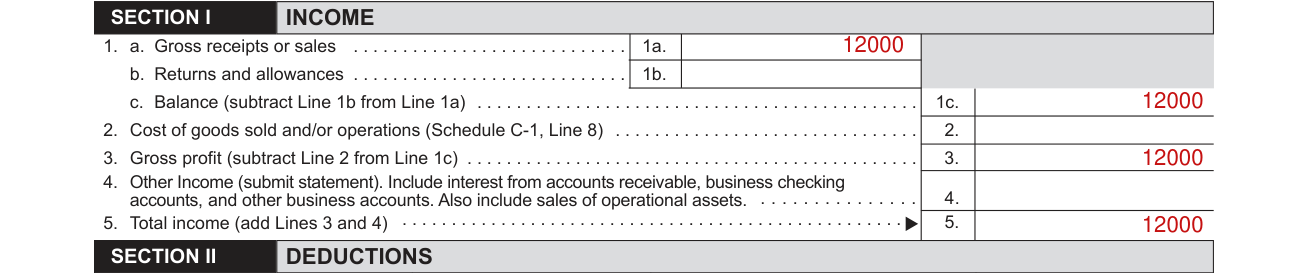
Line 1a, gross receipts or sales: Include all amounts you received in operating your business or profession.
Line 1b, returns and allowances, and Line 2, cost of goods sold and/or operations (Schedule C-1, Line 8): The Line 1b amount is the same for both Pennsylvania and federal purposes. The Line 2 amount is the same for Pennsylvania and federal purposes. If you report a different amount for Pennsylvania, submit an explanation.
Line 1c, Balance: subtract Line 1b from Line 1a.
Line 4, other income: Submit a statement explaining the amount you enter.
Deductions (Section II)
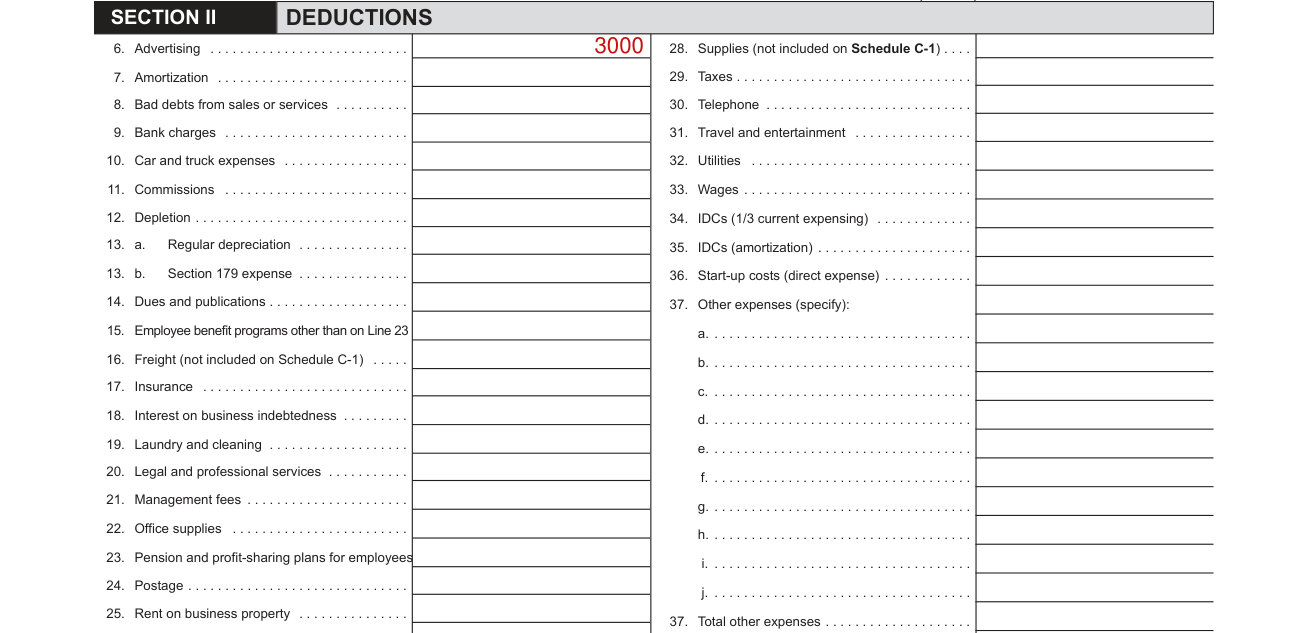
Section II, deductions: Use generally accepted accounting principles and practices to maintain your books and records and report your expenses from your business or professional activity.
PA law does not impose dollar or percentage limitations on allowable expenses. You may deduct 100 percent of the PA allowable business or professional expenses incurred during the taxable year.
Line 10, car and truck expenses: You may deduct 100 percent of your actual vehicle expenses or you may use the federal standard mileage rate. If you use the federal standard mileage rate, you may not deduct any actual operating expenses, including depreciation and lease costs.
Line 29, taxes: Deduct tax expenses other than taxes based on income. You may not deduct taxes based on net income, federal income taxes or the one-half of self-employment taxes the IRS allows.
Total expenses and net profit or loss (Lines 38 and 39)
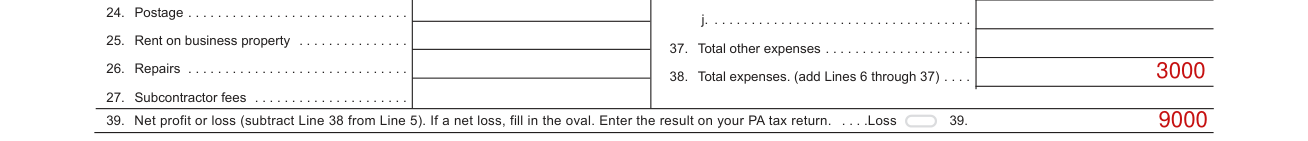
Line 38, total expenses: Add Lines 6 through 37.
Line 39, net profit or loss (subtract Line 38 from Line 5). If a net loss, fill in the oval. Enter the result on your PA tax return.
Line 39, net profit or loss: In calculating net profit or loss from your business or profession, report your entire loss in this taxable year.
Unless a loss results from an activity where a net profit has not been realized in at least two years of a five consecutive-year period, an owner may deduct all losses from a business or profession in the taxable year realized.
Schedule C-1 cost of goods sold and/or operations
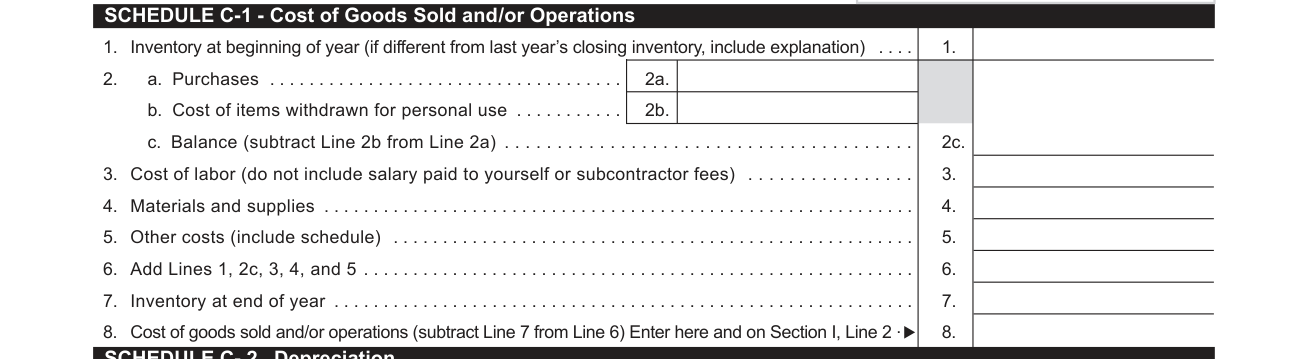
Schedule C-1, cost of goods sold and/or operations: Generally, if you engaged in a trade or business in which the production, purchase, or sale of merchandise was an income-producing factor, you must consider inventories at the beginning and end of your tax year.
In determining inventory value, use the cost, lower of cost or market, or other method allowable under generally accepted accounting principles and practices.
If you change methods of valuing inventory, restate the value at the beginning of the year based on the changed method, and include an explanation.
Line 3, cost of labor: do not include salary paid to yourself or subcontractor fees.
Line 8, cost of goods sold and/or operations: subtract Line 7 from Line 6.
Depreciation, spouses, statutory employees, property sales and farming
You use a depreciation method other than federal depreciation
Schedule C-2, depreciation: Complete this schedule if you are using a depreciation method other than federal depreciation reported on your federal Schedule C.
Pennsylvania PIT law does not conform to Federal law to allow federal bonus depreciation.
For assets where basis is different between federal and PA, you must calculate depreciation expenses on a straight-line basis.
You and your spouse own a business
If you are married and you jointly owned the business with your spouse, you must complete separate PA Schedule C's.
If you and your spouse have separate business activities, complete separate PA Schedule(s) C.
You are a federal statutory employee
Federal statutory employees may be required to report PA taxable income on Line 1a, PA-40, and use PA Schedule UE to deduct expenses.
You have a like-kind exchange or a sale of land and buildings
Form 8824: Do not report a like-kind exchange on PA Schedule C. PA law does not have like-kind exchange provisions.
For PA purposes, you may not include the sales of land and buildings on PA Schedule C unless the property sold is replaced.
You have farming activity
Report farming activity on PA Schedule F.
Sources
[1] PA Schedule C, Profit or Loss from Business or Profession (Sole Proprietorship), PA-40 C (EX) 03-26 (FI), PA Department of Revenue (the Official source link on this page).
