
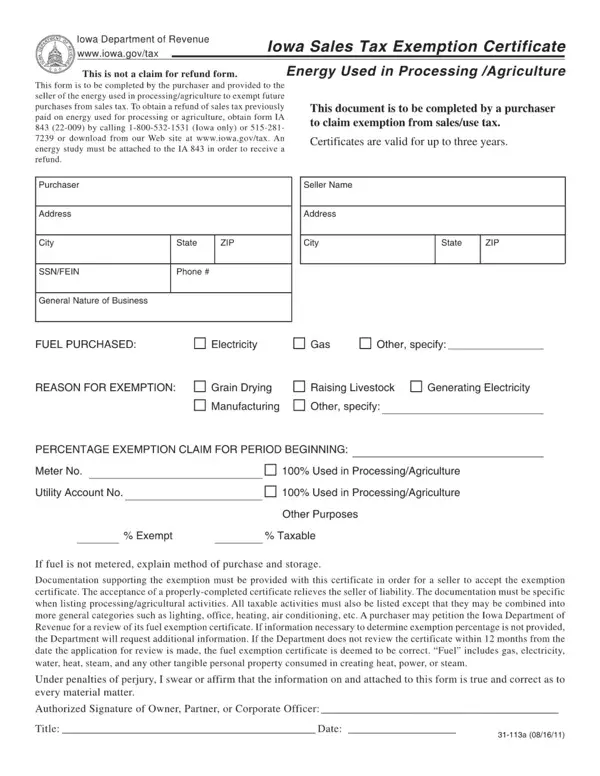

Form 31-014a at a glance
What it is: This document is to be completed by a purchaser claiming an exemption from sales tax, use tax, or excise tax.
Who signs: Iowa Sales/Use/Excise Tax Exemption Certificate Instructions 31-014d (09/08/2025): this exemption certificate must be completed by the purchaser claiming an exemption from sales, use, or excise tax and given to the seller.
A filled-in Form 31-014a example: a retailer buys for resale
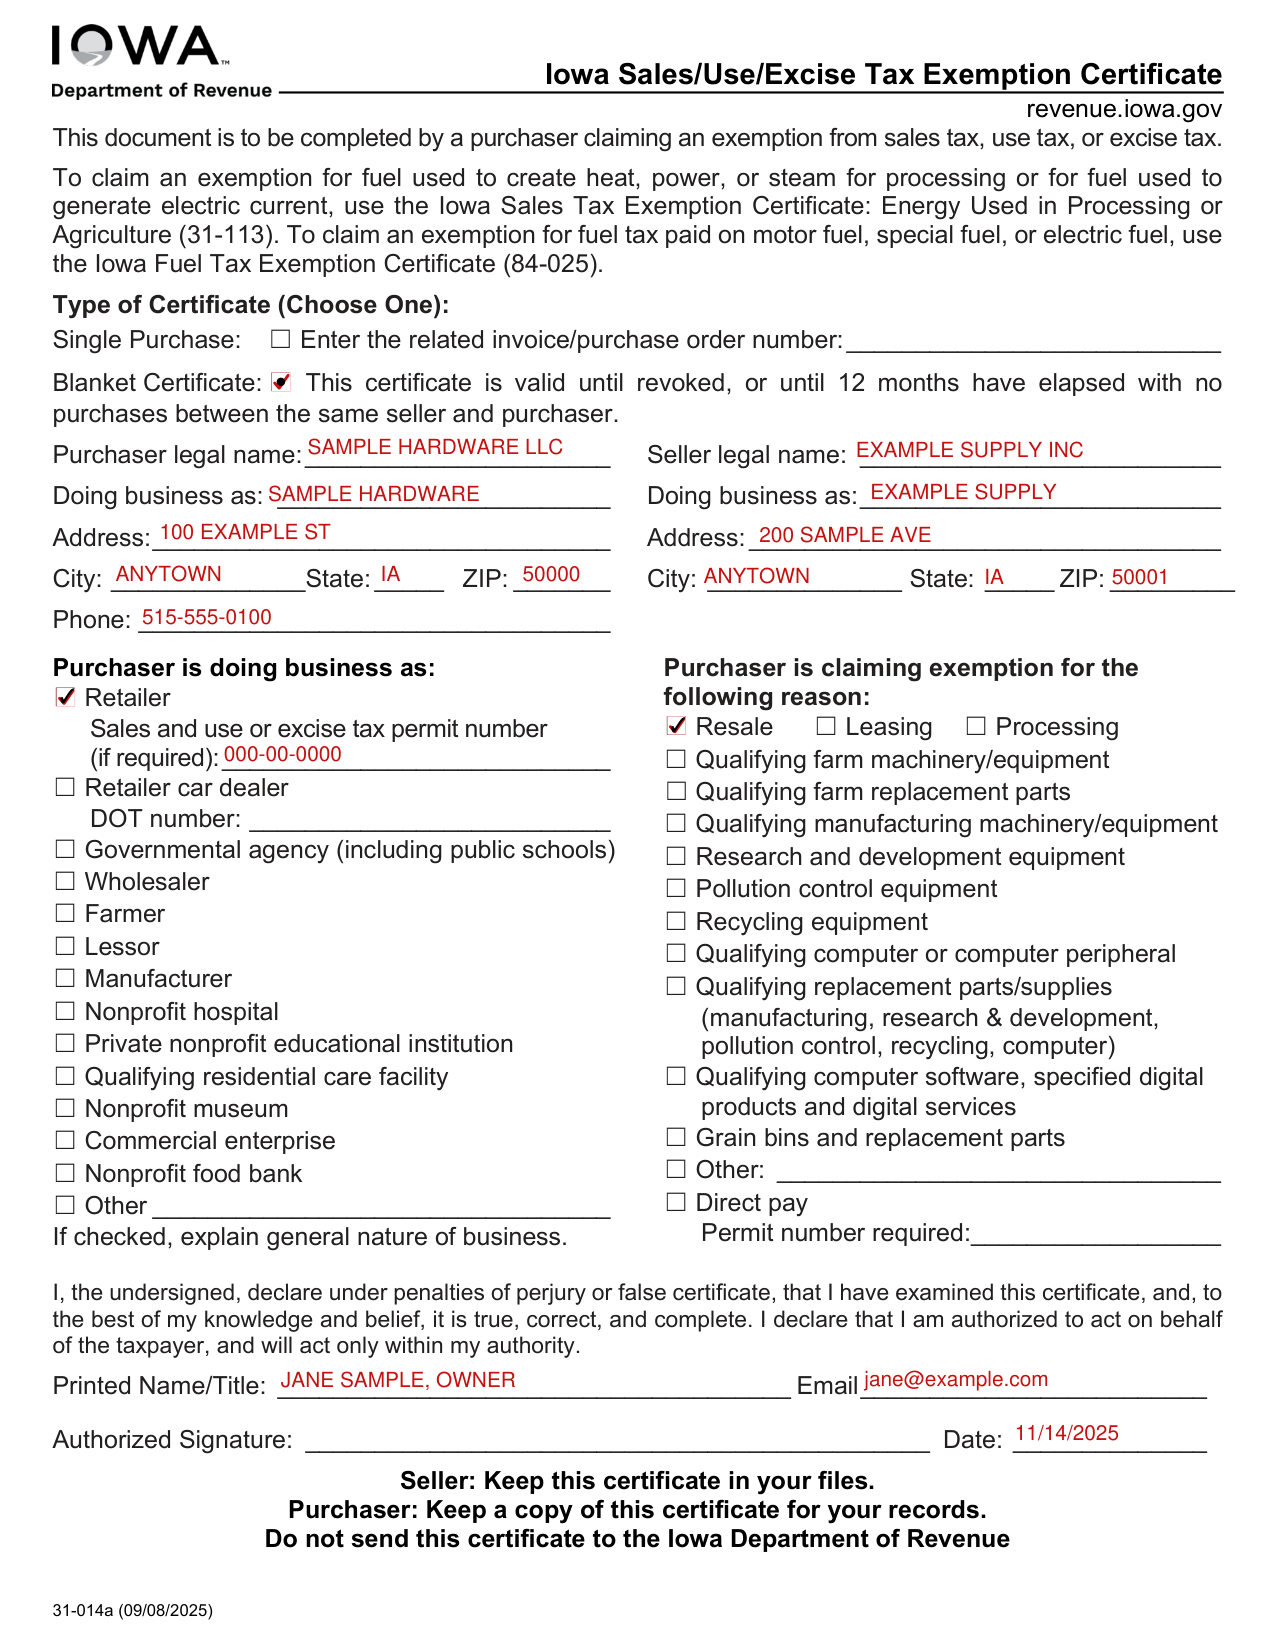
How to fill out Form 31-014a, box by box
Type of Certificate (Choose One)
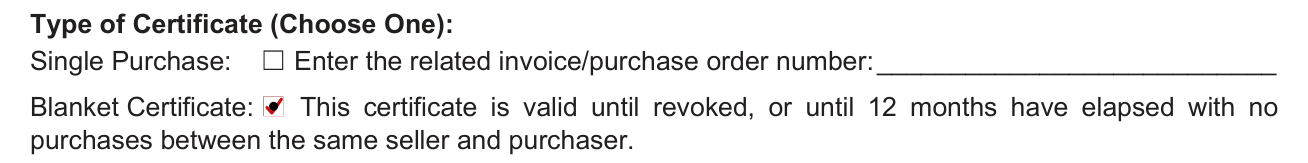
Under Type of Certificate (Choose One), check the box for a single purchase or a blanket certificate. If used for a single purchase, enter the related invoice/purchase order number.
If used for a blanket certificate, this certificate is valid until revoked, or canceled by the purchaser, or until 12 months have elapsed with no purchases between the same seller and purchaser.
Purchaser legal name and Seller legal name
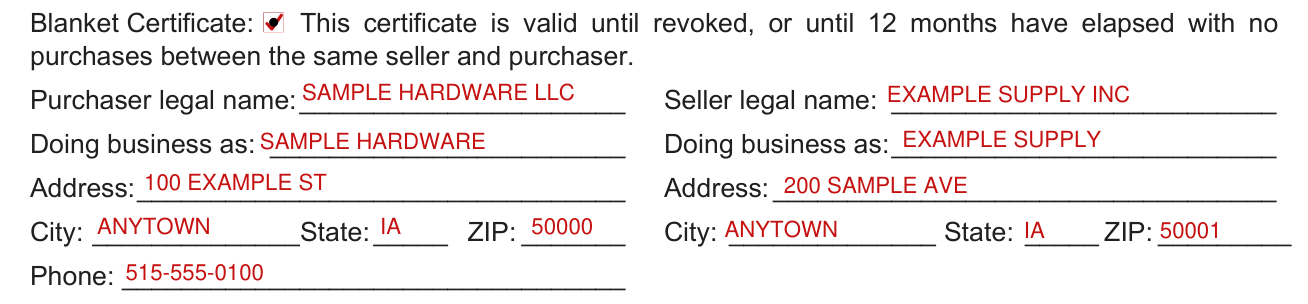
For the purchaser, enter the legal name, the doing business as name, the address, the city, state and ZIP, and the phone.
For the seller, enter the legal name, the doing business as name, the address, and the city, state and ZIP.
Purchaser is doing business as
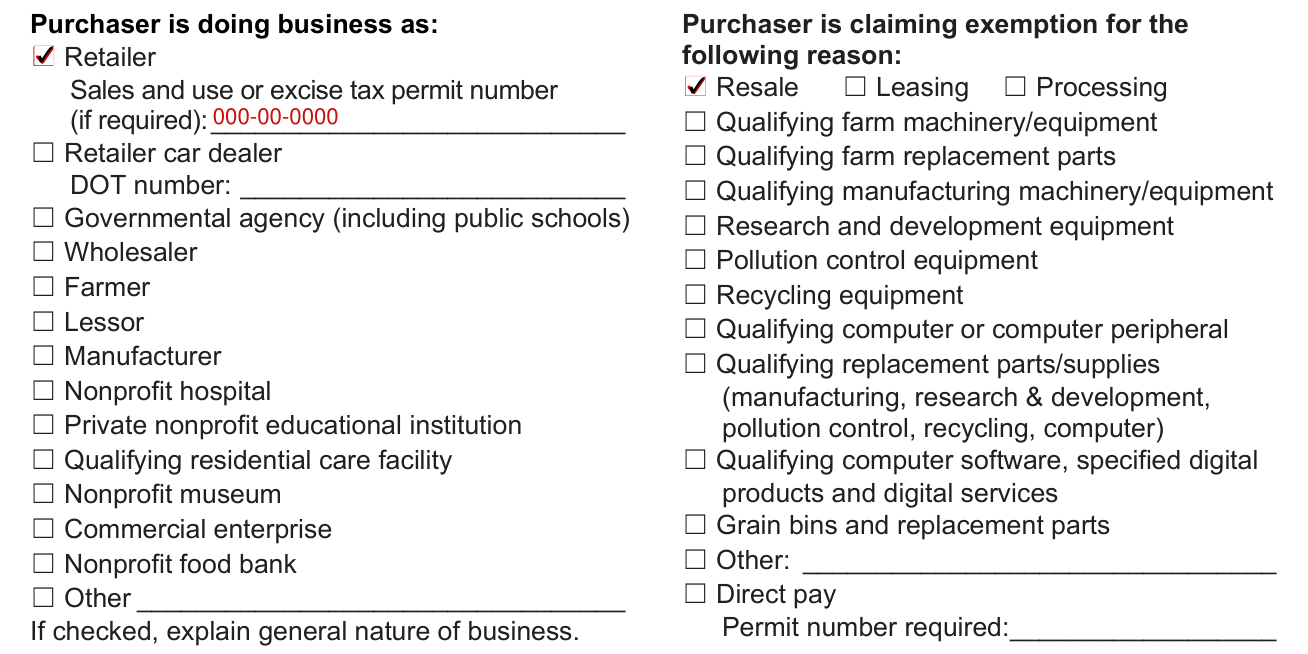
Under Purchaser is doing business as, check one of these: Retailer, Retailer car dealer, Governmental agency (including public schools), Wholesaler, Farmer, Lessor, Manufacturer, Nonprofit hospital, Private nonprofit educational institution, Qualifying residential care facility, Nonprofit museum, Commercial enterprise, Nonprofit food bank, or Other. If Other is checked, explain general nature of business. Enter the DOT number for Retailer car dealer.
Enter the sales and use or excise tax permit number (if required). Retailers with a sales and use tax permit number must enter it in the space provided.
Purchaser is claiming exemption for the following reason
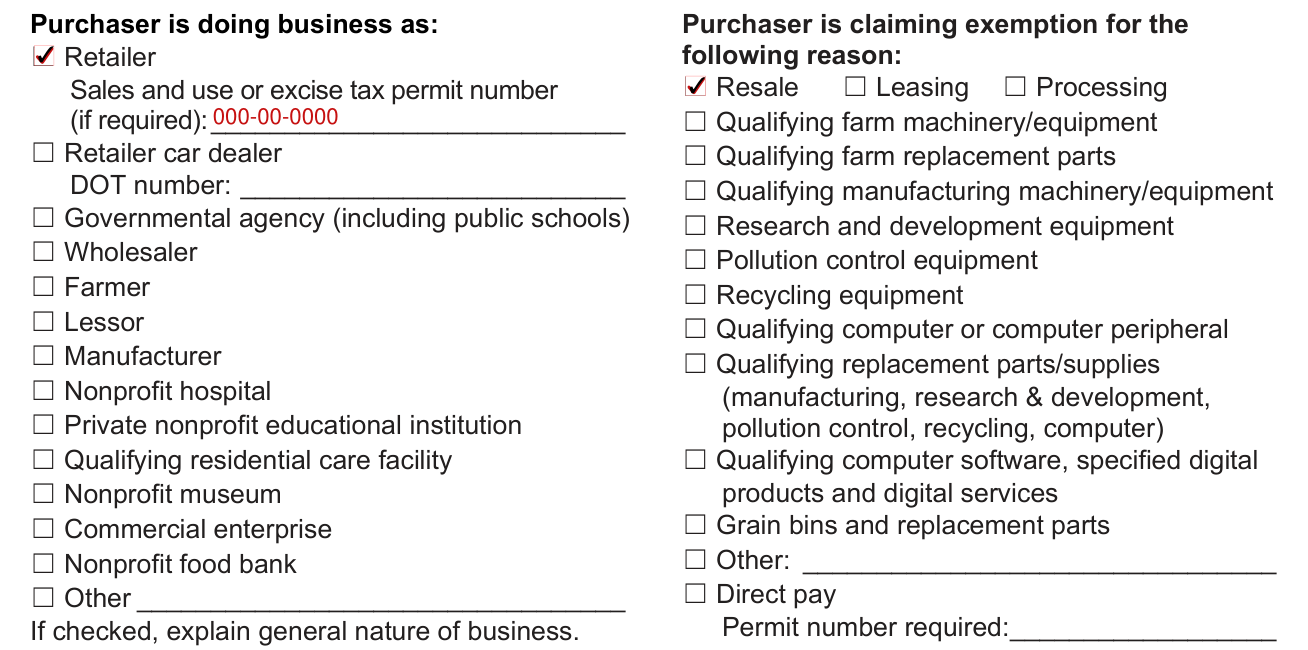
Purchaser is claiming exemption for the following reason: Resale, Leasing, Processing, Qualifying farm machinery/equipment, Qualifying farm replacement parts, Qualifying manufacturing machinery/equipment, Research and development equipment, Pollution control equipment, Recycling equipment, Qualifying computer or computer peripheral, Qualifying replacement parts/supplies (manufacturing, research & development, pollution control, recycling, computer), Qualifying computer software, specified digital products and digital services, Grain bins and replacement parts, Other, or Direct pay.
Direct pay: Businesses and individuals who pay their taxes directly to the Department, rather than to the seller, must enter their Direct Pay permit number in the space provided.
Printed Name/Title, Authorized Signature and Date
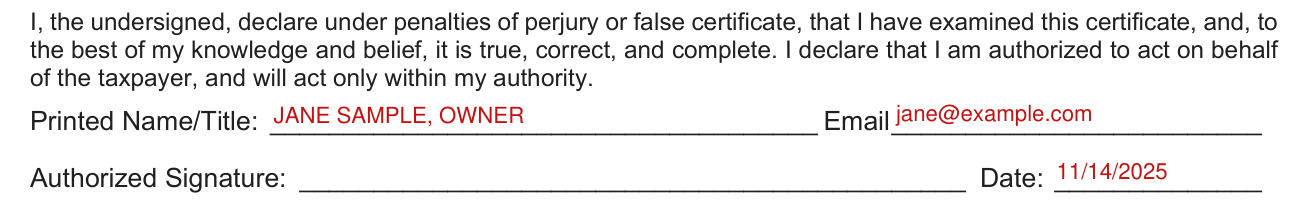
By signing you certify under penalties of perjury or false certificate that you have examined this certificate and, to the best of your knowledge and belief, it is true, correct, and complete, that you are authorized to act on behalf of the taxpayer, and that you will act only within your authority.
Enter the Printed Name/Title and the Email, then sign on the Authorized Signature line and enter the Date.
More rules for Form 31-014a
The seller must retain this certificate as proof that the exemption was properly claimed. The certificate must be complete to be accepted by the seller.
If your situation is different
Fuel exemptions
To claim an exemption for fuel used to create heat, power, or steam for processing or for fuel used to generate electric current, use the Iowa Sales Tax Exemption Certificate: Energy Used in Processing or Agriculture (31-113). To claim an exemption for fuel tax paid on motor fuel, special fuel, or electric fuel, use the Iowa Fuel Tax Exemption Certificate (84-025).
Resale
Resale: Any person in the business of selling who purchases taxable property or services for resale may claim this exemption. The purchaser may act as either a retailer or wholesaler and may not be required to have a sales and use tax permit.
If property or services purchased for resale or processing are used or disposed of by the purchaser in a nonexempt manner, the purchaser is responsible for the tax.
Processing
Processing: Exempt purchases for processing include tangible personal property that, by means of fabrication, compounding, manufacturing, or germination, becomes an integral part of other tangible personal property ultimately sold at retail; chemicals, solvents, sorbents, or reagents used, consumed, dissipated, or depleted in processing personal property intended to be sold ultimately at retail, and chemicals used in the production of free newspapers and shoppers' guides.
Qualifying manufacturing machinery/equipment
Qualifying manufacturing machinery/equipment: The item must be computers, machinery, equipment, replacement parts, supplies, or material used to construct or self-construct computers, machinery, equipment, replacement parts, or supplies used for one of the following purposes: 1. Directly and primarily used in processing by a manufacturer. 2. Directly and primarily used to maintain integrity or unique environmental conditions for the product. 3. Directly and primarily used in research and development of new products or processes. 4. Directly and primarily used in recycling or reprocessing of waste products.
Pollution control equipment
Pollution control equipment: The equipment must be used by a manufacturer primarily to reduce, control, or eliminate air or water pollution.
Qualifying computer software, specified digital products and digital services
Qualifying computer software, specified digital products, and digital services: The product purchased may only be those listed in Iowa Code section 423.3(104), must be purchased by a commercial enterprise as defined in Iowa Code section 423.3(104), and must be used exclusively by the commercial enterprise.
Private nonprofit educational institutions
Private nonprofit educational institutions: Purchases made by Iowa private nonprofit educational institutions as defined in Iowa Code section 423.3(17) used for educational purposes are exempt. Not exempt from sales and use tax are purchases by most other private nonprofit organizations such as churches, fraternal organizations, clubs, etc., for use by those organizations.
Nonprofit food banks
Nonprofit food banks: Purchases of tangible personal property and taxable services by nonprofit food banks as defined in Iowa Code section 423.3(107) are exempt from sales and use tax if the property or services are used by the food bank for a charitable purpose. Iowa Administrative Code rule 701-212.1 provides more information on what constitutes a charitable purpose. Purchases by these organizations of specified digital products are taxable.
Common questions about Form 31-014a
Is there a deadline?
To be valid, this certificate must be completed and be in effect within 90 days of the date of sale.
Where do I file it?
Seller: Keep this certificate in your files. Purchaser: Keep a copy of this certificate for your records. Do not send this certificate to the Iowa Department of Revenue.
Sources
[1] Form 31-014a (09/08/2025), Iowa Sales/Use/Excise Tax Exemption Certificate, Iowa Department of Revenue (the Official source link on this page).