
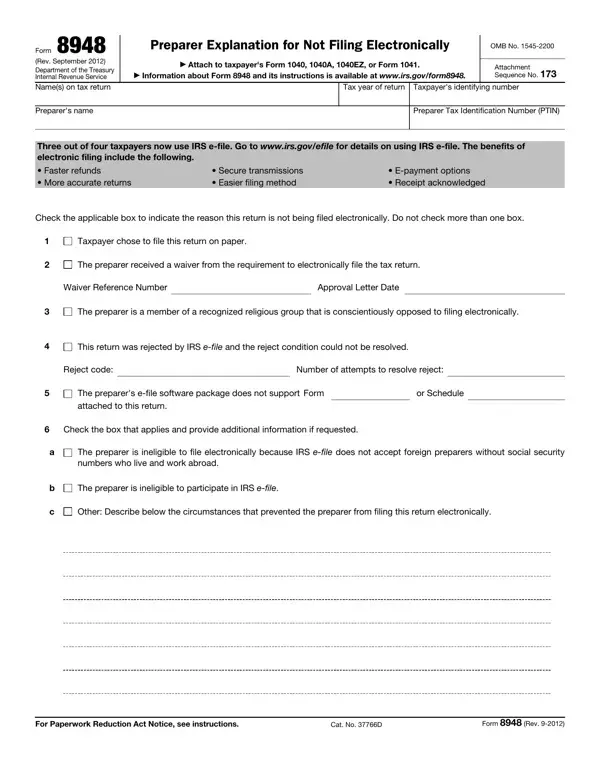
Form 8948 at a glance
What it is: Form 8948, Preparer Explanation for Not Filing Electronically, is used only by specified tax return preparers (defined in this form) to explain why a particular return is being filed on paper.
Where and when to file: File Form 8948 with the tax return that is filed on paper. When to file: attach this form to the paper tax return you prepare and furnish to the taxpayer for the taxpayer's signature.
A specified tax return preparer is a tax return preparer who is a preparer of covered returns and who reasonably expects (if the preparer is a member of a firm, the firm's members in the aggregate reasonably expect) to file 11 or more covered returns during a calendar year, as identified in section 7701(a)(36) and Regulations section 301.7701-15.
A specified tax return preparer may be required by law to electronically file (e-file) certain covered returns.
There are exceptions to this requirement, and Form 8948 is used by specified tax return preparers to identify returns that meet allowable exceptions.
A filled-in Form 8948 example: a paper return the taxpayer chose
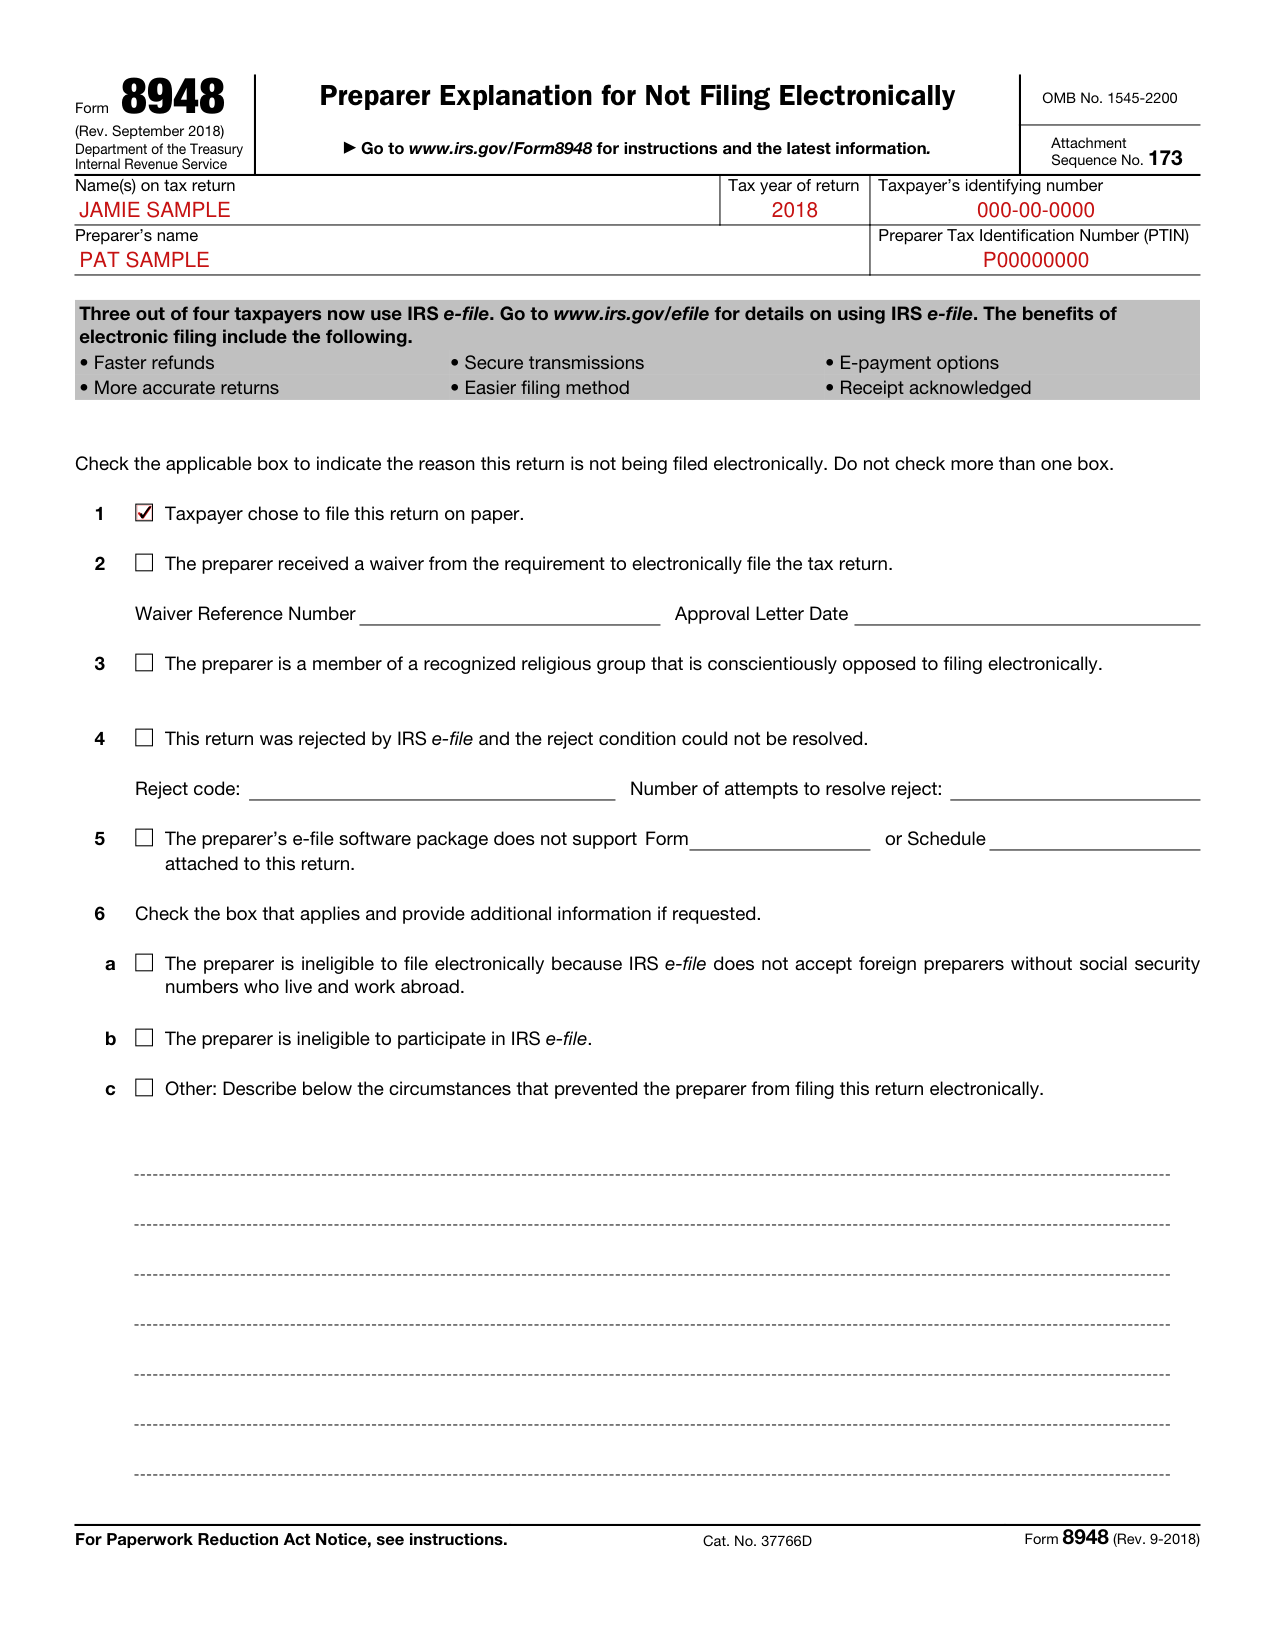
How to fill out Form 8948, box by box
Name(s) on tax return, tax year of return and taxpayer's identifying number

Enter the taxpayer's name(s), the tax year, and identifying number (SSN or EIN) that appear on the tax return with which Form 8948 will be filed.
The tax year of the tax return associated with Form 8948 must be entered.
If the return is an individual tax return using the Married Filing Jointly filing status, enter the first SSN listed on the tax return.
Preparer's name and Preparer Tax Identification Number (PTIN)

Enter the preparer's name and PTIN. The name and PTIN of the preparer also must be entered on the form.
Enter all the numbers of the PTIN.
Line 1: the taxpayer chose to file on paper

Check the applicable box to indicate the reason this return is not being filed electronically. Do not check more than one box.
Line 1. Check this box if the taxpayer has chosen to file on paper and the return is prepared by the preparer, but will be submitted by mail by the taxpayer.
Form 8948 does not meet the criteria of a taxpayer choice statement.
Do not attach the taxpayer choice statement to the tax return or otherwise send it to the IRS.
Line 2: the preparer received a waiver

Line 2. Check this box if the preparer applied for and received an approved undue hardship waiver for the calendar year in which the return is being filed.
Enter the waiver reference number and date of the approval letter.
Do not submit the approval letter with this form.
Specified tax return preparers who submitted Form 8944, Preparer e-file Hardship Waiver Request, and received an approval letter, should file Form 8948 with the tax return that is being sent to the IRS.
Line 3: a recognized religious group
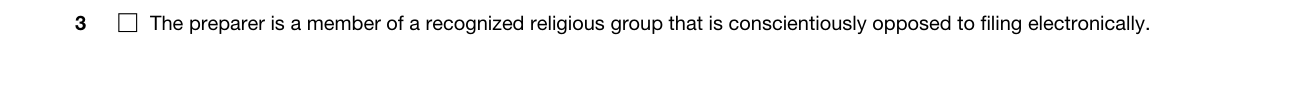
Line 3. Check this box if the preparer is a member of a recognized religious group that is conscientiously opposed to its members using electronic technology, including the filing of income tax returns electronically, and the group has existed continuously since December 31, 1950.
Line 4: the return was rejected by IRS e-file

Line 4. Check this box if the preparer attempted to e-file this return but was unable to do so because the return was rejected and the reject condition could not be resolved.
Enter the reject code and the number of attempts made to resolve the reject.
Line 5: the e-file software does not support a form or schedule

Line 5. Check this box if the preparer attempted to e-file this return but the software package used to e-file did not support one or more of the forms or schedules that are a part of this return.
Enter the form and/or schedule numbers the software did not support.
Do not check this box if the reason you could not e-file this return is that the IRS does not electronically accept a form or schedule attached to this return.
Line 6: the preparer is ineligible or has other difficulties
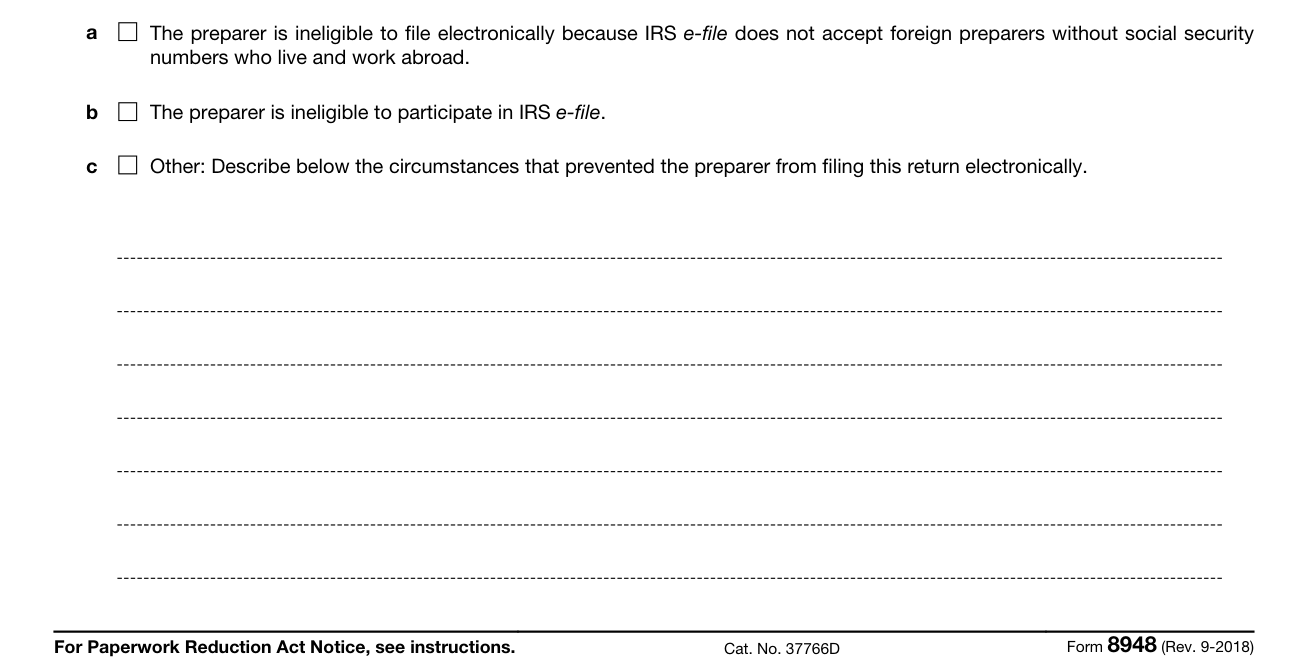
Line 6. Check the box that applies and provide additional information if requested. Line 6a. Check this box if the preparer is a foreign person without a social security number who cannot enroll in IRS e-file and the preparer is not a member of a firm that is eligible to e-file.
To qualify to check this box, the preparer must have applied for a PTIN and submitted Form 8946, PTIN Supplemental Application For Foreign Persons Without a Social Security Number.
Do not attach the PTIN application or Form 8946 to the return.
Line 6b. Check this box if the preparer is ineligible to e-file due to an IRS sanction.
To qualify, the preparer must have received a letter from the IRS enforcing the sanction and the sanction must be in effect for some or all of the calendar year in which the return is being filed.
Do not attach the sanction letter to the return.
The preparer may check this box until such time as the sanction period ends or the IRS accepts the preparer into the IRS e-file program, whichever occurs first.
If the preparer has filed a pending application for the IRS e-file program at the same time the sanction period ends, the preparer may continue to check this box until the IRS makes a decision about the preparer's application.
Line 6c. Check the box if the preparer is unable to e-file because of other verifiable and documented technological difficulties experienced by the preparer that are not described elsewhere on this form.
Describe the circumstances in the space provided.
If your situation is different
The return cannot be e-filed
Some covered returns are not currently capable of being accepted electronically by the IRS.
In certain instances, the IRS has instructed taxpayers not to file some covered returns electronically.
Additionally, certain covered returns cannot be e-filed if they have attached forms, schedules, or documents that the IRS does not accept electronically and these forms, schedules, or documents cannot be sent to the IRS separately using Form 8453 or Form 8453-F as a transmittal document.
In any of these situations, the preparer does not need to complete and submit Form 8948.
However, if the forms, schedules, or documents can be sent to the IRS separately using Form 8453 or Form 8453-F as a transmittal document, the rest of the return must be e-filed.
Forms 1040A and 1040EZ
Forms 1040A and/or 1040EZ are not being revised for tax year 2018. Previous filers for these forms will file Form 1040 for 2018; all references for these forms have been revised accordingly.
Common questions about Form 8948
Where do I file it?
File Form 8948 with the tax return that is filed on paper.
Sources
[1] Form 8948 (Rev. September 2018), Preparer Explanation for Not Filing Electronically, Department of the Treasury Internal Revenue Service (the Official source link on this page).