
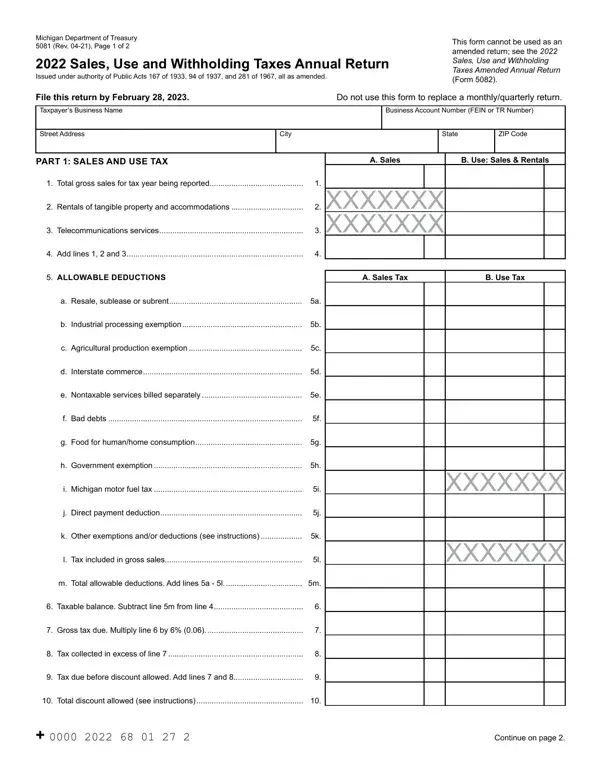
Form 5081 at a glance
What it is: Form 5081 is the 2025 Sales, Use and Withholding Taxes Annual Return of the Michigan Department of Treasury, a return for sales tax, use tax and/or withholding tax.
Who signs: Signature of Taxpayer or Official Representative must be Owner, Officer, Member, Manager, or Partner.
Where and when to file: File this return by February 28, 2026; do not use this form to replace a monthly/quarterly return. File and pay this return for free on Michigan Treasury Online at mto.treasury.michigan.gov. Alternatively, make check payable to “State of Michigan.” Write the account number, “SUW Annual” and tax year on the check. Send the return and payment due to: Michigan Department of Treasury, P.O. Box 30401, Lansing, MI 48909-7901.
A filled-in Form 5081 example: a hardware seller files the annual return
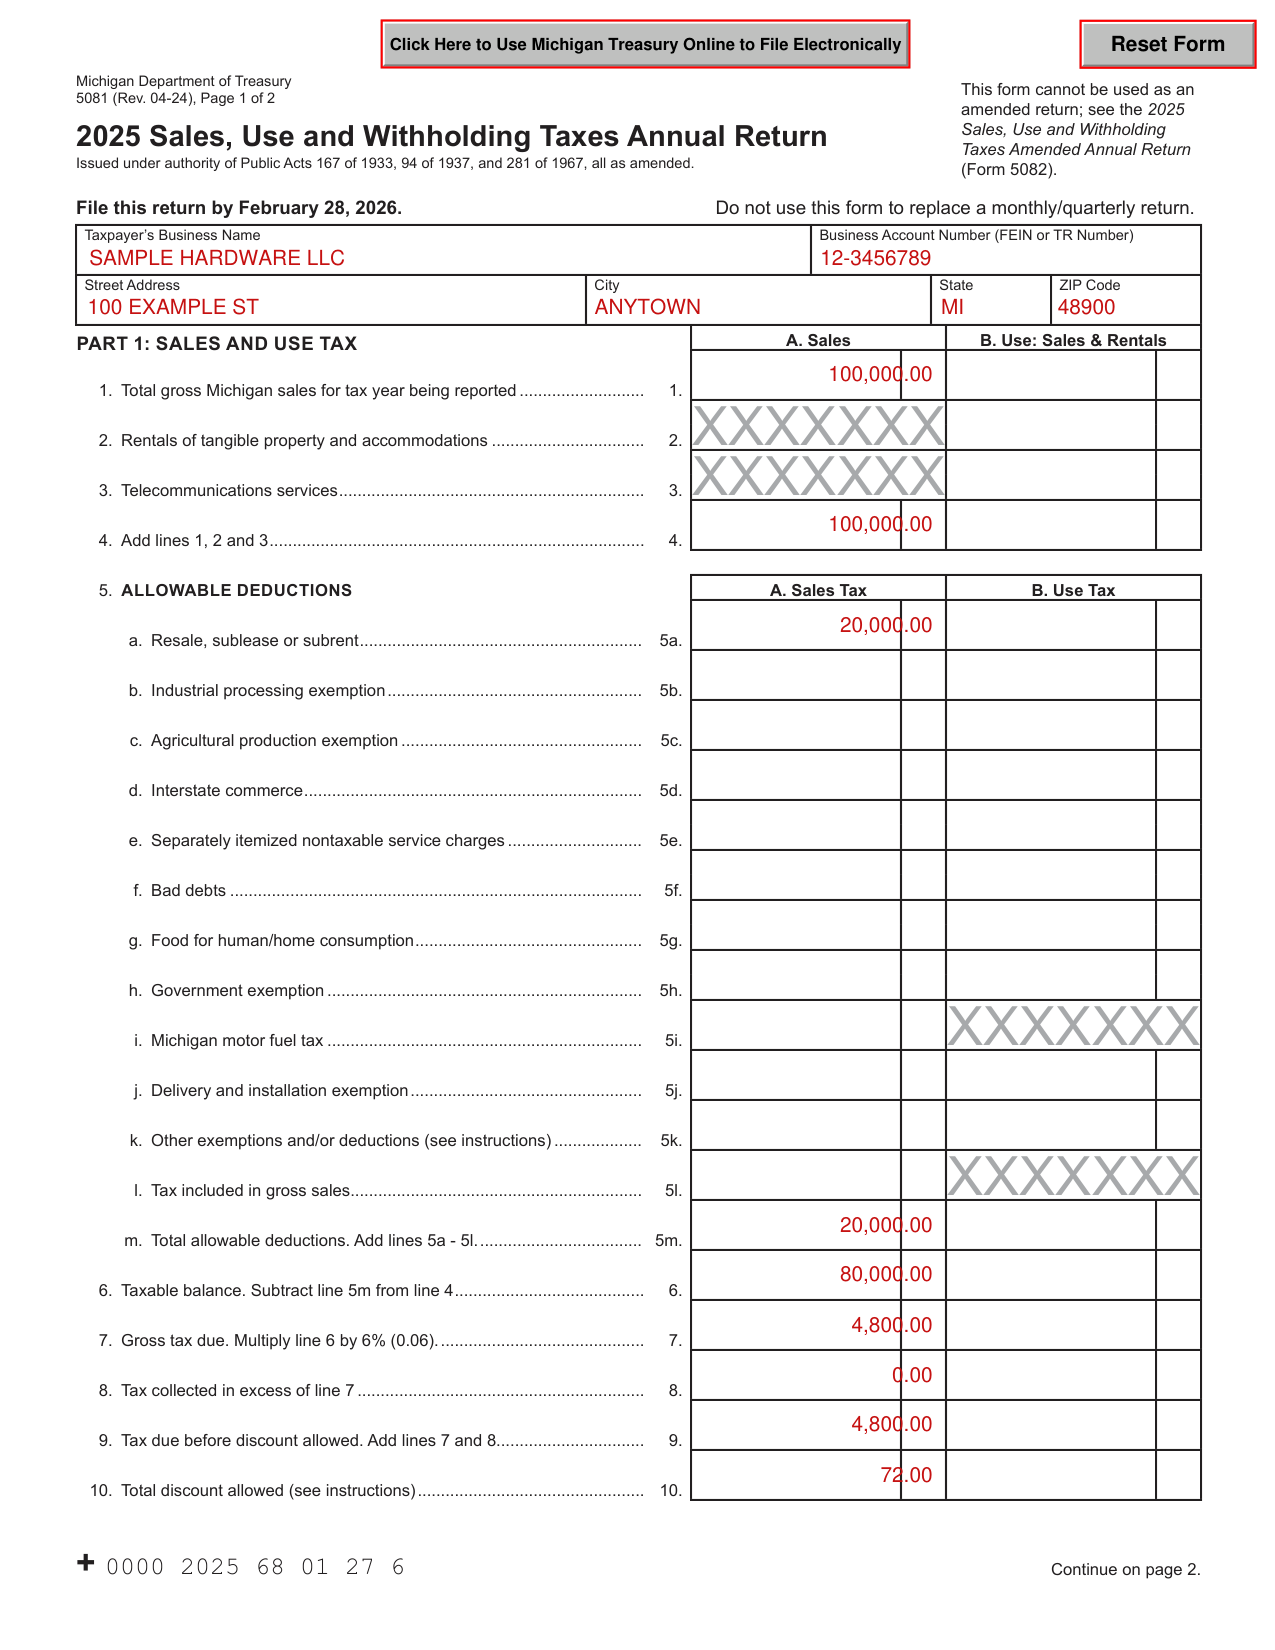
How to fill out Form 5081, box by box
Taxpayer's Business Name, Business Account Number and Street Address
Enter the Taxpayer's Business Name and the Business Account Number (FEIN or TR Number).
Enter the Street Address, City, State and ZIP Code.
NOTE: The address field on this form is required to be completed but will not be used to replace an existing valid address for the purpose of correspondence or refunds.
Update address and other registration information using MTO or mail a completed Notice of Change or Discontinuance (Form 163).
Part 1: Sales and Use Tax, lines 1 to 4
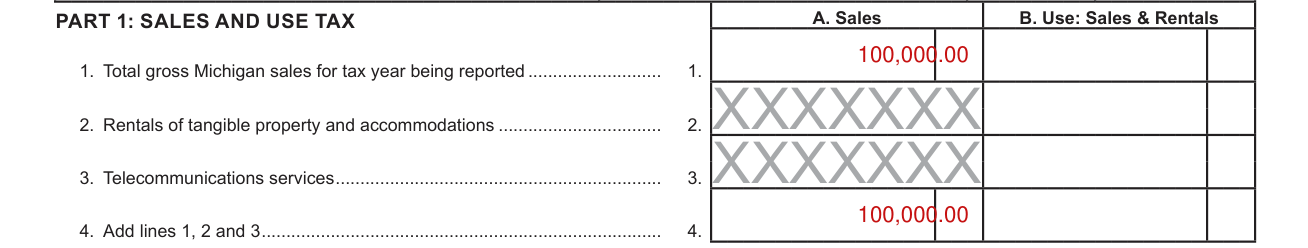
Common mistake: Only enter figures for taxes the business is registered and/or liable for.
Line 1A: SALES TAX - Total Gross Sales for the Tax Year: This line should be used by sellers with nexus to report sales of tangible personal property where ownership transfers in Michigan. This includes sellers with nexus through physical presence or economic presence (remote sales).
Line 1A: Sellers with nexus enter total sales, including cash and installment transactions, of tangible personal property.
Line 1A: Sellers with nexus do not report nontaxable services that do not involve the sale or lease of tangible personal property, or sales made through a marketplace facilitator, if you are a marketplace seller.
Line 4: Add lines 1, 2 and 3.
Sellers that separately state the tax (for example, on a receipt) and track their sales and tax separately in their books and records should report sales in this section without tax included and should leave line 5l blank.
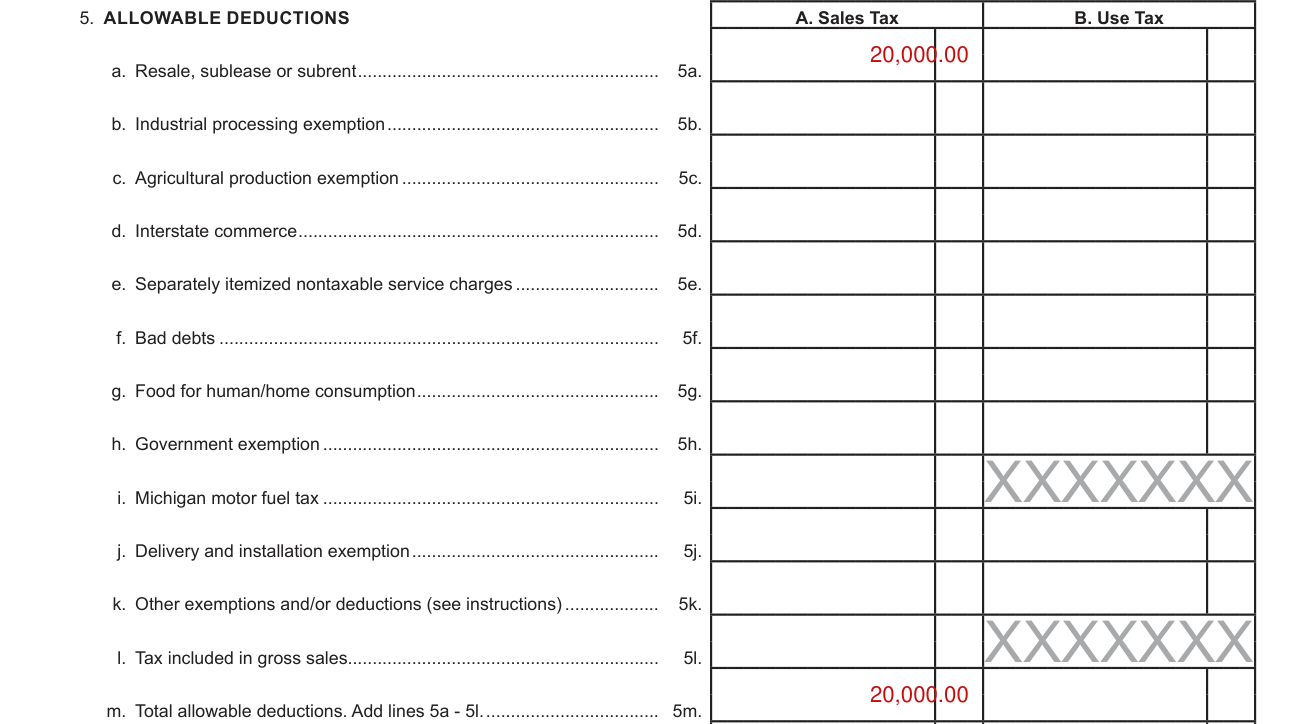
Line 5: Allowable Deductions
The TIGS method means that the taxpayer reports its gross sales on lines 1 through 4 with the tax included and uses line 5l to calculate and deduct the tax that was included.
Common mistake: A seller that did not collect the tax at the point of sale from its customers is not permitted to use the TIGS method. For line 5l, Tax Included in Gross Sales, subtract lines 5a through 5k from line 4, then divide the difference by 17.6667, and enter the result on line 5l.
Line 5a-5l: Use lines 5a - 5l to deduct from gross sales the nontaxable sales included in line 4.
Deductions taken for tax exempt sales must be substantiated in business records.
A completed copy of Michigan Sales and Use Tax Certificate of Exemption (Form 3372) or the same information in another format must be obtained from the purchaser.
Line 5a: Resale, Sublease or Subrent. Enter resale, sublease or subrent exemption claims.
m. Total allowable deductions. Add lines 5a - 5l.
Lines 6 to 10: Taxable balance, tax due and discount
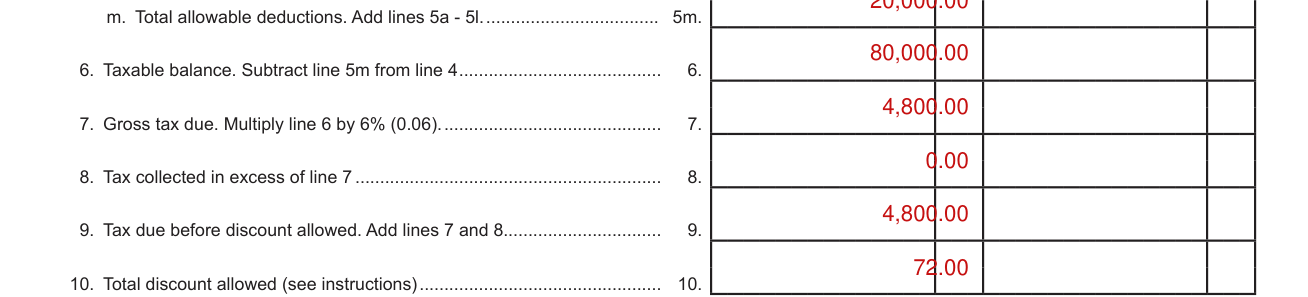
6. Taxable balance. Subtract line 5m from line 4.
7. Gross tax due. Multiply line 6 by 6% (0.06).
8. Tax collected in excess of line 7. This line is used to report differences due to the rounding of numerous transactions.
9. Tax due before discount allowed. Add lines 7 and 8.
Line 10: Total Discount Allowed for Timely Payments. Annual filers: Enter $72 if the tax due on line 9 is $108 or more (checked November 12, 2026). If tax due is less than $108, calculate the discount by multiplying line 9 by 2/3 (0.6667) (checked November 12, 2026). Accelerated/Monthly/Quarterly filers: Enter total discounts allowed for the year.
Lines 11 and 12: Total tax due and payments
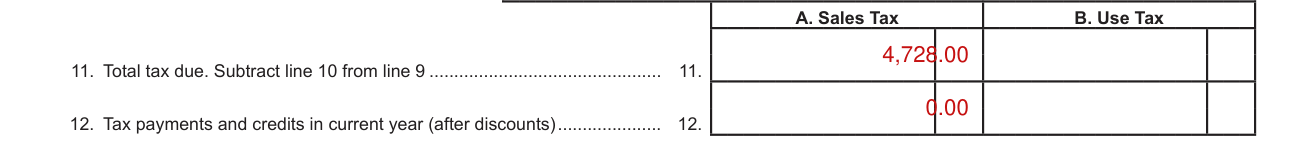
11. Total tax due. Subtract line 10 from line 9.
12. Tax payments and credits in current year (after discounts).
Part 2: Use Tax on Items Purchased for Business or Personal Use
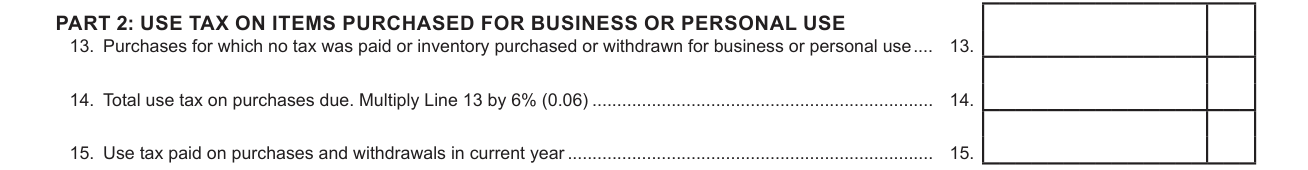
Part 2, Line 13: Unless a specific exemption applies enter purchases for which no sales or use tax was paid, including property withdrawn for business or personal use.
14. Total use tax on purchases due. Multiply Line 13 by 6% (0.06).
15. Use tax paid on purchases and withdrawals in current year.
Part 3: Withholding Tax
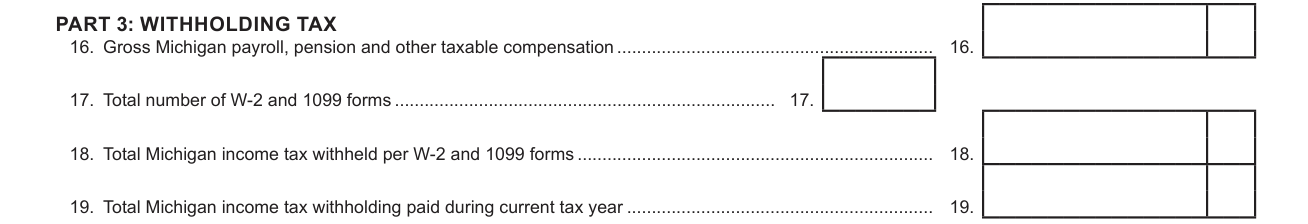
16. Gross Michigan payroll, pension and other taxable compensation.
Part 3, Line 17: Enter the number of your W-2 and 1099 statements.
18. Total Michigan income tax withheld per W-2 and 1099 forms.
19. Total Michigan income tax withholding paid during current tax year.
Part 4: Summary
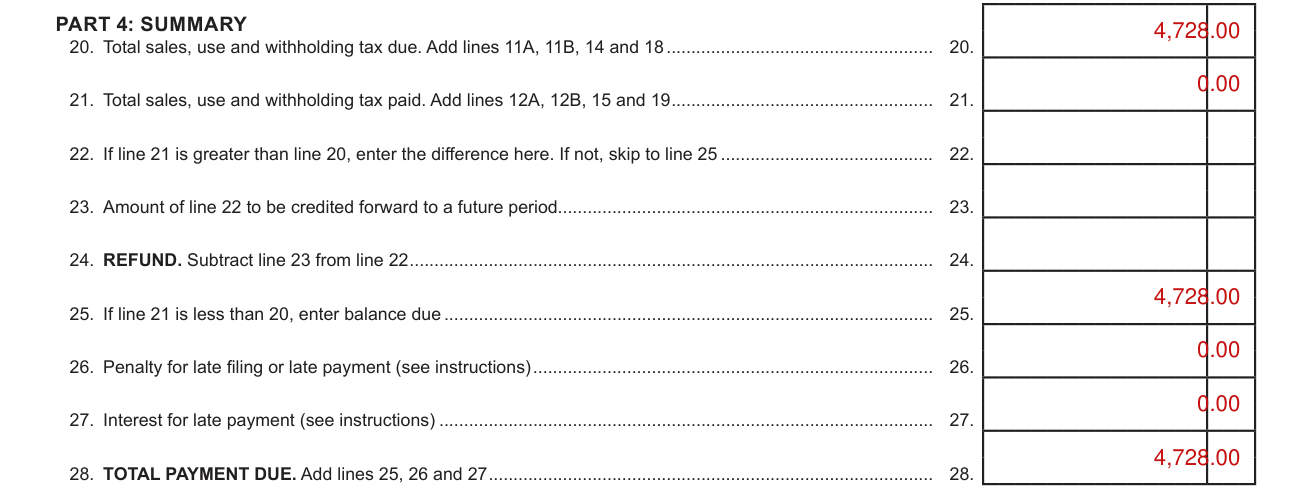
20. Total sales, use and withholding tax due. Add lines 11A, 11B, 14 and 18.
21. Total sales, use and withholding tax paid. Add lines 12A, 12B, 15 and 19.
22. If line 21 is greater than line 20, enter the difference here. If not, skip to line 25.
23. Amount of line 22 to be credited forward to a future period.
24. REFUND. Subtract line 23 from line 22. Line 24: Enter the amount of overpayment from line 22 to be refunded. Refunds will not be made in amounts of less than $1 (checked November 12, 2026).
Line 25: If line 21 (tax paid) is less than line 20 (tax due), enter the additional tax due. Pay any amount greater than or equal to $1 (checked November 12, 2026).
26. Penalty for late filing or late payment (see instructions).
27. Interest for late payment (see instructions).
How to Compute Penalty and Interest If the return is filed after February 28 and no tax is due, compute penalty at $10 per day up to a maximum of $400 (checked November 12, 2026).
If the return is filed with additional tax due, include penalty and interest with the payment.
Penalty is 5% of the tax due and increases by an additional 5% per month or fraction thereof, after the second month, to a maximum of 25%.
28. TOTAL PAYMENT DUE. Add lines 25, 26 and 27.
Do not pay if the amount due is less than $1 (checked November 12, 2026).
Part 5: Signature, Taxpayer Certification

Taxpayer Certification: “I declare under penalty of perjury that the information in this return and attachments is true and complete to the best of my knowledge.”
PART 5: SIGNATURE REMINDER: Taxpayers must sign and date returns.
Enter the Print Taxpayer or Official Representative's Name and the Date.
Enter the Title and Telephone Number.
Part 5: Signature, Preparer Certification
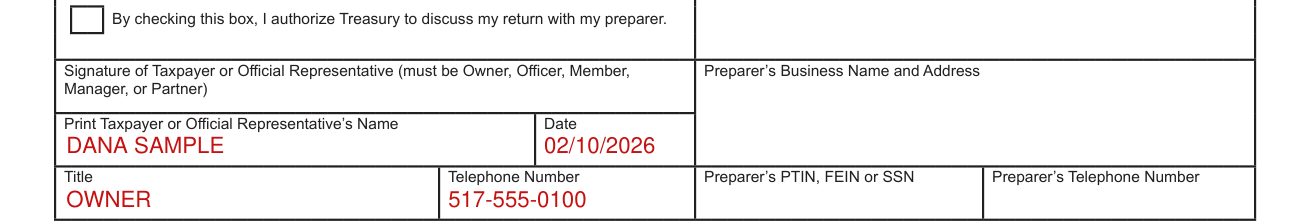
Preparer Certification: “I declare under penalty of perjury that this return is based on all information of which I have any knowledge.”
Preparer's Signature. Preparer's Business Name and Address.
Enter the Preparer's PTIN, FEIN or SSN and the Preparer's Telephone Number.
By checking this box, I authorize Treasury to discuss my return with my preparer.
Preparers must provide a Preparer Taxpayer Identification Number (PTIN), Social Security Number (SSN) or Preparer Firm ID (FEIN), as well as business name, business address and phone number.
More rules for Form 5081
This form cannot be used as an amended return; see the 2025 Sales, Use and Withholding Taxes Amended Annual Return (Form 5082).
If the taxpayer inserts a zero on or leaves blank any line reporting sales tax, use tax or withholding tax, the taxpayer is certifying that no tax is owed for that tax type.
If it is determined that tax is owed the taxpayer will be liable for the deficiency as well as penalty and interest.
If your situation is different
You may qualify for the Annual EZ form
Most taxpayers will have the option to file the Annual EZ form, reducing the amount of fields needed to complete.
Visit MTO to see if you qualify.
You have 250 or more employees
Taxpayers with 250 or more employees must file their withholding return electronically.
Do not include wage statements with your mailed annual return.
Common questions about Form 5081
What is a 5081 tax form?
Form 5081 is the 2025 Sales, Use and Withholding Taxes Annual Return of the Michigan Department of Treasury, a return for sales tax, use tax and/or withholding tax. Page 3 of the 2025 instructions: Form 5081 is available for submission electronically using Michigan Treasury Online (MTO) at mto.treasury.michigan.gov or by using approved tax preparation software.
Who signs it?
Signature of Taxpayer or Official Representative must be Owner, Officer, Member, Manager, or Partner.
Is there a deadline?
File this return by February 28, 2026; do not use this form to replace a monthly/quarterly return.
Where do I file it?
File and pay this return for free on Michigan Treasury Online at mto.treasury.michigan.gov.
Sources
[1] Form 5081 (Rev. 04-24), 2025 Sales, Use and Withholding Taxes Annual Return, Michigan Department of Treasury (the Official source link on this page).