
Form MI W-4P at a glance
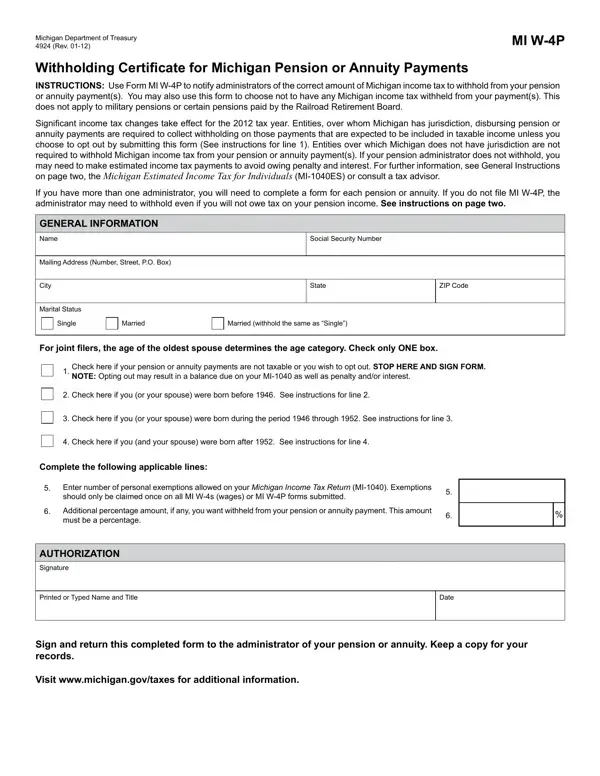
What it is: Form MI W-4P is the Withholding Certificate for Michigan Pension or Annuity Payments from the Michigan Department of Treasury.
Where and when to file: Sign and return this completed form to the administrator of your pension or annuity. Keep a copy for your records. Complete Form MI W-4P and give it to the administrator of your retirement benefits as soon as possible.
Use Form MI W-4P to provide your information to pension and retirement benefits administrators to determine the amount of Michigan income tax to withhold from your pension, retirement benefit or annuity payments. You may also use this form to choose not to have any Michigan income tax withheld from your payments. Military pensions and pensions paid by the Railroad Retirement Board are not subject to tax or withholding.
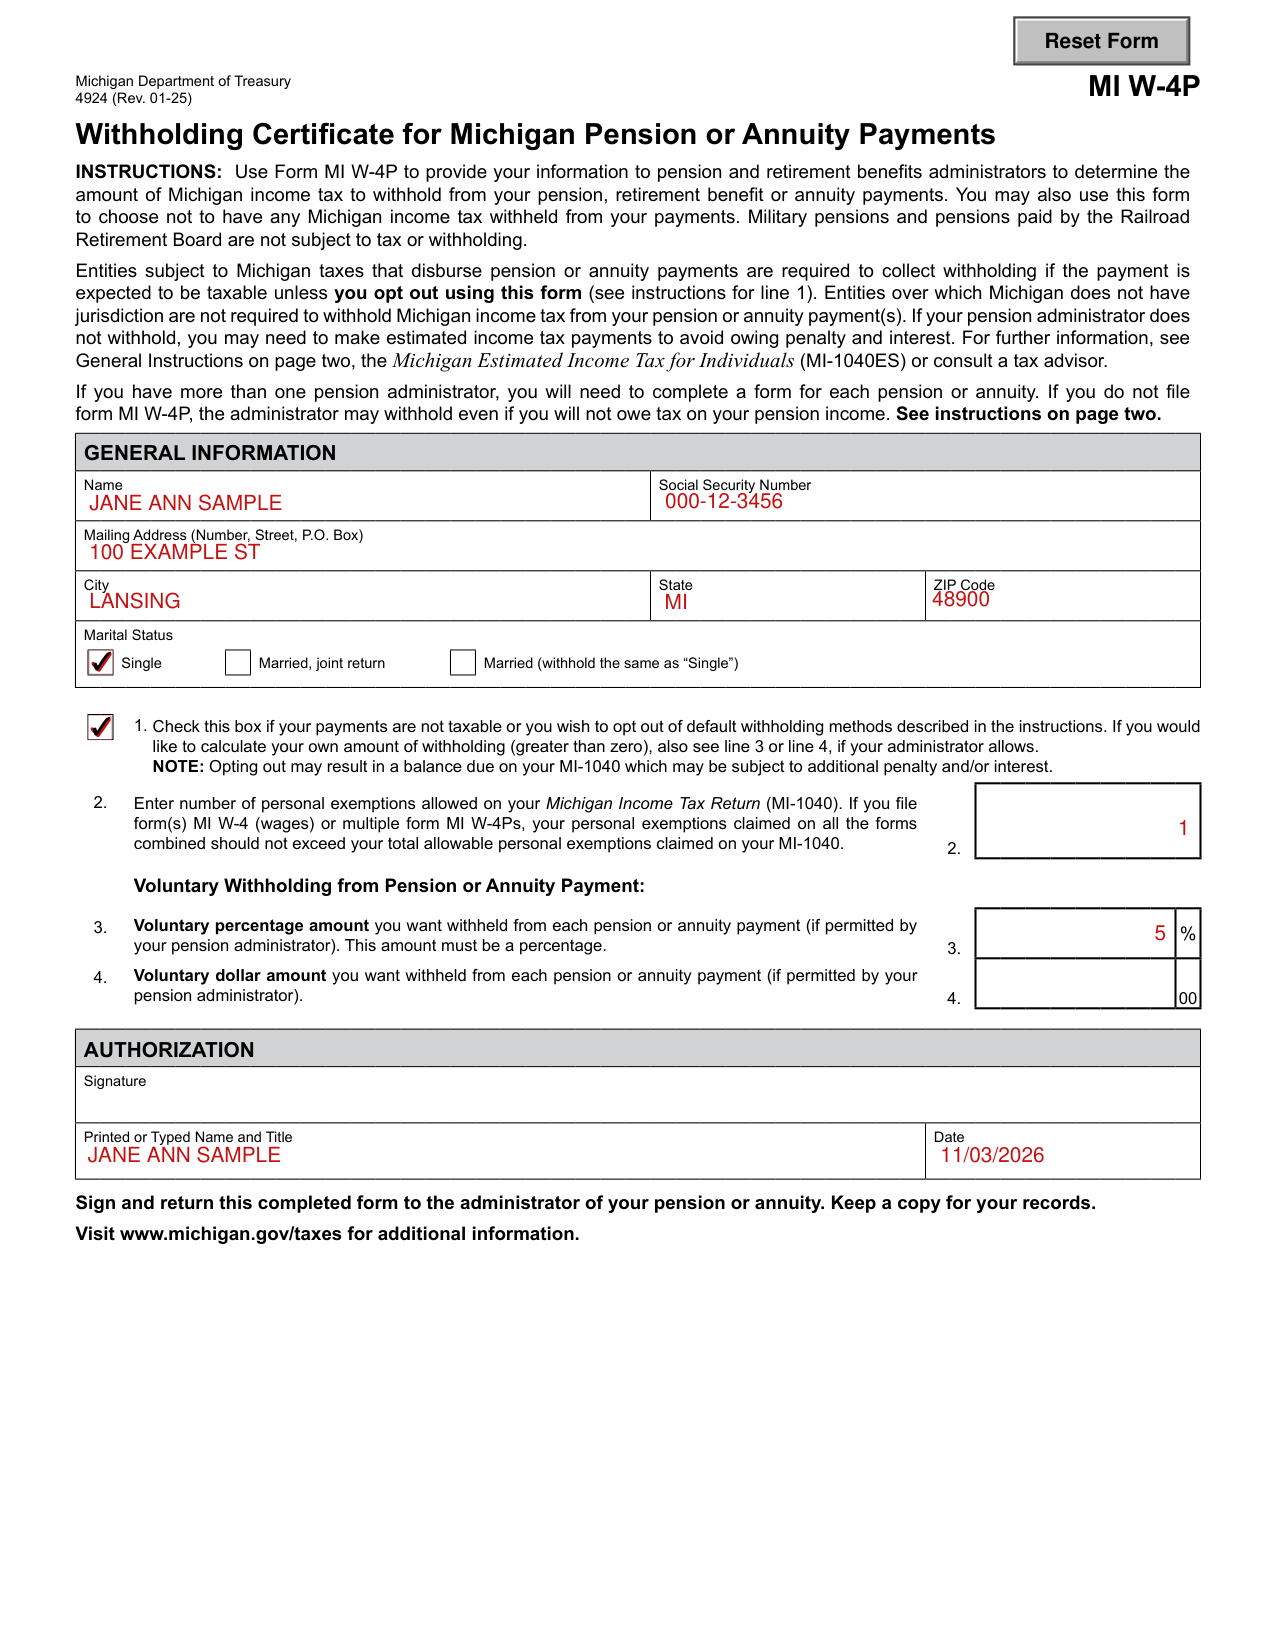
A filled-in Form MI W-4P example: a single retiree sets a withholding percentage
How to fill out Form MI W-4P, box by box
Name, Social Security Number and Mailing Address
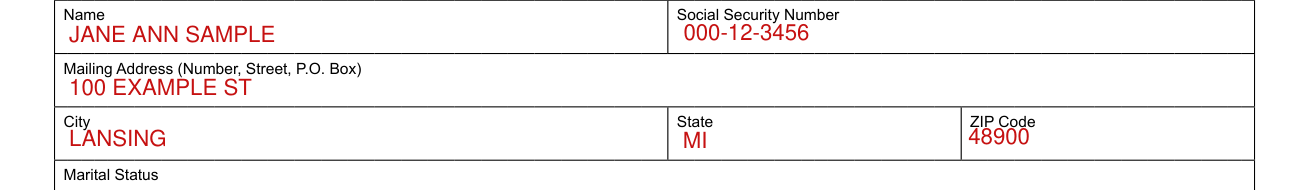
Enter your Name and Social Security Number.
Enter your Mailing Address (Number, Street, P.O. Box), City, State and ZIP Code.
Marital Status

Under Marital Status, check Single, Married, joint return or Married (withhold the same as “Single”).
Only check the “Married, joint return” box if your spouse does not also receive qualifying retirement or pension benefits or if your spouse opts not to consider any subtraction while computing their retirement withholding.
Checking this box indicates to your administrator that they may allow the larger, joint limitations in computing your withholding and unless used properly, could result in underpayment on your annual return.
Line 1: opt out of default withholding methods

Check this box if your payments are not taxable or you wish to opt out of default withholding methods described in the instructions. If you would like to calculate your own amount of withholding (greater than zero), also see line 3 or line 4, if your administrator allows. NOTE: Opting out may result in a balance due on your MI-1040 which may be subject to additional penalty and/or interest.
You may opt out of withholding tax from your retirement benefits if you believe you will not have a balance due on your MI-1040.
If you (and your spouse) opt to have no Michigan tax withheld from your retirement benefits by checking the box on line 1, it may result in a balance due on your MI-1040 and penalty and/or interest may apply.
If you prefer to opt out of the default rules and calculate your own taxable benefits and withholding, check the box on line 1 and use line 3 or line 4, if allowed by your administrator, to determine the percent or amount of tax you want the administrator to withhold.
Line 2: number of personal exemptions

On line 2, enter the number of personal exemptions you are claiming for withholding, allowed on your Michigan Income Tax Return (MI-1040).
If you file form(s) MI W-4 (wages) or multiple form MI W-4Ps, your personal exemptions claimed on all the forms combined should not exceed your total allowable personal exemptions claimed on your MI-1040.
Line 3: voluntary percentage amount withheld

Enter the voluntary percentage amount you want withheld from each pension or annuity payment (if permitted by your pension administrator). This amount must be a percentage.
On line 3, you may designate additional withholding if you expect to owe more than the amount withheld.
Check with your pension administrator to see if they permit additional withholding.
Line 4: voluntary dollar amount withheld

Enter the voluntary dollar amount you want withheld from each pension or annuity payment (if permitted by your pension administrator).
On line 4, if allowed by your pension administrator, you may enter an additional dollar amount to be withheld from each payment.
Failure to have sufficient tax withheld from your retirement benefits may result in a balance due on your MI-1040 and penalty and/or interest may apply.
Authorization
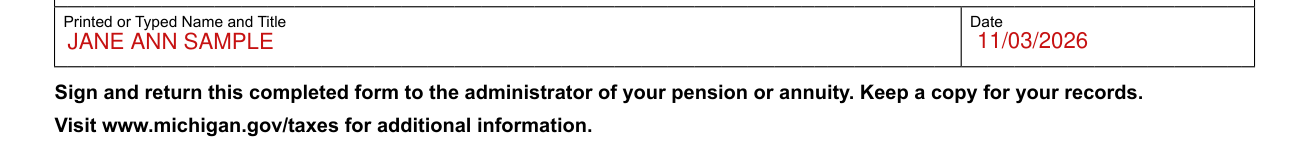
Under AUTHORIZATION, sign on the Signature line and enter your Printed or Typed Name and Title and the Date.
More rules for Form MI W-4P
Your pension administrator is only required to withhold on the benefits expected to be taxable. However, you may request more or less withholding by completing this form and submitting it to your pension administrator.
If you do not submit this form to your pension administrator, the amount of tax withheld from your retirement or pension benefits will be automatically calculated based on general rules.
If withholding is too low, an underpayment may result on your annual return (Form MI-1040). Underpayments may be subject to penalty and interest.
Taxpayers who choose not to have tax withheld from their retirement benefits may be required to make estimated tax payments.
Your tax situation may change from year to year; you may want to evaluate your withholding each year.
If your situation is different
You have more than one pension administrator
If you have more than one pension administrator, you will need to complete a form for each pension or annuity. If you do not file form MI W-4P, the administrator may withhold even if you will not owe tax on your pension income. See instructions on page two.
If you (and your spouse) receive multiple pension payments, your withholding on those payments may not cover your entire tax liability.
Married couples where each spouse receives retirement benefits may choose to have withholding calculated as if each was single on the MI W-4P and select one personal exemption in order to have sufficient withholding to cover the tax liability.
Taxpayers with multiple pensions may need to make quarterly estimated payments (MI-1040ES) or consult a tax advisor to ensure the proper amount is withheld or paid through estimated payments.
Your pension administrator is not under Michigan jurisdiction
Entities subject to Michigan taxes that disburse pension or annuity payments are required to collect withholding if the payment is expected to be taxable unless you opt out using this form (see instructions for line 1). Entities over which Michigan does not have jurisdiction are not required to withhold Michigan income tax from your pension or annuity payment(s). If your pension administrator does not withhold, you may need to make estimated income tax payments to avoid owing penalty and interest. For further information, see General Instructions on page two, the Michigan Estimated Income Tax for Individuals (MI-1040ES) or consult a tax advisor.
Only companies over which Michigan has taxing jurisdiction are required to withhold Michigan tax from your retirement benefits.
If your pension administrator does not fall under Michigan jurisdiction, you may request to have Michigan tax withheld, but the company is not required to do so.
If no taxes are withheld from your payments, it is likely you will be required to make estimated payments in place of the withholding.
Contact your pension and/or annuity administrator to verify whether tax will be withheld from your payments.
Common questions about Form MI W-4P
Is there a deadline?
Complete Form MI W-4P and give it to the administrator of your retirement benefits as soon as possible, and you can change the amount to be withheld by submitting an updated Form MI W-4P to your pension administrator at any time.
Where do I file it?
Sign and return this completed form to the administrator of your pension or annuity. Keep a copy for your records.
Is there a penalty?
There are penalties for not paying enough state income tax during the year, either through withholding or estimated tax payments.
Sources
[1] Form MI W-4P (Rev. 01-25), Michigan Department of Treasury (the Official source link on this page).