
Form SIPC-7 at a glance
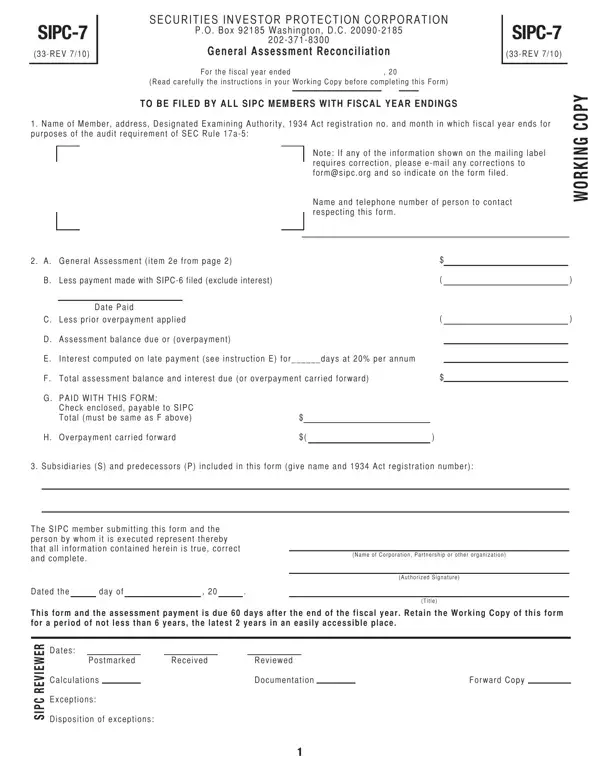
What it is: SIPC-7 is the general assessment reconciliation form of the Securities Investor Protection Corporation.
Who signs: The SIPC member submitting this form and the person by whom it is executed represent thereby that all information contained herein is true, correct and complete.
This form is to be filed by all members of the Securities Investor Protection Corporation whose fiscal years end in 2011 and annually thereafter.
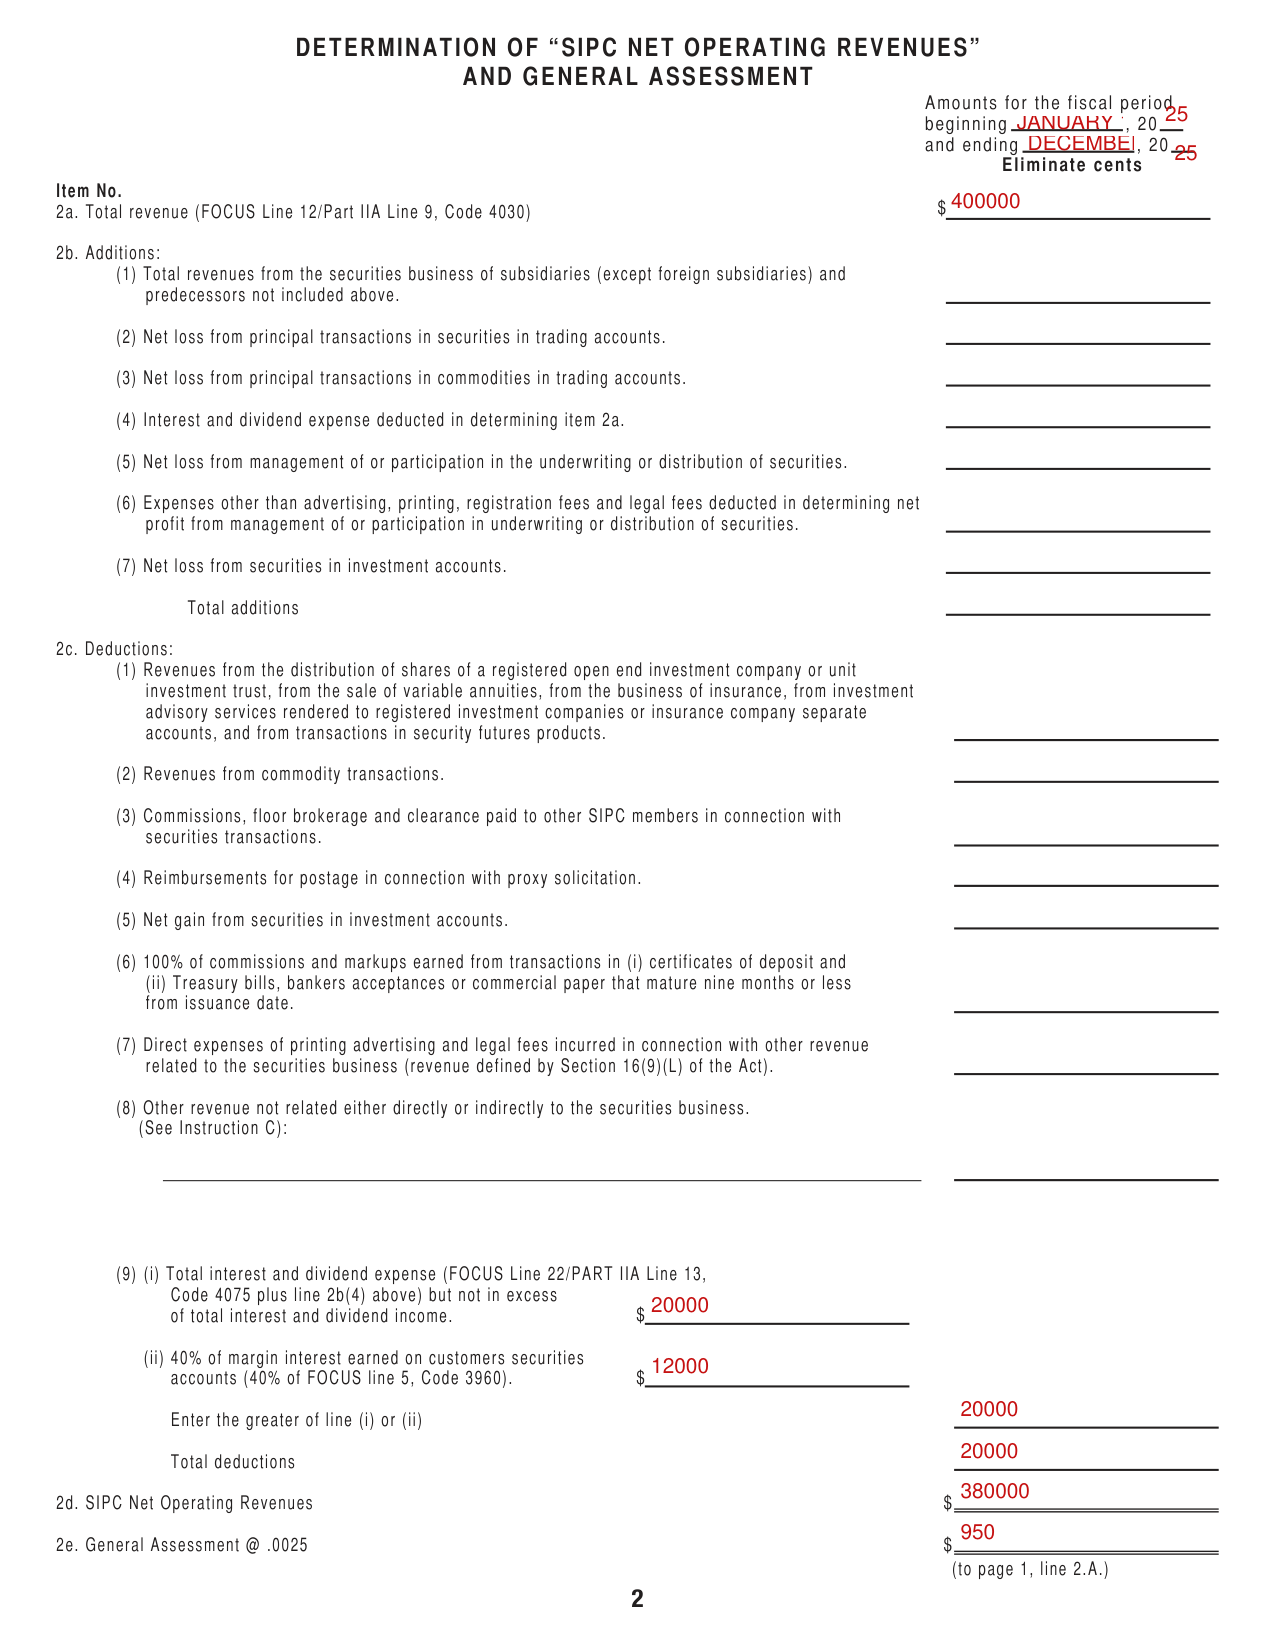
A filled-in Form SIPC-7 example: a small brokerage with one deduction
How to fill out Form SIPC-7, box by box
Fiscal year, member and contact
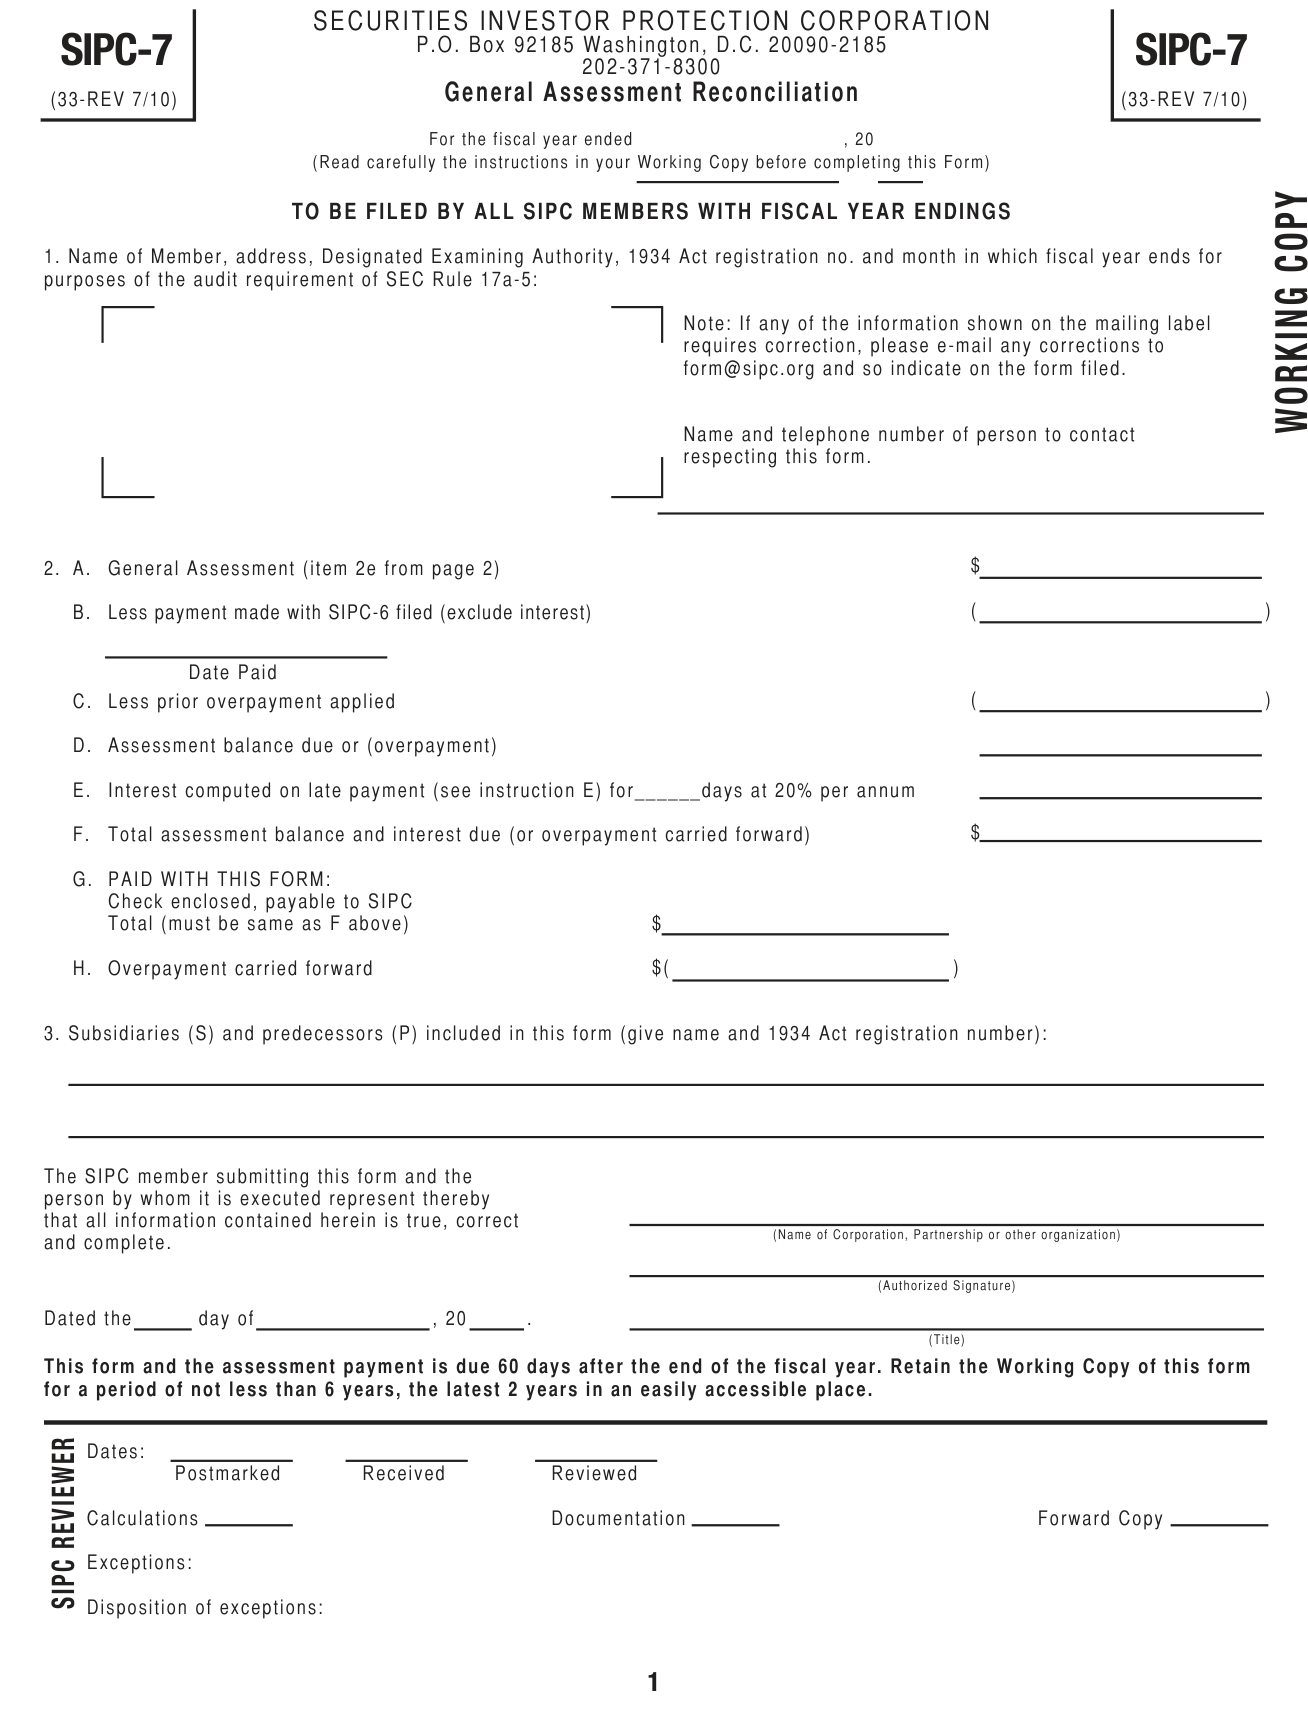
For the fiscal year ended: read carefully the instructions in your Working Copy before completing this Form.
Box 1: Name of Member, address, Designated Examining Authority, 1934 Act registration no. and month in which fiscal year ends for purposes of the audit requirement of SEC Rule 17a-5.
If any of the information shown on the mailing label requires correction, e-mail any corrections to form@sipc.org and so indicate on the form filed.
Name and telephone number of person to contact respecting this form.
Box 2: the assessment, payments and interest
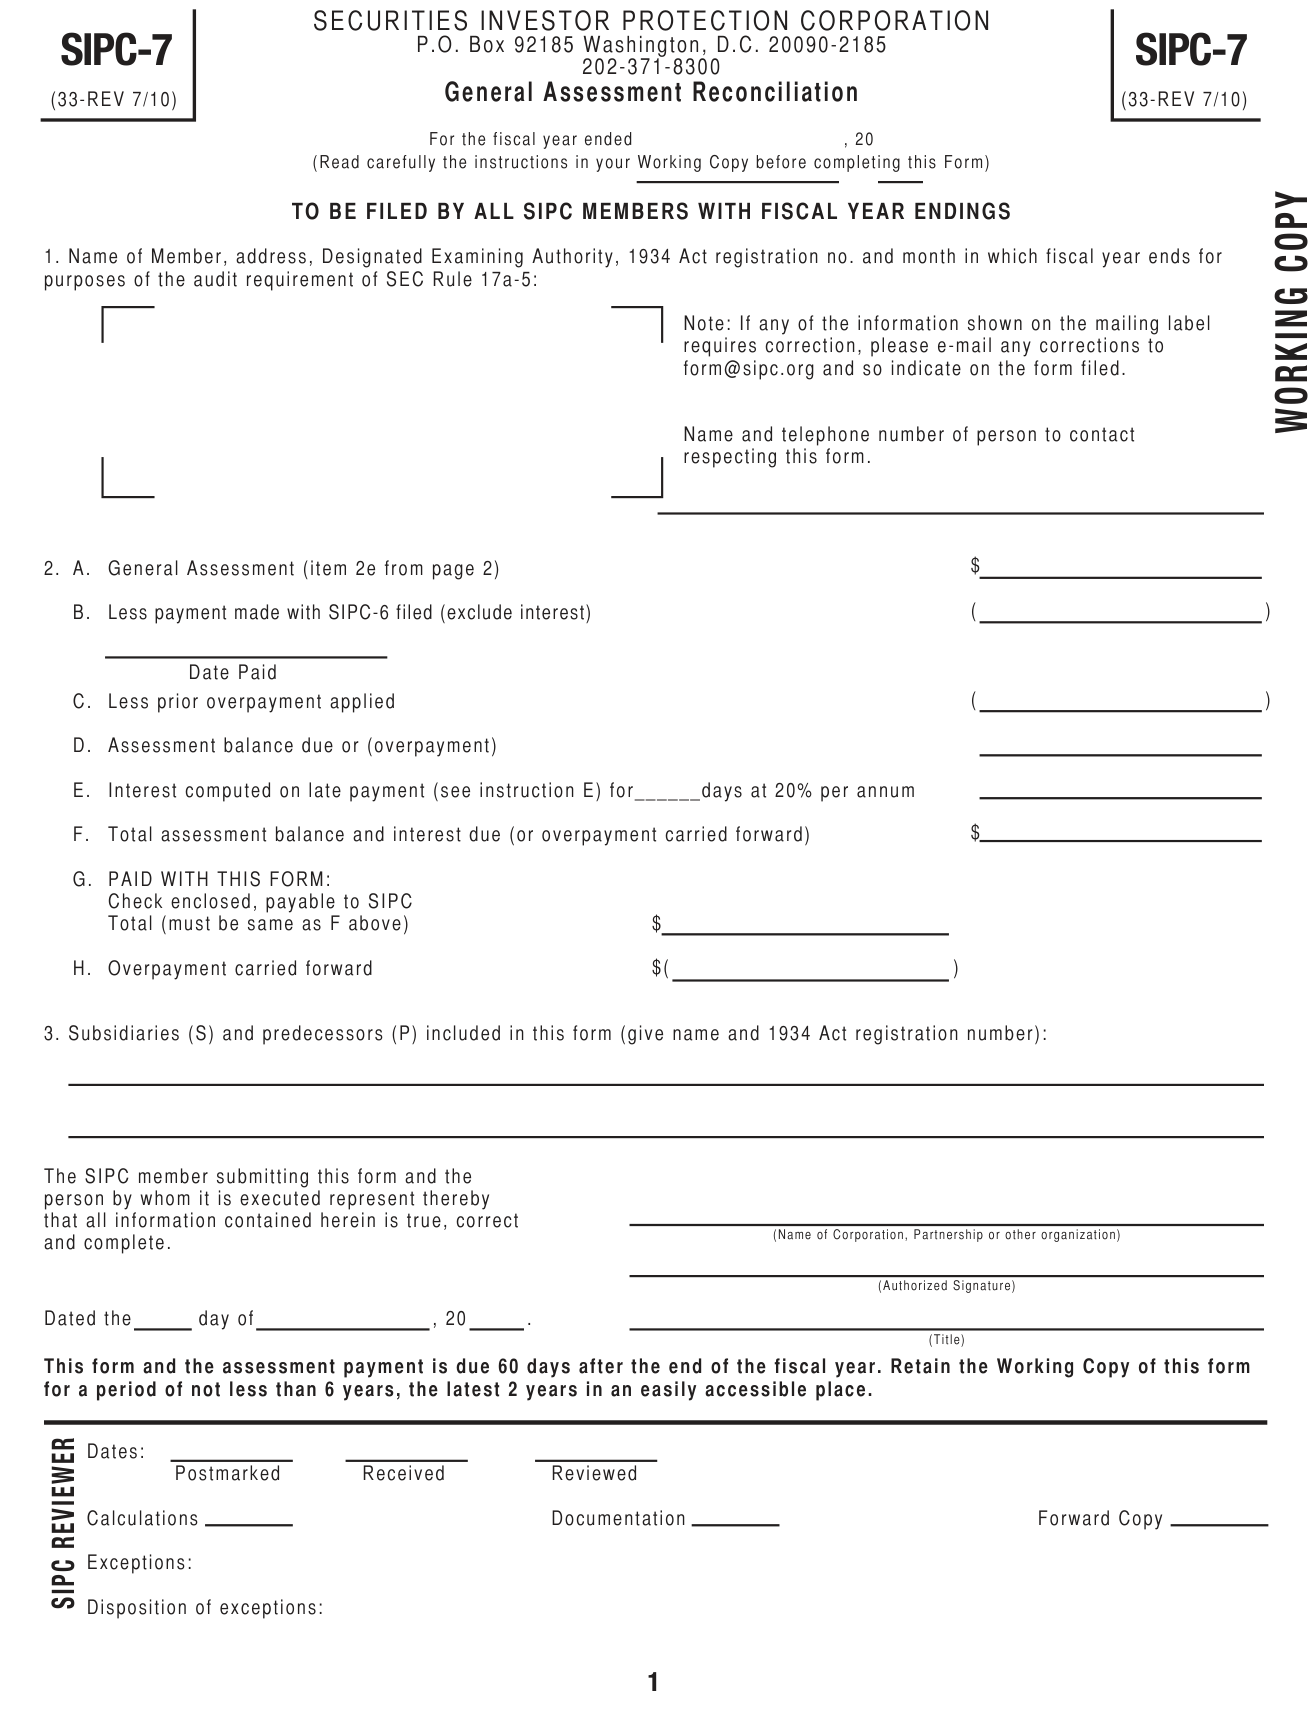
2. A. General Assessment (item 2e from page 2).
Enter the resulting amount in item 2e and on line 2A of page 1. Enter on line 2B the assessment due as reflected on the SIPC-6 previously filed (B. Less payment made with SIPC-6 filed (exclude interest)). Subtract line 2B and 2C from line 2A and enter the difference on line 2D.
This is the balance due for the period.
Interest computed on late payment (see instruction E) for days at 20% per annum.
If all or any part of assessment payable under Section 4 of the Act has not been postmarked within 15 days after the due date thereof, the member shall pay, in addition to the amount of the assessment, interest at the rate of 20% per annum on the unpaid portion of the assessment for each day it has been overdue.
Enter interest computed on late payment (if applicable) on line 2E. Enter the total due on line 2F and the payment of the amount due on line 2G. Enter overpayment carried forward (if any) on line 2H.
Paid with this form: Check enclosed, payable to SIPC Total (must be same as F).
Box 3: subsidiaries and predecessors
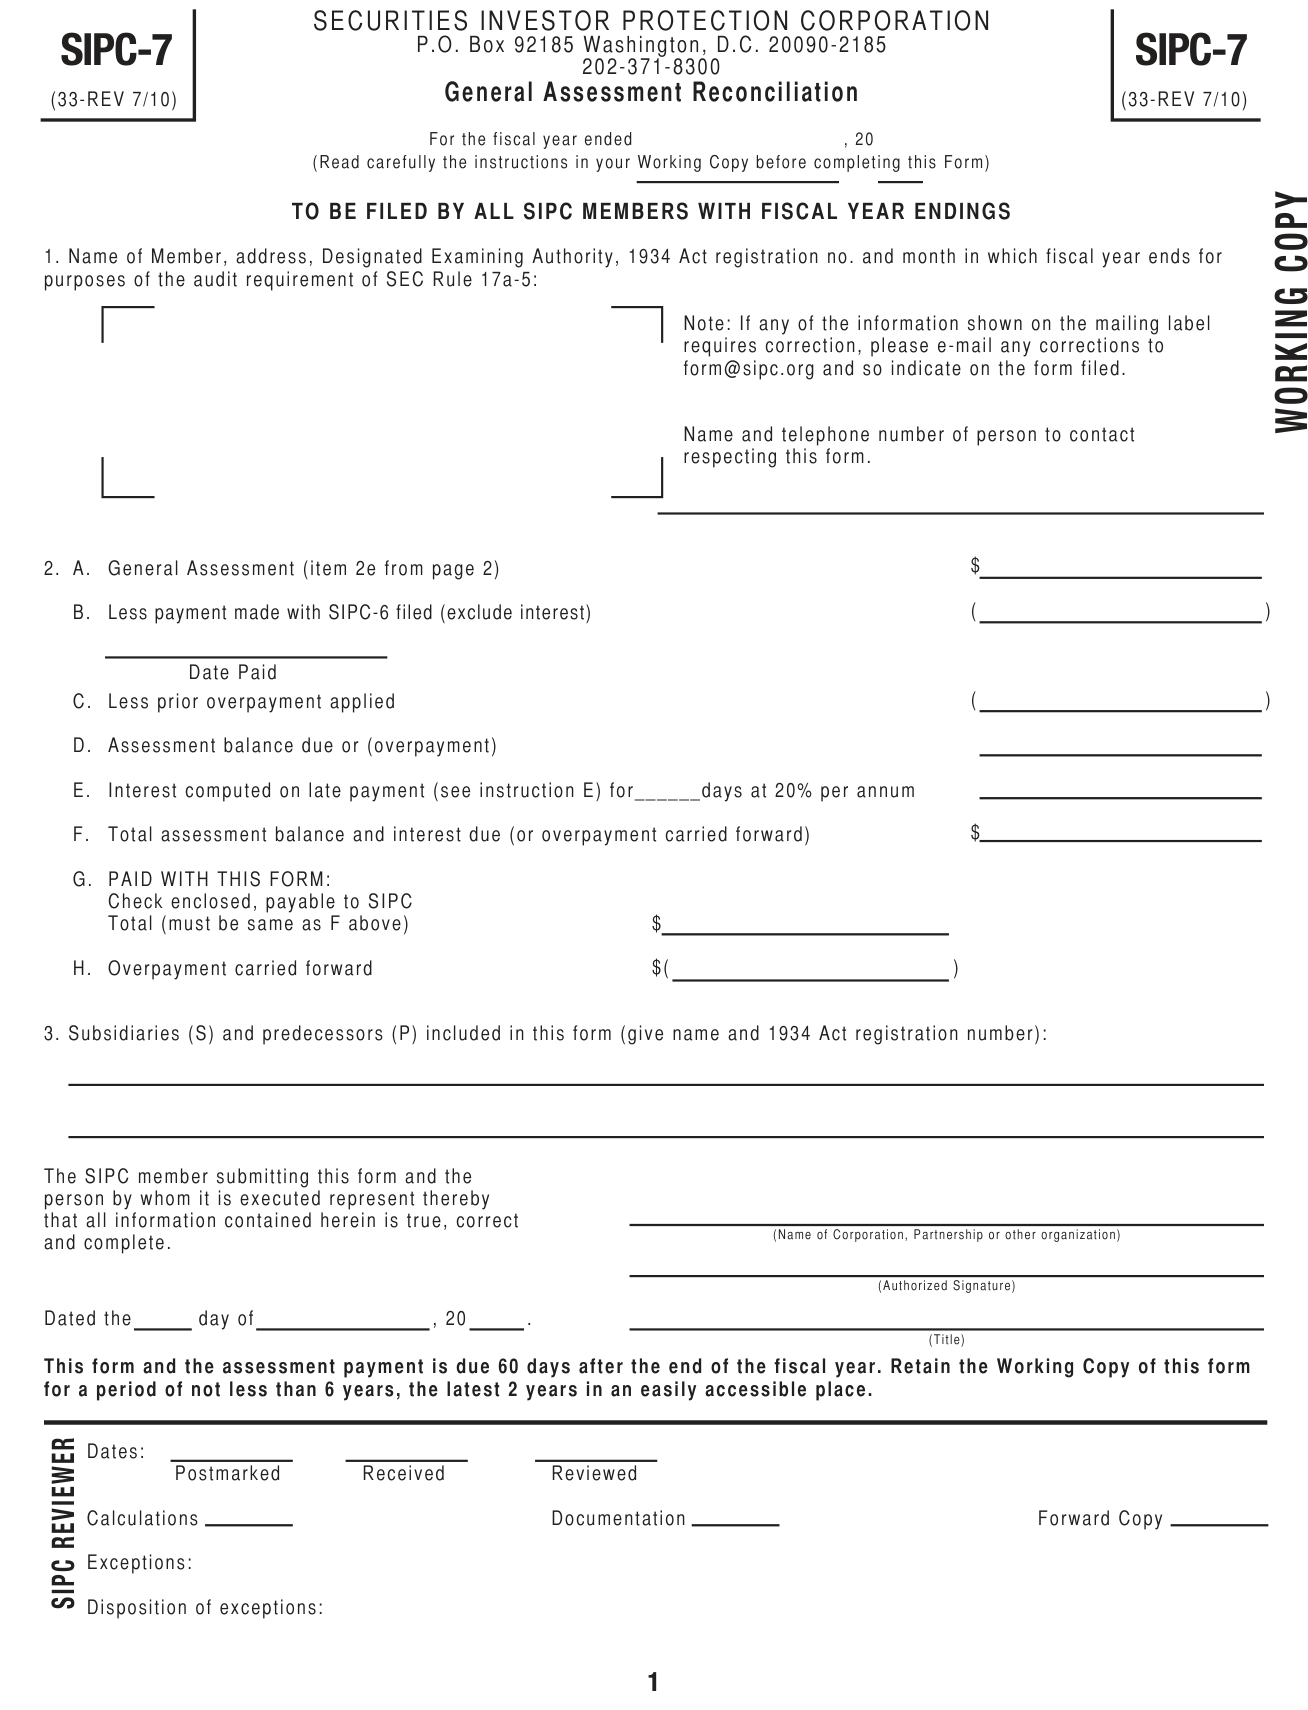
3. Subsidiaries (S) and predecessors (P) included in this form (give name and 1934 Act registration number).
If a subsidiary was required to file a Rule 17a-5 annual audited statement of income separately and is also a SIPC member, then such subsidiary must itself file SIPC-7, pay the assessment, and should not be consolidated in your SIPC-7.
SIPC Net Operating Revenues of a predecessor member which are not included in item 2a, were not reported separately and the SIPC assessments were not paid thereon by such predecessor, shall be included in item 2b(1).
Total revenue and the fiscal period
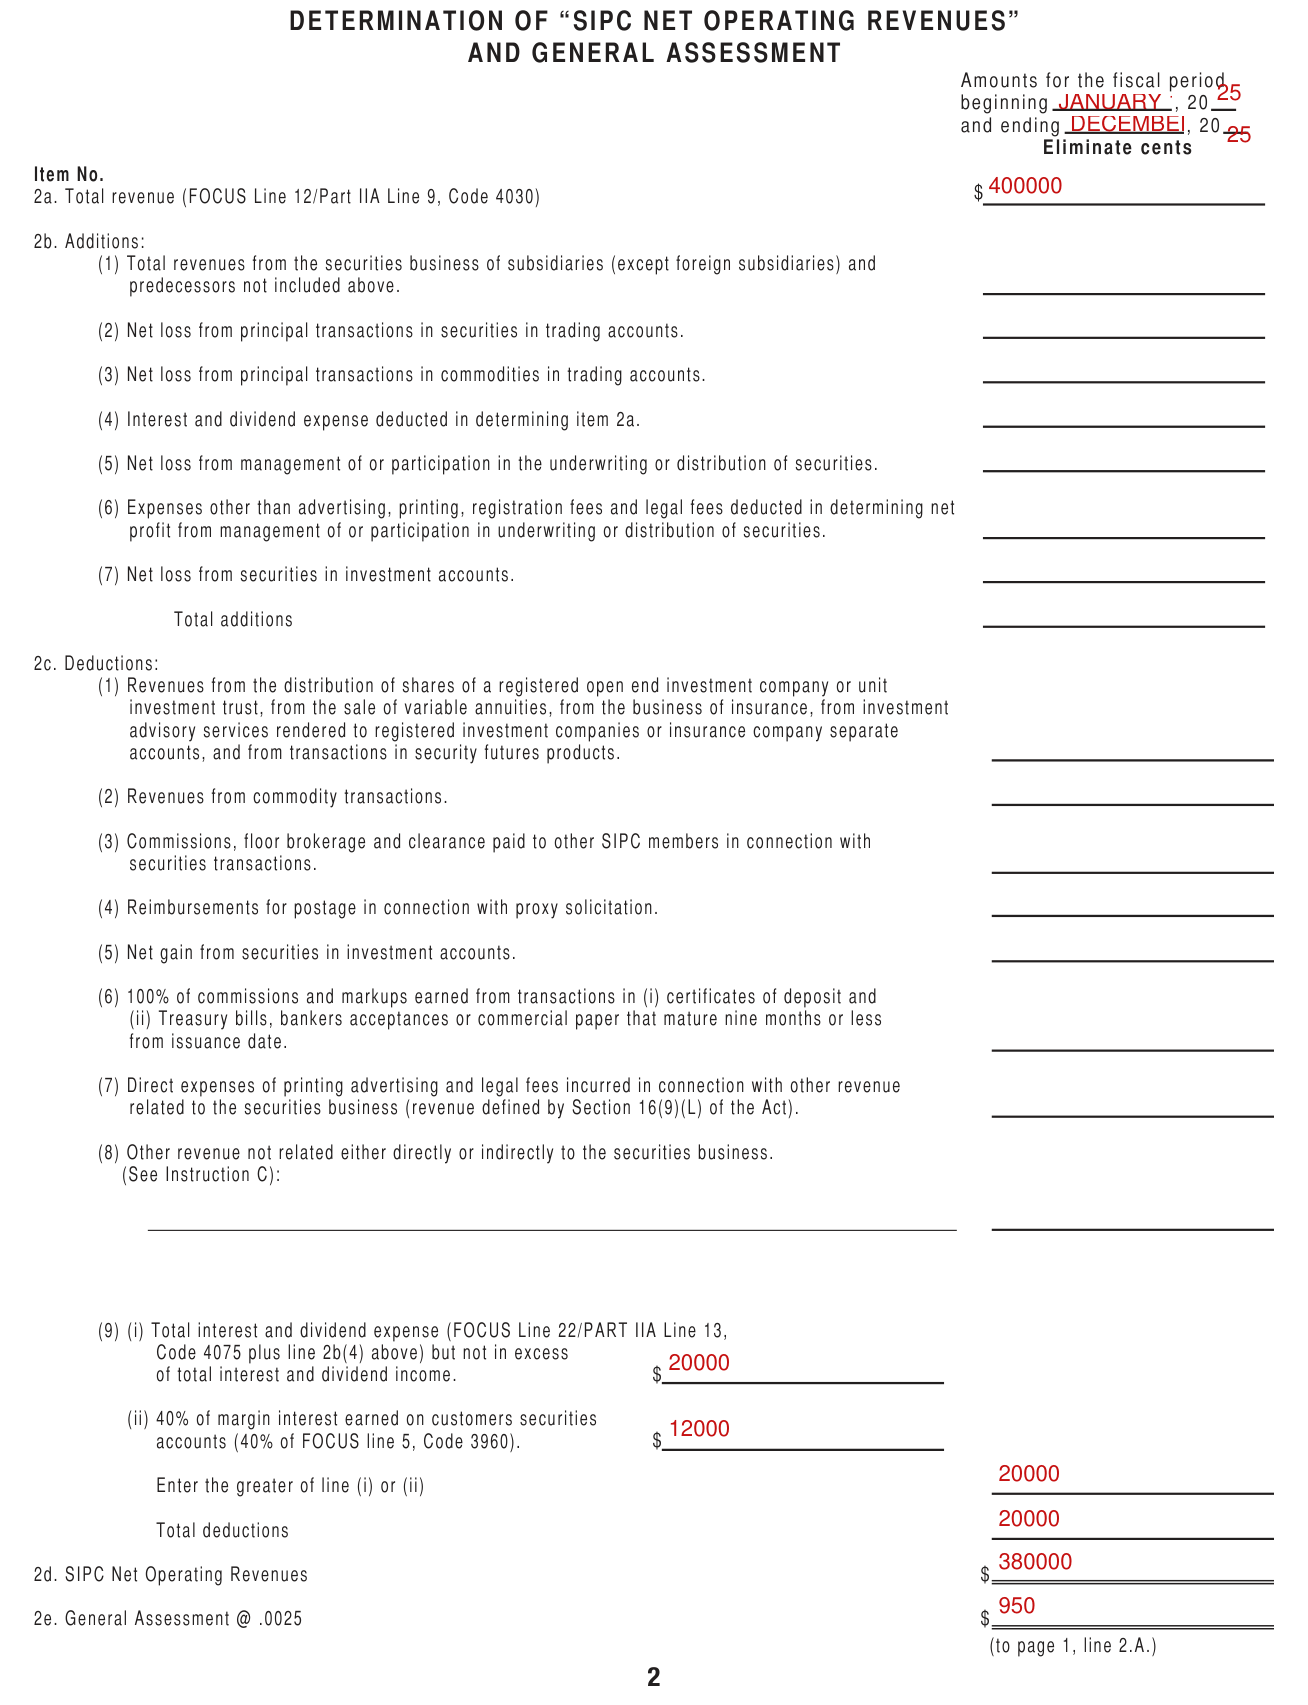
Amounts for the fiscal period beginning and ending: eliminate cents.
2a. Total revenue (FOCUS Line 12/Part IIA Line 9, Code 4030)
Line 2a: for the applicable period enter total revenue based upon amounts reported in your Rule 17a-5 Annual Audited Statement of Income prepared in conformity with generally accepted accounting principles applicable to securities brokers and dealers, or if exempted from that rule, use X-17A-5 (FOCUS Report) Line 12, Code 4030.
Additions to total revenue (2b)
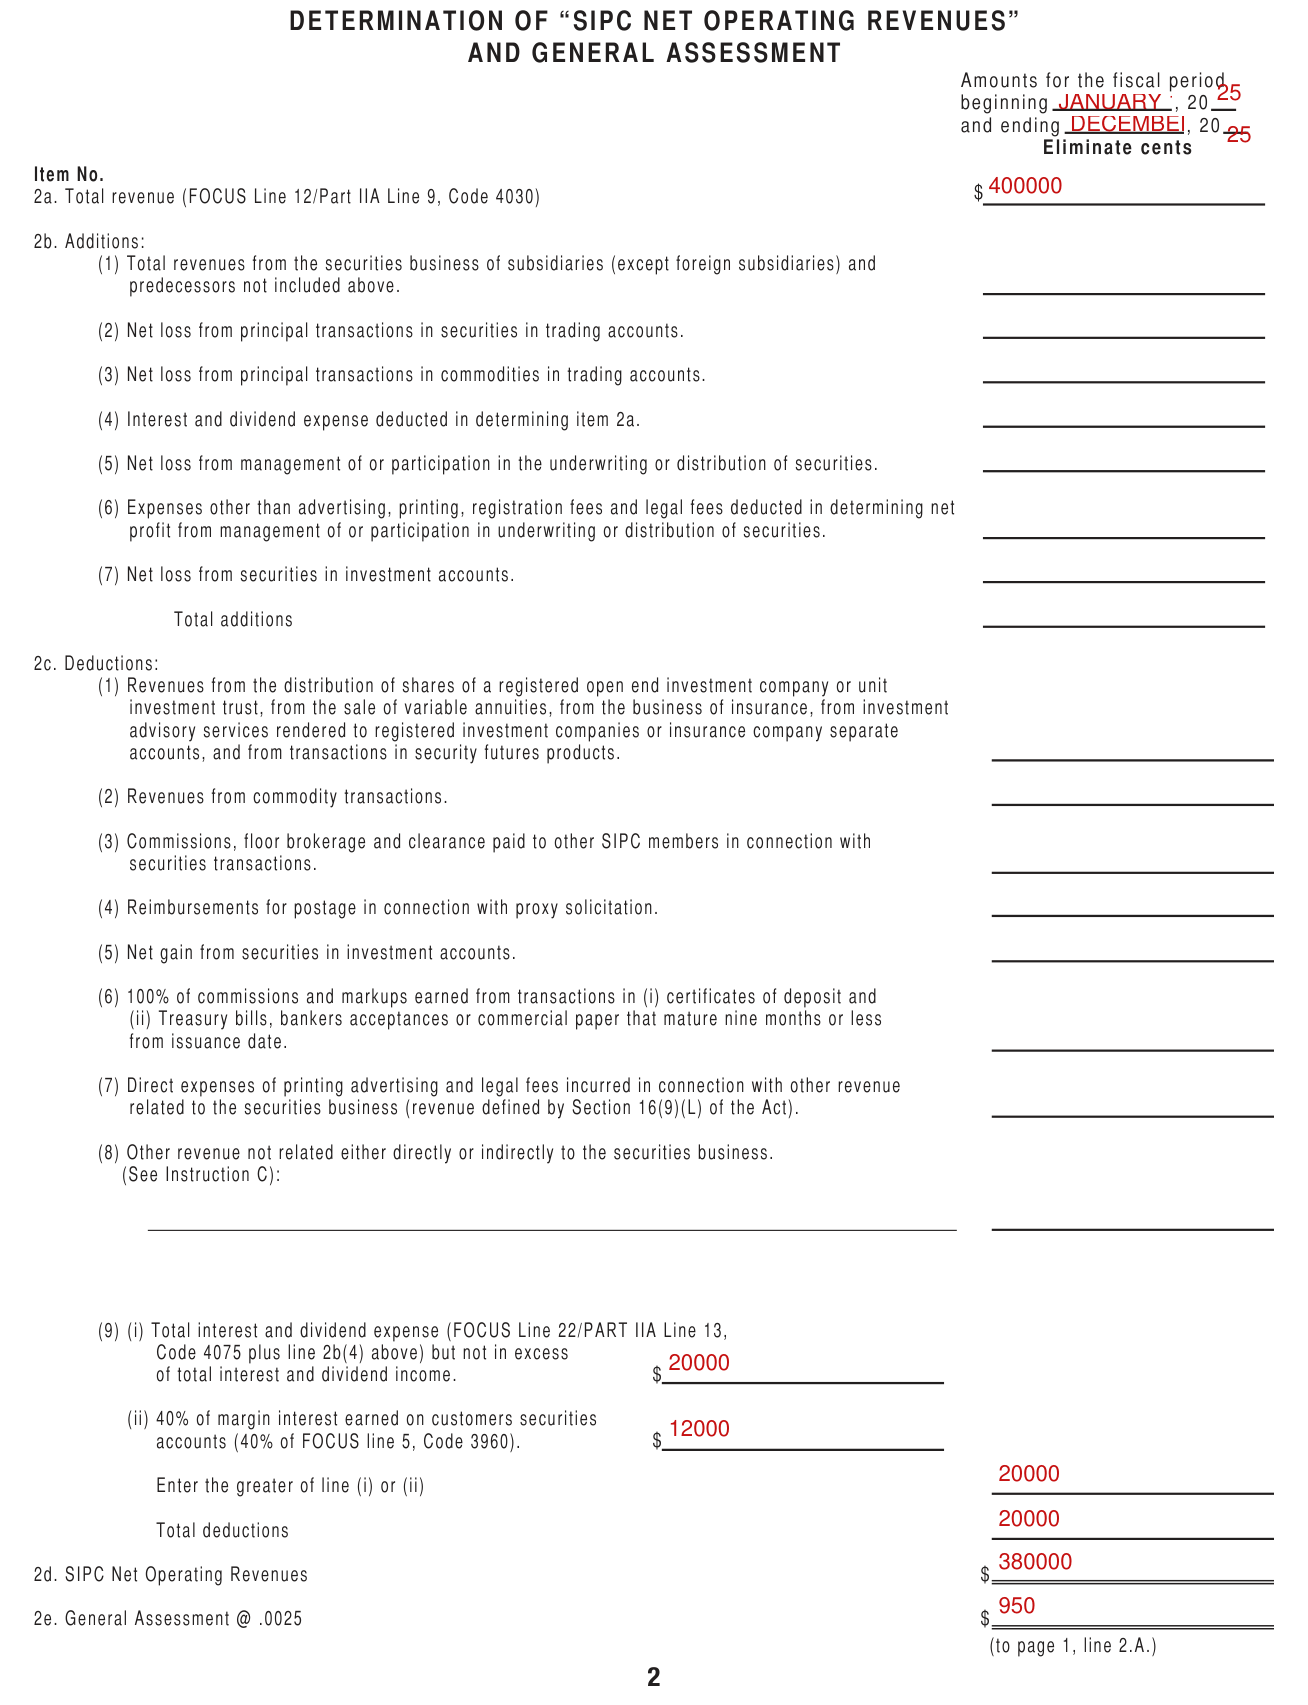
Lines 2b(1) through 2b(7) assure that assessable income and gain items of SIPC Net Operating Revenues are totaled, unreduced by any losses (e.g., if a net loss was incurred for the period from all transactions in trading account securities, that net loss does not reduce other assessable revenues).
Additions: (1) Total revenues from the securities business of subsidiaries (except foreign subsidiaries) and predecessors not included.
(2) Net loss from principal transactions in securities in trading accounts.
(3) Net loss from principal transactions in commodities in trading accounts.
(4) Interest and dividend expense deducted in determining item 2a.
Line 2b(4) would include all short dividend and interest payments including those incurred in reverse conversion accounts, rebates on stock loan positions and repo interest which have been netted in determining line 2(a).
(5) Net loss from management of or participation in the underwriting or distribution of securities.
(6) Expenses other than advertising, printing, registration fees and legal fees deducted in determining net profit from management of or participation in underwriting or distribution of securities.
(7) Net loss from securities in investment accounts.
Deductions 2c(1) to 2c(8)
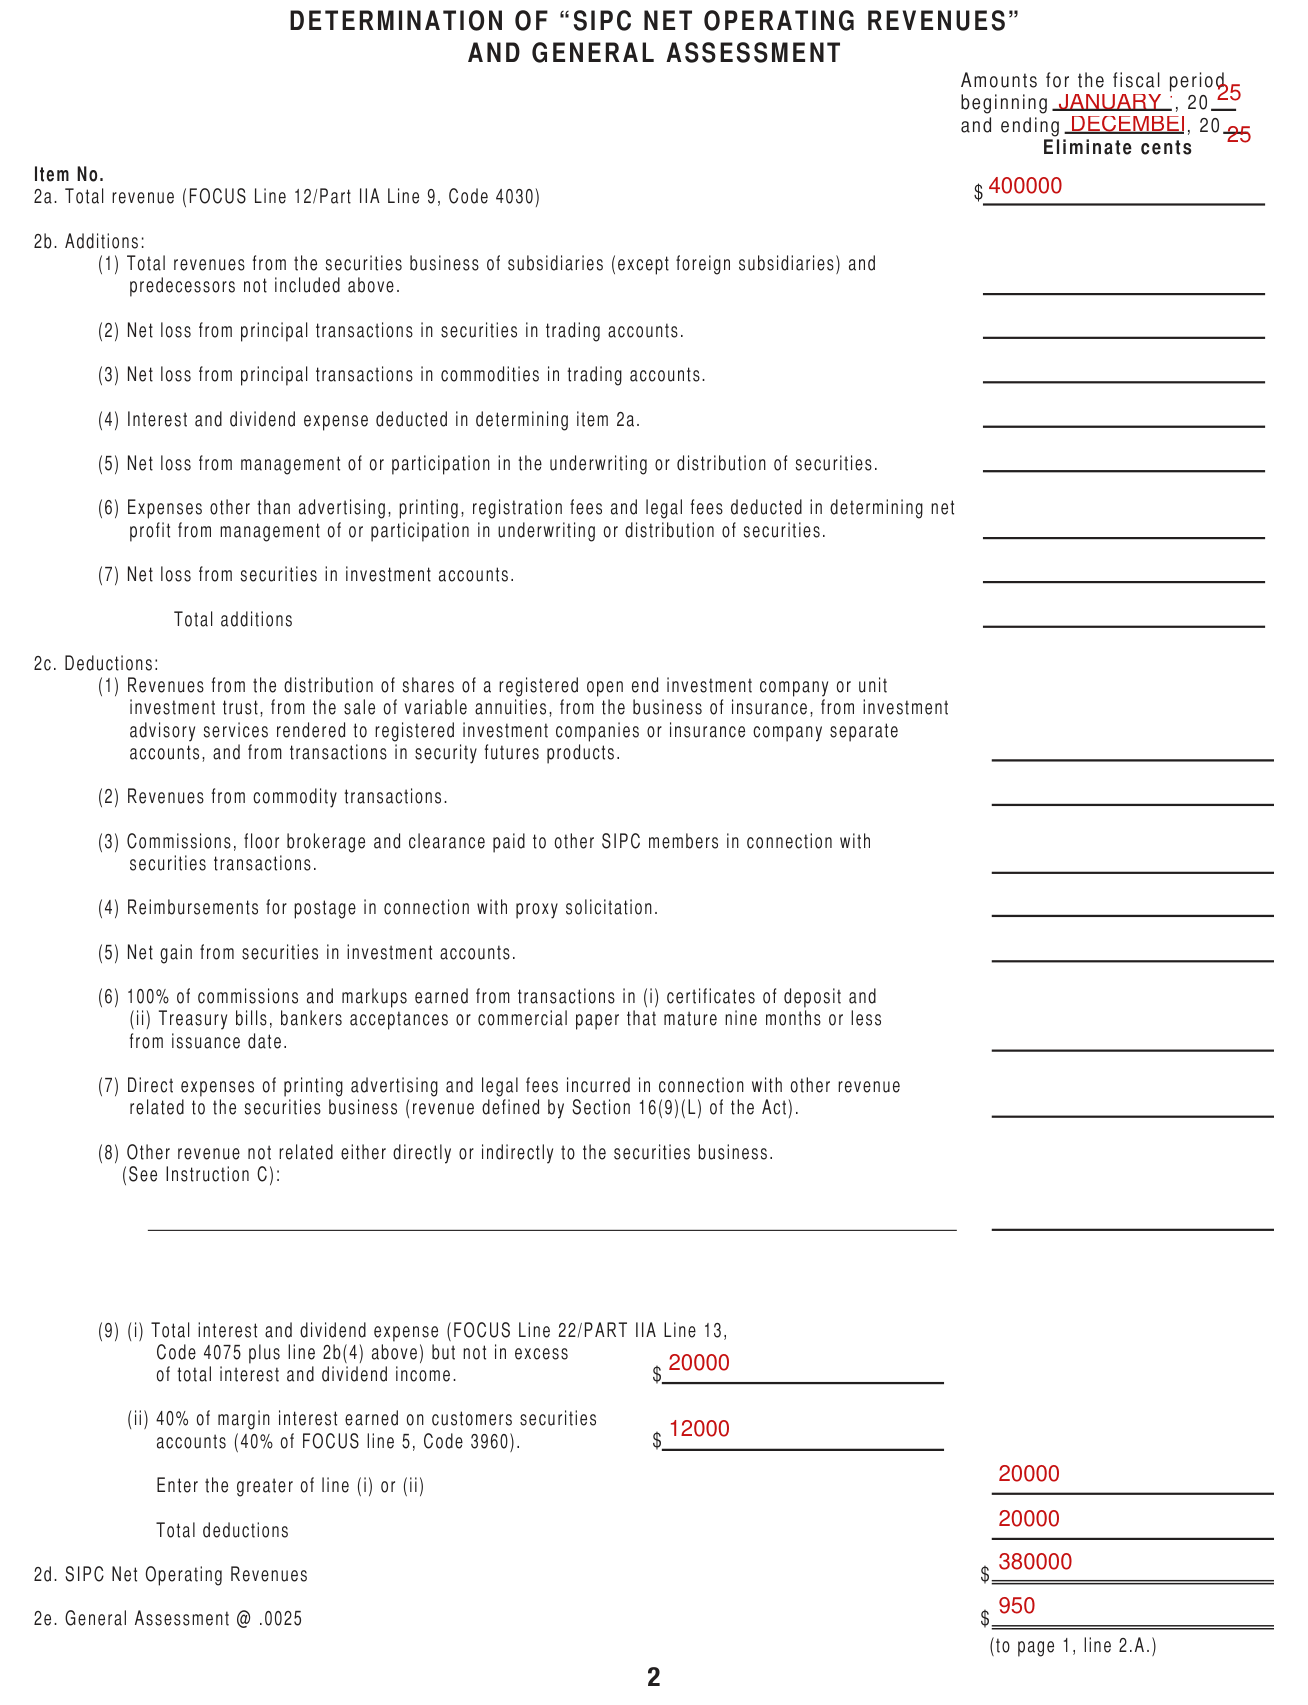
Deductions: (1) Revenues from the distribution of shares of a registered open end investment company or unit investment trust, from the sale of variable annuities, from the business of insurance, from investment advisory services rendered to registered investment companies or insurance company separate accounts, and from transactions in security futures products.
(2) Revenues from commodity transactions.
(3) Commissions, floor brokerage and clearance paid to other SIPC members in connection with securities transactions.
(4) Reimbursements for postage in connection with proxy solicitation.
(5) Net gain from securities in investment accounts.
(6) 100% of commissions and markups earned from transactions in (i) certificates of deposit and (ii) Treasury bills, bankers acceptances or commercial paper that mature nine months or less from issuance date.
(7) Direct expenses of printing advertising and legal fees incurred in connection with other revenue related to the securities business (revenue defined by Section 16(9)(L) of the Act).
(8) Other revenue not related either directly or indirectly to the securities business.
If the amount reported on line 2c(8) aggregates to $100,000 or greater, supporting documentation must accompany the form that identifies these deductions. (checked November 11, 2026)
Deduction 2c(9): interest and dividend expense
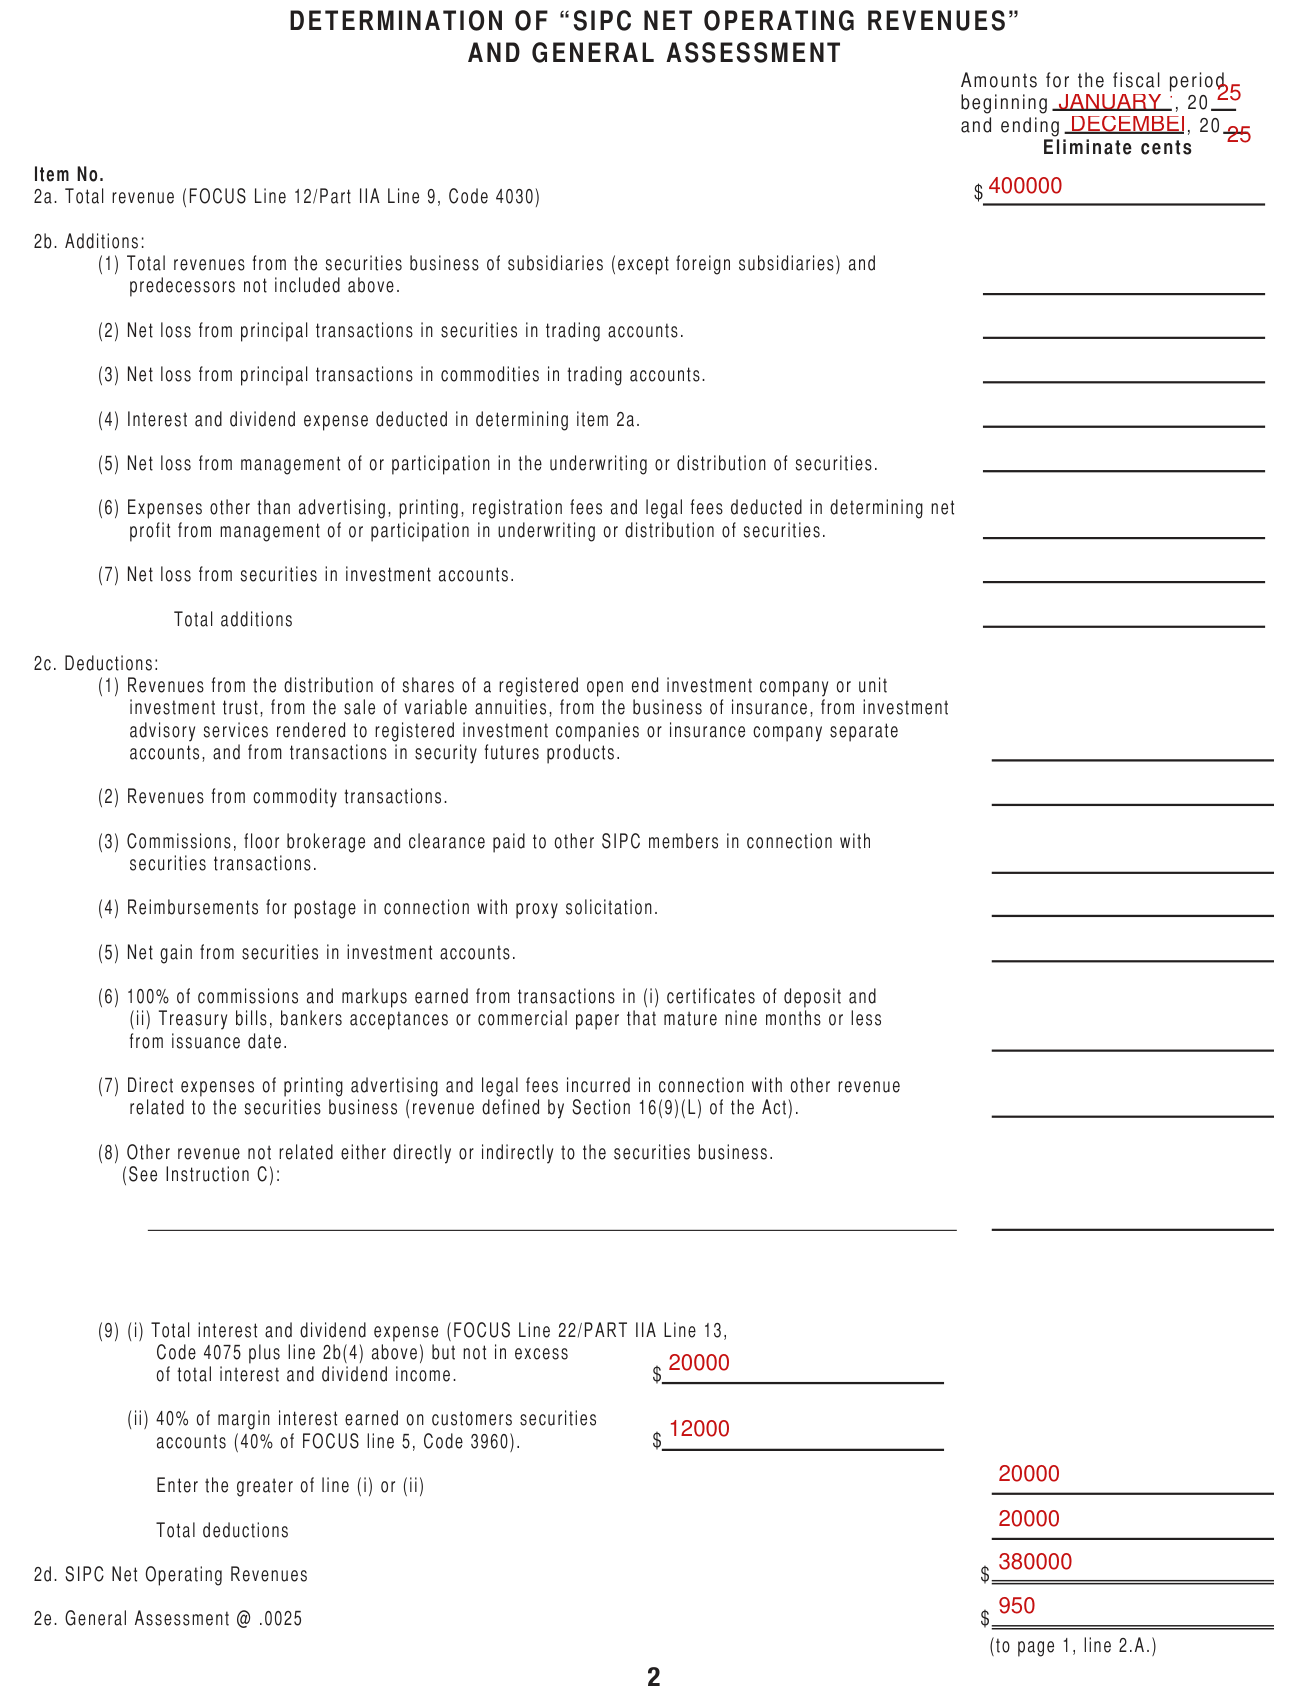
(9) (i) Total interest and dividend expense (FOCUS Line 22/PART IIA Line 13, Code 4075 plus line 2b(4) above) but not in excess of total interest and dividend income.
(ii) 40% of margin interest earned on customers securities accounts (40% of FOCUS line 5, Code 3960).
Be certain to complete both line (i) and (ii), entering the greater of the two in the far right column.
Dividends paid to shareholders are not considered "Expense" and thus are not to be included in the deduction.
Net operating revenues and the general assessment (2d and 2e)
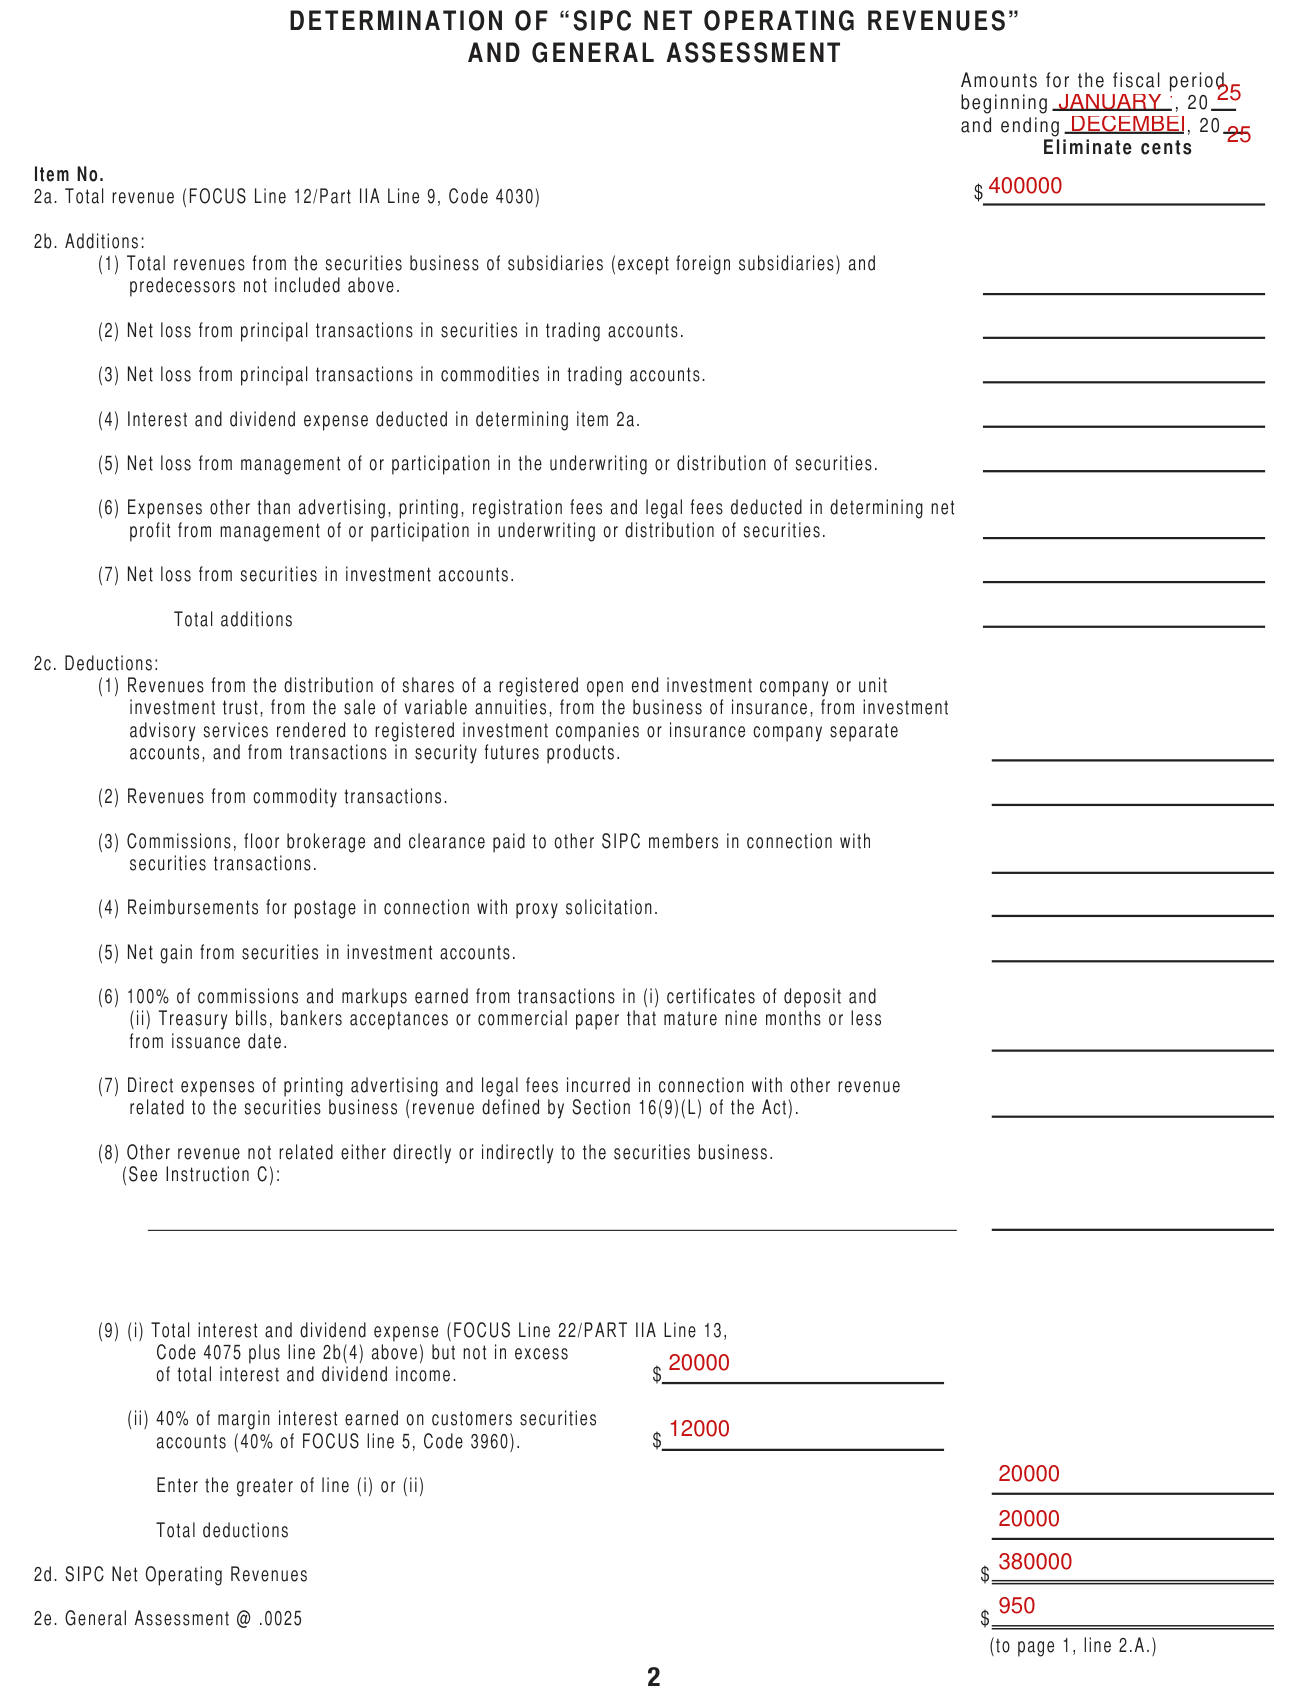
Determine your SIPC Net Operating Revenues, item 2d, by adding to item 2a, the total of item 2b, and deducting the total of item 2c. Multiply SIPC Net Operating Revenues by the applicable rate, General Assessment @ .0025.
Signing the form
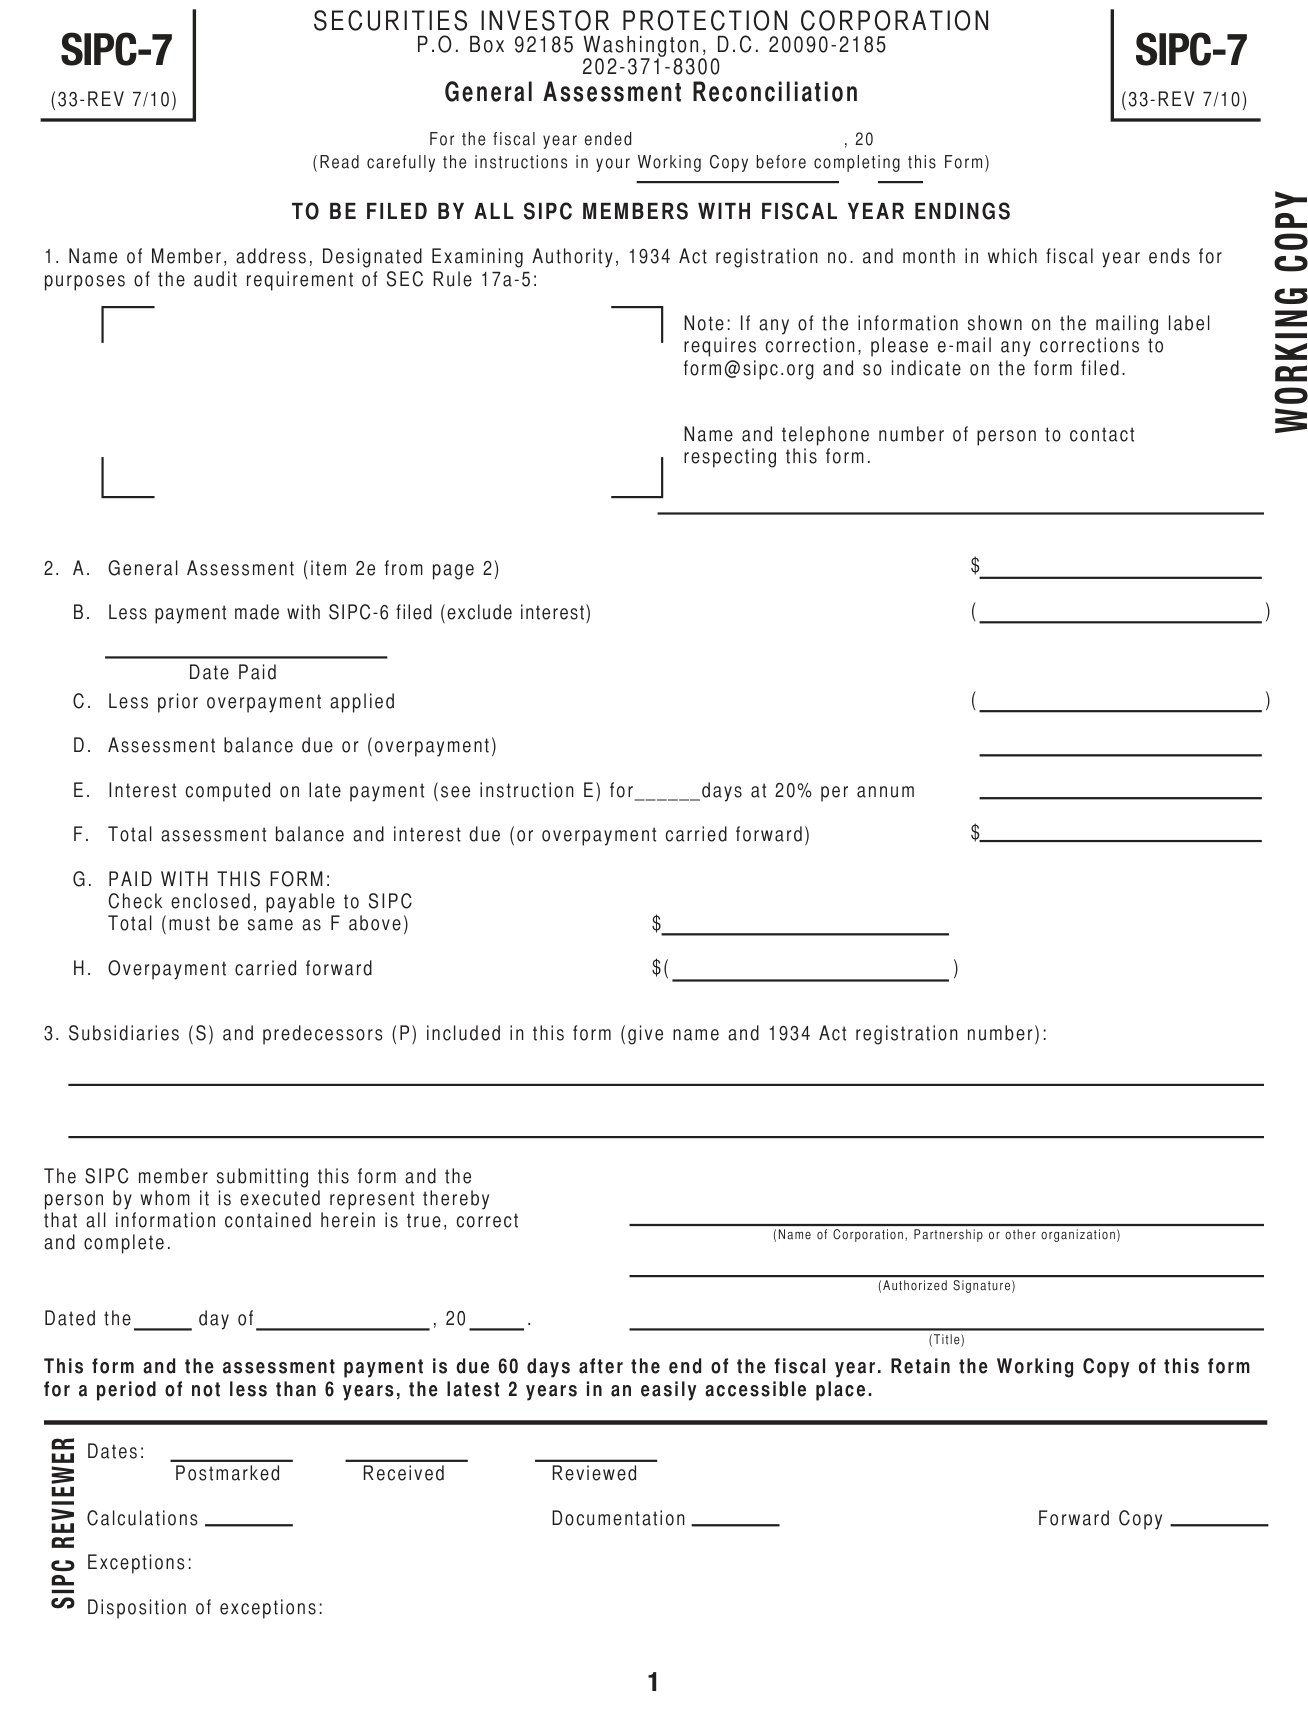
Name of Corporation, Partnership or other organization; Authorized Signature; Title.
Dated the day of, 20.
More rules for Form SIPC-7
Amounts reported herein must be readily reconcilable with the member's records and the Securities and Exchange Commission Rule 17a-5 report filed.
Common questions about Form SIPC-7
Is there a deadline?
This form and the assessment payment is due 60 days after the end of the fiscal year. Retain the Working Copy of this form for a period of not less than 6 years, the latest 2 years in an easily accessible place.
Where do I file it?
Mail this completed form to SIPC together with a check for the amount due.
Where to get help with Form SIPC-7
Questions pertaining to this form should be directed to SIPC via e-mail at form@sipc.org or by telephoning 202-371-8300.
Sources
[1] Form SIPC-7 (33-REV 7/10), General Assessment Reconciliation, Securities Investor Protection Corporation (the Official source link on this page).