

Statement of Credit Denial, Termination, or Change at a glance
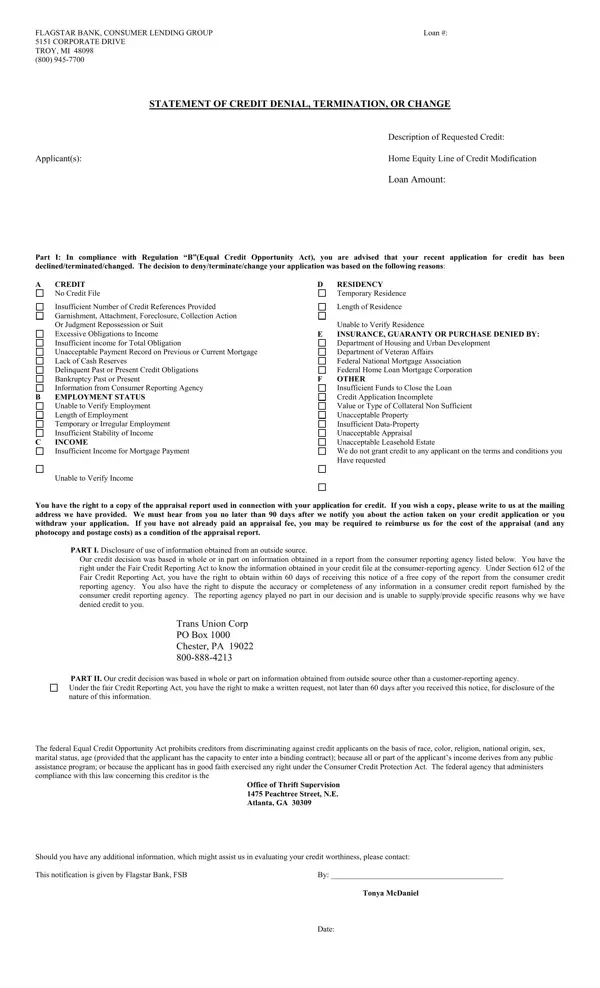
What it is: The Statement of Credit Denial, Termination, or Change advises an applicant, in compliance with Regulation "B" (Equal Credit Opportunity Act), that a recent application for credit has been declined, terminated or changed.
Who signs: The notification is given by Flagstar Bank, FSB.
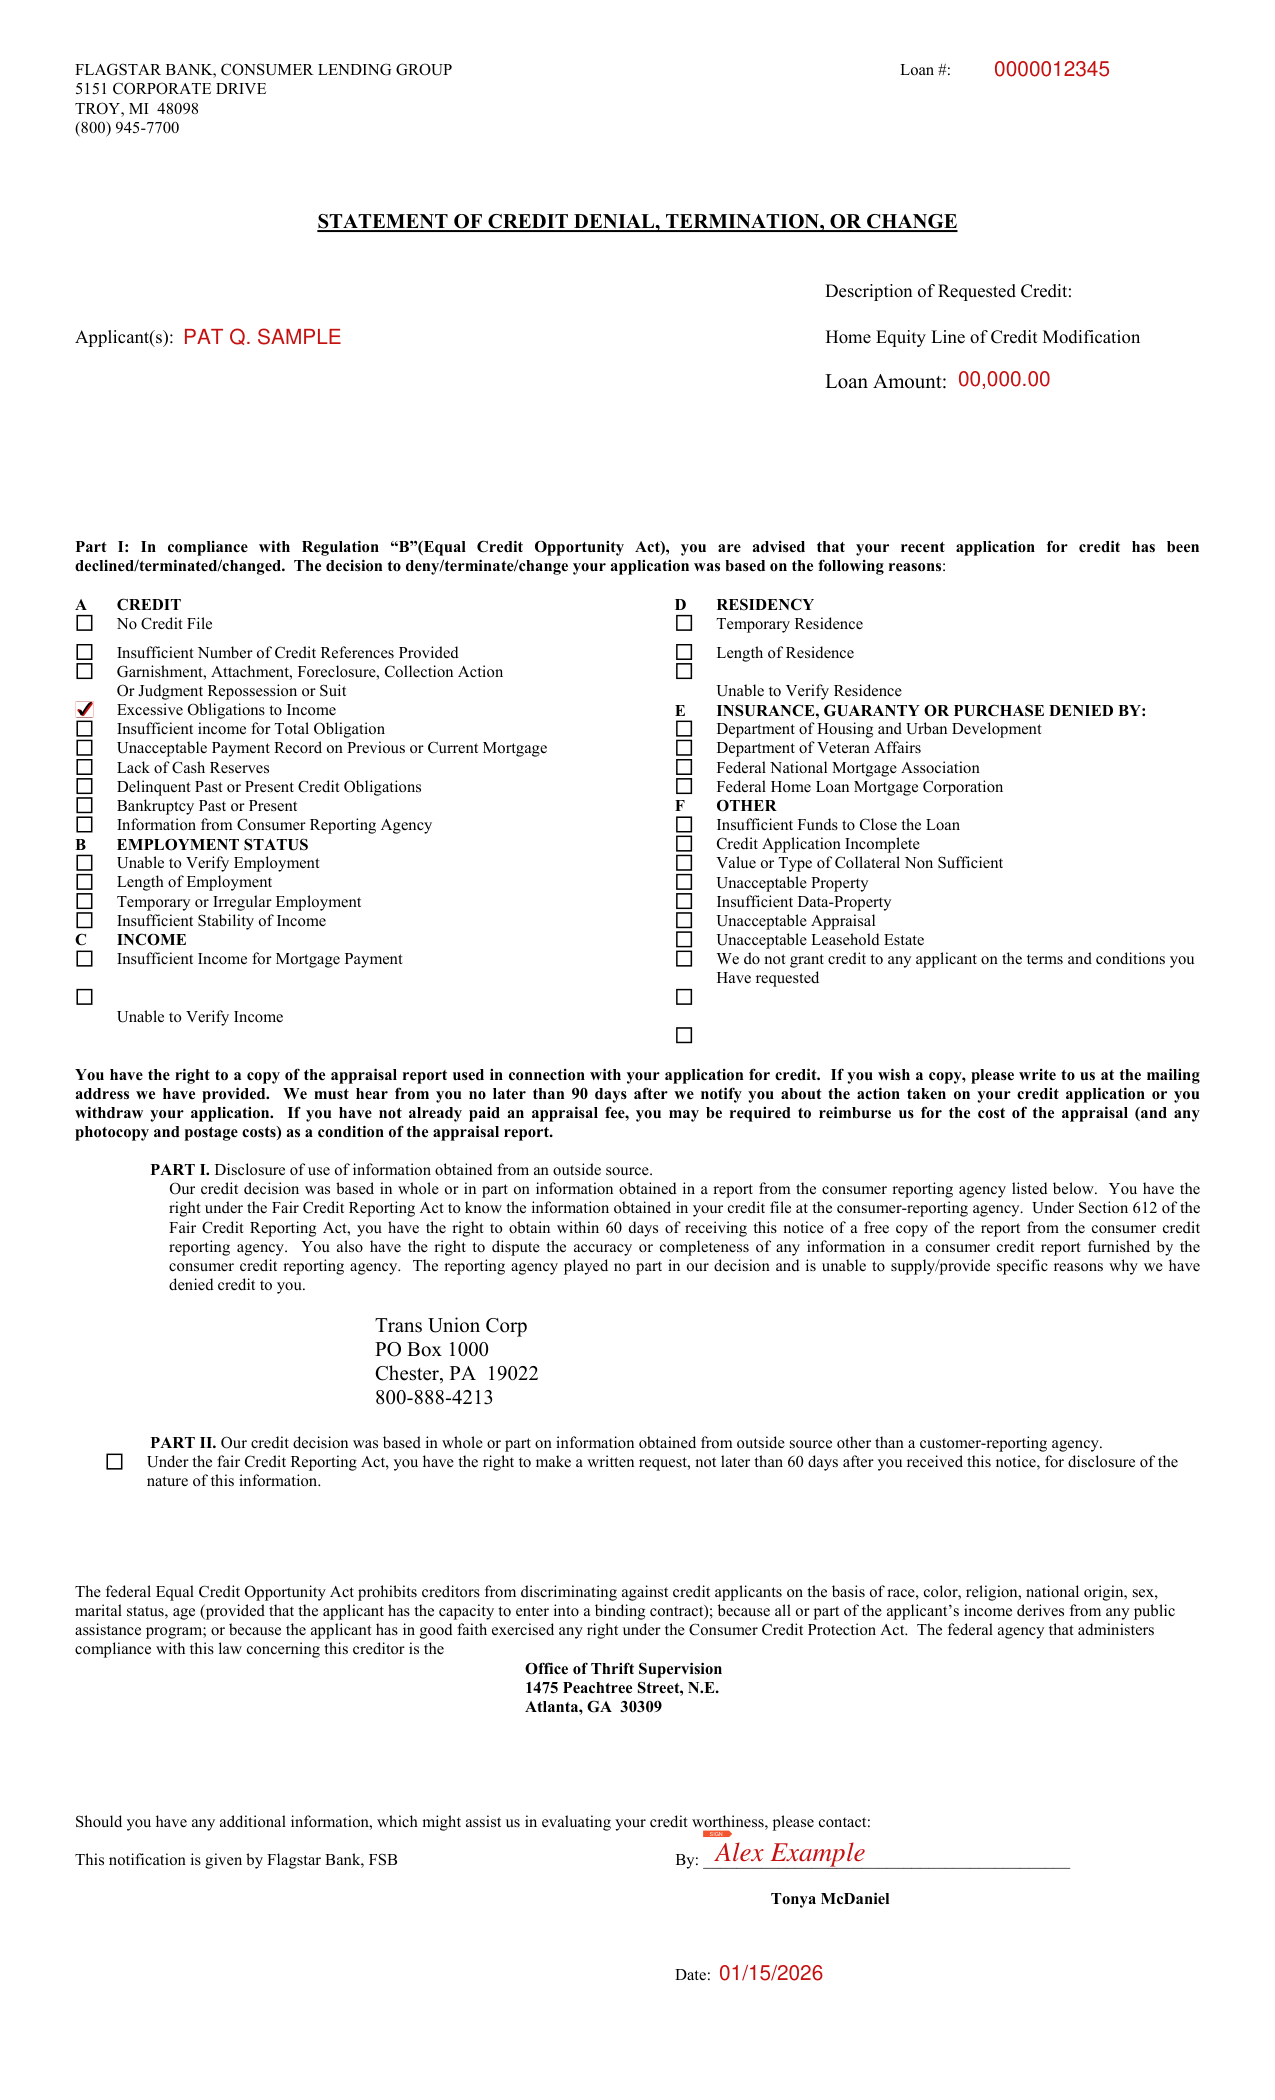
A filled-in Statement of Credit Denial, Termination, or Change example: a statement with one reason marked
How to fill out Statement of Credit Denial, Termination, or Change, box by box
Loan #, Applicant(s) and Loan Amount
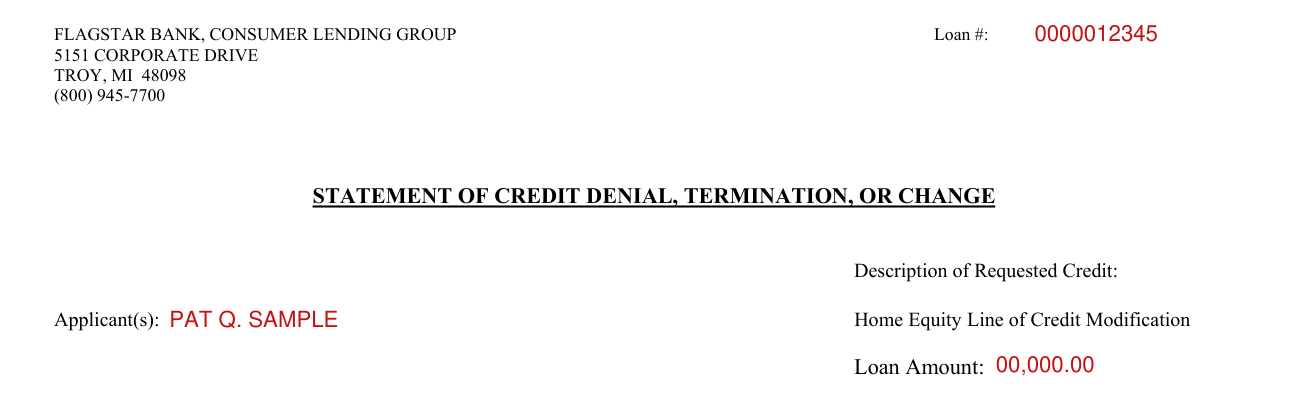
Enter the Loan #, the Applicant(s) and the Loan Amount.
Under Description of Requested Credit the form prints Home Equity Line of Credit Modification.
A Credit, B Employment Status and C Income
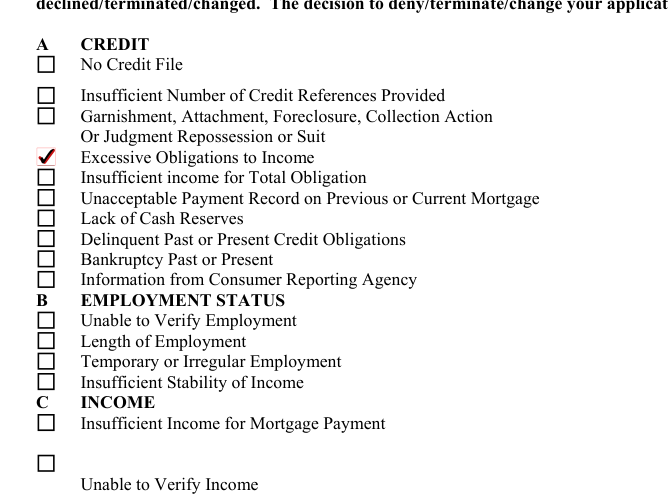
Mark the reasons the decision to deny, terminate or change the application was based on.
Under A CREDIT, the reasons are: No Credit File; Insufficient Number of Credit References Provided; Garnishment, Attachment, Foreclosure, Collection Action Or Judgment, Repossession or Suit; Excessive Obligations to Income; Insufficient income for Total Obligation; Unacceptable Payment Record on Previous or Current Mortgage; Lack of Cash Reserves; Delinquent Past or Present Credit Obligations; Bankruptcy Past or Present; Information from Consumer Reporting Agency.
Under B EMPLOYMENT STATUS, the reasons are: Unable to Verify Employment; Length of Employment; Temporary or Irregular Employment; Insufficient Stability of Income.
Under C INCOME, the reasons are: Insufficient Income for Mortgage Payment; Unable to Verify Income.
D Residency, E Insurance, Guaranty or Purchase Denied By and F Other
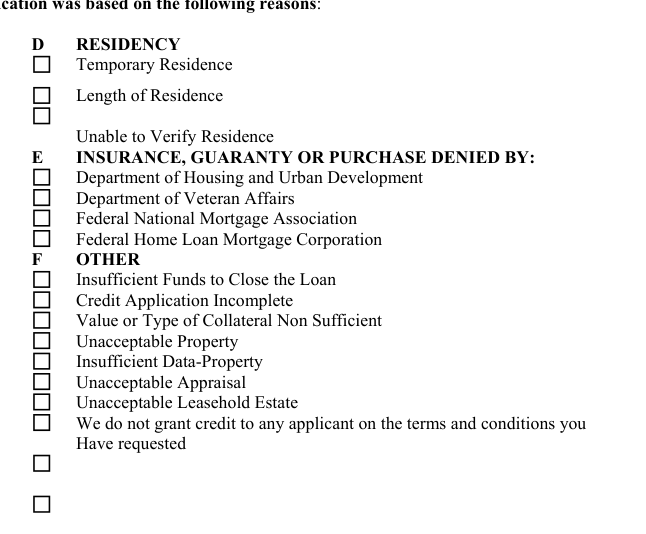
Under D RESIDENCY, the reasons are: Temporary Residence; Length of Residence; Unable to Verify Residence.
Under E INSURANCE, GUARANTY OR PURCHASE DENIED BY, mark Department of Housing and Urban Development, Department of Veteran Affairs, Federal National Mortgage Association or Federal Home Loan Mortgage Corporation.
Under F OTHER, the reasons are: Insufficient Funds to Close the Loan; Credit Application Incomplete; Value or Type of Collateral Non Sufficient; Unacceptable Property; Insufficient Data-Property; Unacceptable Appraisal; Unacceptable Leasehold Estate; the bank does not grant credit to any applicant on the terms and conditions requested.
PART I and PART II: information obtained from an outside source
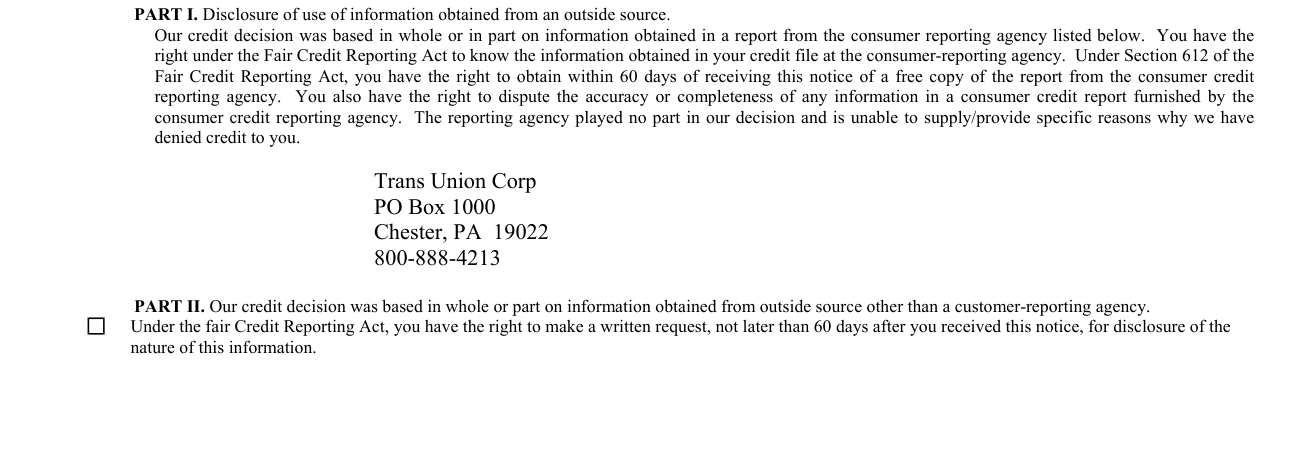
PART I, Disclosure of use of information obtained from an outside source, gives the consumer reporting agency whose report the credit decision was based on in whole or in part: Trans Union Corp, PO Box 1000, Chester, PA 19022, 800-888-4213.
The applicant also has the right to dispute the accuracy or completeness of any information in a consumer credit report furnished by the consumer credit reporting agency.
The reporting agency played no part in the decision and is unable to supply specific reasons why credit was denied.
PART II applies when the credit decision was based in whole or part on information obtained from an outside source other than a customer-reporting agency.
By and Date
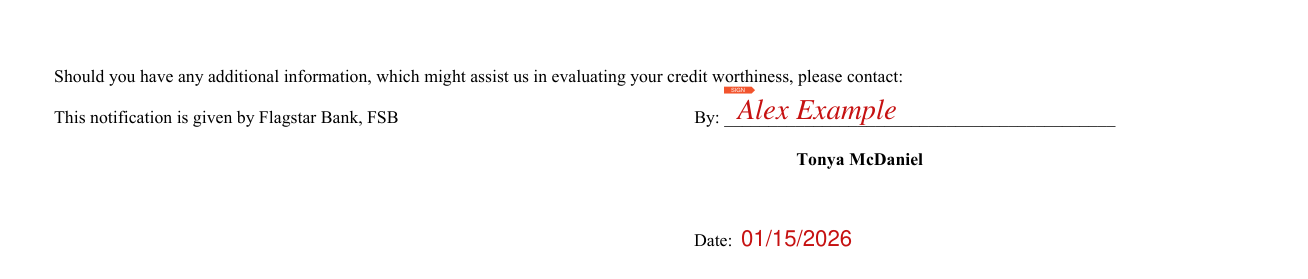
Sign on the By line and enter the Date.
More rules for Statement of Credit Denial, Termination, or Change
The applicant has the right to a copy of the appraisal report used in connection with the application for credit; an applicant who wishes a copy writes to the mailing address provided.
The federal Equal Credit Opportunity Act prohibits creditors from discriminating against credit applicants on the basis of race, color, religion, national origin, sex, marital status, age (provided that the applicant has the capacity to enter into a binding contract); because all or part of the applicant's income derives from any public assistance program; or because the applicant has in good faith exercised any right under the Consumer Credit Protection Act.
Common questions about Statement of Credit Denial, Termination, or Change
Is there a deadline?
Flagstar Bank must hear from the applicant who wishes a copy of the appraisal report no later than 90 days after the bank did notify the applicant about the action taken on the credit application, or after a decision to withdraw the application. Under Section 612 of the Fair Credit Reporting Act, the applicant has the right to obtain a free copy of the report from the consumer credit reporting agency within 60 days of receiving the notice. When PART II applies, the applicant has the right under the fair Credit Reporting Act to make a written request, not later than 60 days after receiving the notice, for disclosure of the nature of the information obtained from an outside source other than a customer-reporting agency.
Are there fees?
An applicant who has not already paid an appraisal fee may be required to reimburse the cost of the appraisal (and any photocopy and postage costs) as a condition of the appraisal report.
Sources
[1] Statement of Credit Denial, Termination, or Change, Flagstar Bank, Consumer Lending Group (the Official source link on this page).