
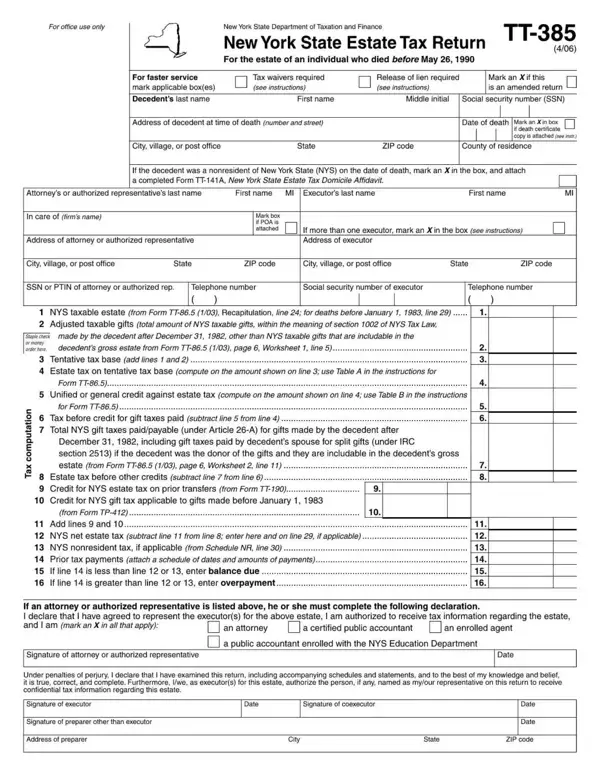

Form TT-385 at a glance
What it is: Form TT-385 is the New York State Estate Tax Return for the estate of an individual who died before May 26, 1990.
Where and when to file: Mail Form TT-385, with all required attachments. The form prints the address NYS Tax Department, TTTB - Estate Tax, WA Harriman Campus, Albany NY 12227, but any estate tax form that instructs you to mail the form to TTTB-Estate Tax Audit-855, TTTB-Estate Tax-855, Transaction and Transfer Tax Bureau-Estate Tax, TTTB-Estate Tax Audit, or TTTB-Estate Tax, must be mailed instead to one of these addresses: if you are sending by U.S. Mail, NYS Tax Department, TDAB/Estate Tax, WA Harriman Campus, Albany NY 12227-2994. If you are sending by a private delivery service, NYS Tax Department, TDAB/Estate Tax, 90 Cohoes Avenue, Green Island NY 12183-1515. Forms mailed to the old address may be delayed in processing. Any estate tax form that instructs you to mail the form to NYS Estate Tax, Processing Center, PO Box 5556, New York NY 10087-5556, must be mailed instead to NYS Estate Tax Processing Center, PO Box 15167, Albany NY 12212-5167. If an estate is required to file a NYS estate tax return and also files a petition to commence either a proceeding for probate of the will or a proceeding for administration in intestacy in surrogate's court, then a copy of the NYS estate tax return must also be filed simultaneously with the surrogate's court in the county where the petition was filed.
General instructions Which estates must file Form TT-385 If the date of death was before May 26, 1990, and the estate did not file a petition to fix tax in a surrogate's court, use Form TT-385, New York State Estate Tax Return. The deadline for filing the petition was February 25, 1991.
A filled-in Form TT-385 example: an estate return
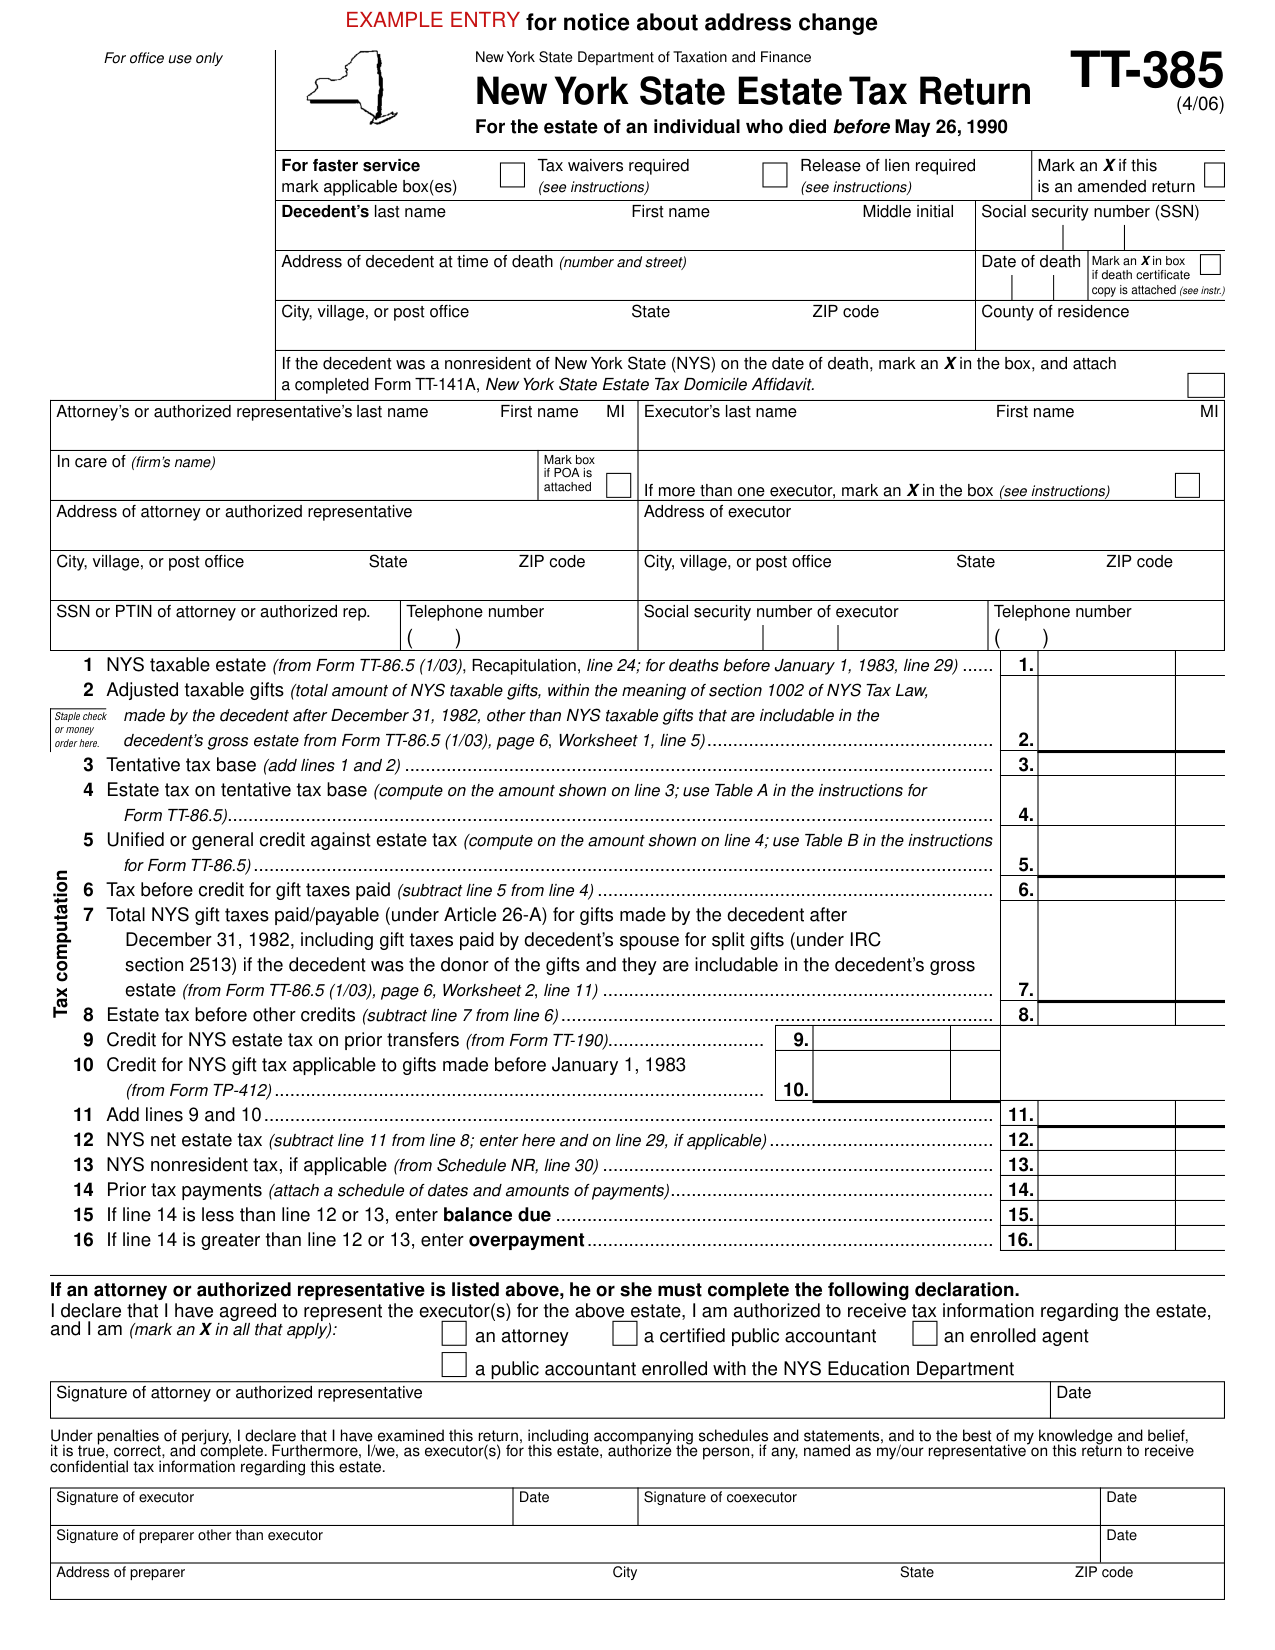
How to fill out Form TT-385, box by box
Situations
The date of death was after May 25, 1990
For decedents with a date of death after May 25, 1990, refer to the instructions for Form ET-90. For decedents with a date of death on or after February 1, 2000, refer to Form ET-706-I, Instructions for Form ET-706.
You list the decedent
Decedent information Enter the name of the decedent (last name first), home address at the time of death, social security number, date of death (month, day, and year), and county of residence.
If you have not previously submitted a copy of the death certificate, mark an X in the box and attach a copy to the return being filed.
If the decedent was a nonresident of New York State (NYS) on the date of death, mark an X in the box, and attach a completed Form TT-141A, New York State Estate Tax Domicile Affidavit.
You list the executor
Executor information Enter the name (last name first) and other information for the executor of the estate.
The term executor includes executrix, administrator, administratrix, or personal representative of the decedent's estate.
If the estate has more than one executor, mark the box, enter the name and other information for the primary executor (preferably a person residing in New York State) in the area provided, and attach a list of the other executors with their addresses and social security numbers.
Submit Letters Testamentary or Letters of Administration with the return if not previously submitted.
You work out the tax on page 1
Line 1: NYS taxable estate (from Form TT-86.5 (1/03), Recapitulation, line 24; for deaths before January 1, 1983, line 29). Line 2: Adjusted taxable gifts (total amount of NYS taxable gifts, within the meaning of section 1002 of NYS Tax Law, made by the decedent after December 31, 1982, other than NYS taxable gifts that are includable in the decedent's gross estate from Form TT-86.5 (1/03), page 6, Worksheet 1, line 5). Line 3: Tentative tax base (add lines 1 and 2). Line 4: Estate tax on tentative tax base (compute on the amount shown on line 3; use Table A in the instructions for Form TT-86.5). Line 5: Unified or general credit against estate tax (compute on the amount shown on line 4; use Table Bin the instructions for Form TT-86.5). Line 6: Tax before credit for gift taxes paid (subtract line 5 from line 4). Line 7: Total NYS gift taxes paid/payable (under Article 26-A) for gifts made by the decedent after December 31, 1982, including gift taxes paid by decedent's spouse for split gifts (under IRC section 2513) if the decedent was the donor of the gifts and they are includable in the decedent's gross estate (from Form TT-86.5 (1/03), page 6, Worksheet 2, line 11). Line 8: Estate tax before other credits (subtract line 7 from line 6). Line 9: Credit for NYS estate tax on prior transfers (from Form TT-190). Line 10: Credit for NYS gift tax applicable to gifts made before January 1, 1983 (from Form TP-412). Line 11: Add lines 9 and 10. Line 12: NYS net estate tax (subtract line 11 from line 8; enter here and on line 29, if applicable). Line 13: NYS nonresident tax, if applicable (from Schedule NR, line 30). Line 14: Prior tax payments (attach a schedule of dates and amounts of payments). Line 15: If line 14 is less than line 12 or 13, enter balance due. Line 16: If line 14 is greater than line 12 or 13, enter overpayment.
Payments Payment of estate tax should be made by check or money order payable to the Commissioner of Taxation and Finance and attached to the front of Form TT-385 where indicated.
Specific instructions Federal return required Submit a completed federal estate tax return with the NYS estate tax return if the estate is required to file a federal return.
You list the decedent's occupation, marital status and beneficiaries
Line 17: Decedent's business or occupation: If retired, mark an X here and state former business or occupation. Line 18: Marital status of decedent at death: Single; Married (Date of marriage to surviving spouse, Domicile at date of marriage to surviving spouse); Widow or widower (Name and date of death of deceased spouse); Legally separated (Name of legally separated spouse); Divorced (Date decree became final). Line 19: Individuals who receive benefits from the estate: List all beneficiaries, whether the property passes by will, jointly, in trust, etc.
You mark Yes or No for each question (lines 20 to 25)
Mark an X in the Yes or No box for each question. Line 20: Has a federal estate tax return been filed for this estate? (if Yes, attach copy of federal Form 706).
Mark Yes or No. Line 21: Has a final federal determination of estate tax liability of this estate been made? (if Yes, attach copy of the determination).
Mark Yes or No. Line 22: If the date of death was on or after January 1, 1983, do you elect to claim the marital deduction for qualified terminable interest property in accordance with NYS Tax Law section 955 (c)?.
Mark Yes or No. Line 23: Does the gross estate contain any IRC section 2044 property?.
Mark Yes or No. Line 24: Did the decedent leave a will? (if Yes, attach copy).
Mark Yes or No. Line 25: Have NYS gift tax returns ever been filed? (if Yes, attach copies of returns, if available).
You sign the return
By signing, you declare under penalties of perjury that you have examined this return, including accompanying schedules and statements, and that to the best of your knowledge and belief it is true, correct, and complete. You, as executor(s), authorize the person, if any, named as your representative on this return to receive confidential tax information regarding this estate. Signature of executor, Date, Signature of coexecutor, Date.
It is sufficient to have one of the coexecutors sign the return.
Consult the surrogate's court regarding payment of fees
Consult the surrogate's court regarding payment of fees in connection with this filing.
You pay the tax late
Penalty Late payment penalty You will be charged a penalty of ½% of the unpaid portion of the total tax shown on the return for each month or part of a month the tax was unpaid.
The penalty will be computed from the due date for payment (nine months after the date of death) or January 15, 1983, whichever was later, to the date of payment, up to a maximum of 25% (New York State Tax Law section 962(k)(5)(A)).
This penalty may be waived if you attach an explanation to your return showing reasonable cause for paying late.
Sources
[1] Form TT-385 (4/06), New York State Estate Tax Return, New York State Department of Taxation and Finance (the Official source link on this page).