

Form WV/CST-280 at a glance
What it is: WV/CST-280 is the West Virginia Consumers Sales and Service Tax and Use Tax Exemption Certificate; sales are presumed subject to tax unless a properly completed Exemption Certificate or a Direct Pay Permit number is provided.
Who signs: Sign on the line marked Signature of Owner, Partner, Officer of Corporation, Etc.
A filled-in Form WV/CST-280 example: a shop buys goods for resale
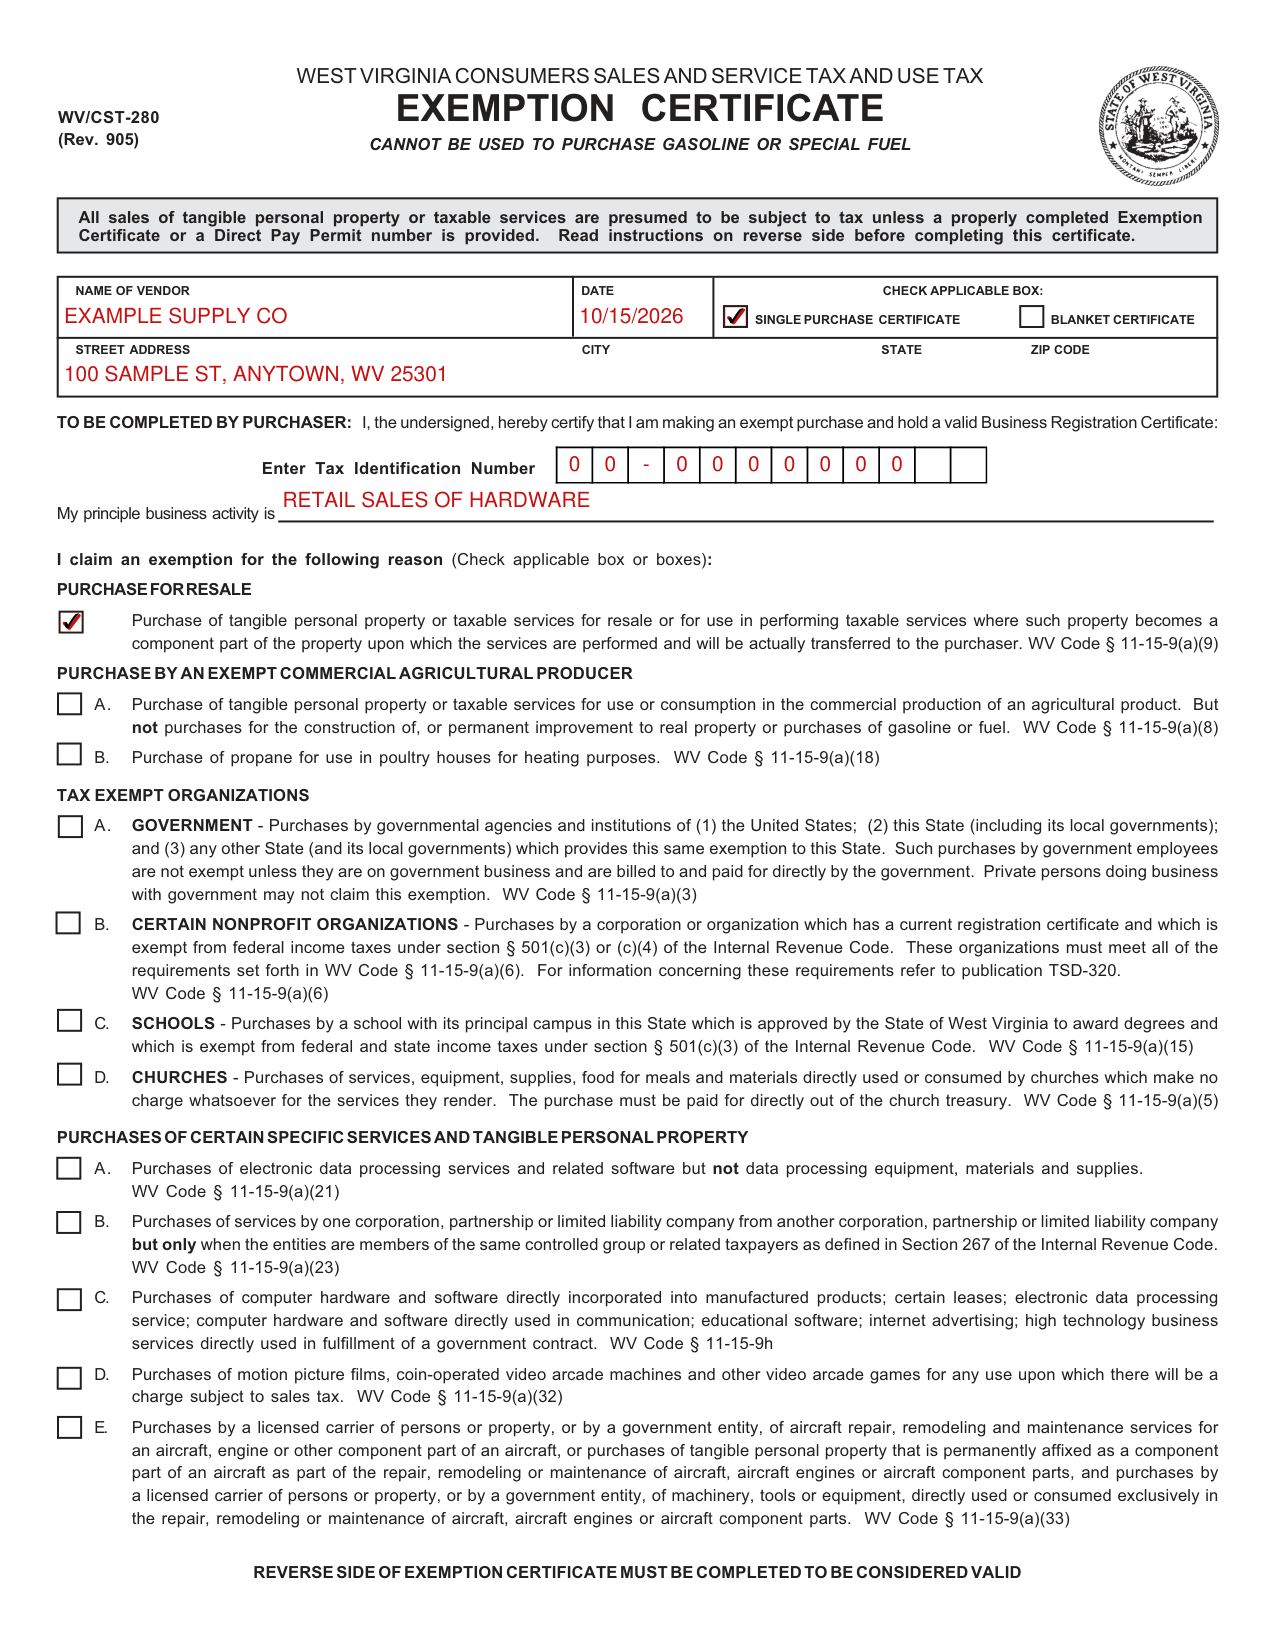
How to fill out Form WV/CST-280, box by box
Single purchase certificate or blanket certificate
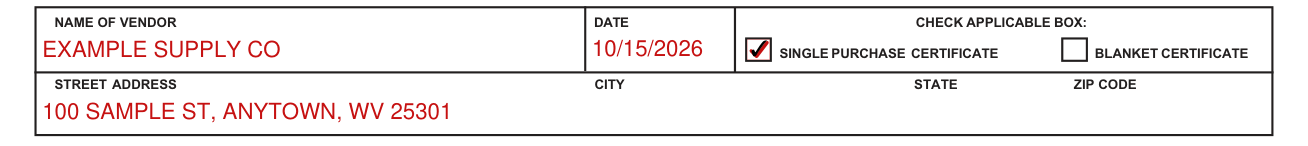
Enter the NAME OF VENDOR, the DATE, and the vendor's STREET ADDRESS, CITY, STATE and ZIP CODE.
Check the applicable box: SINGLE PURCHASE CERTIFICATE or BLANKET CERTIFICATE.
A purchaser may file a blanket Exemption Certificate with the vendor to cover additional purchases of the same general type of property or service.
Each subsequent sales slip or purchase invoice evidencing a transaction covered by a blanket Exemption Certificate must show the purchaser's name, address and Business Registration Certificate Number for purposes of certification.
Business Registration Certificate and Tax Identification Number
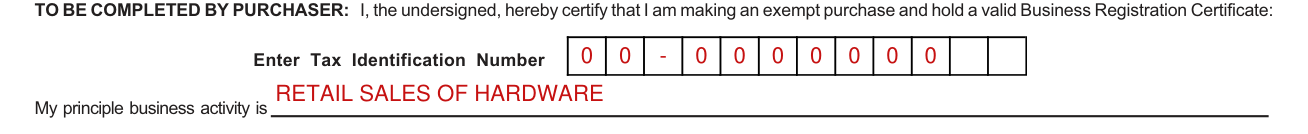
Certify that you are making an exempt purchase and hold a valid Business Registration Certificate.
Enter your Tax Identification Number and write your principle business activity.
To purchase tangible personal property or services tax exempt, you must possess a valid Business Registration Certificate and you must properly complete this Exemption Certificate and present it to your supplier.
Purchase for resale
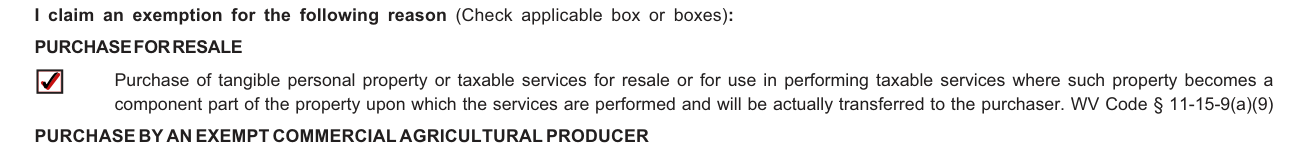
Check the box for a purchase of tangible personal property or taxable services for resale or for use in performing taxable services where such property becomes a component part of the property upon which the services are performed and will be actually transferred to the purchaser (WV Code § 11-15-9(a)(9)).
Purchase by an exempt commercial agricultural producer
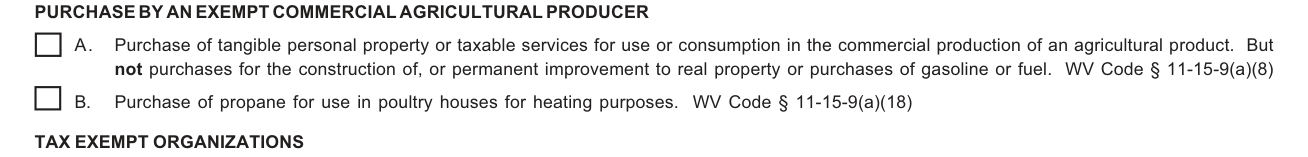
Check A for a purchase of tangible personal property or taxable services for use or consumption in the commercial production of an agricultural product, but not purchases for the construction of, or permanent improvement to real property or purchases of gasoline or fuel (WV Code § 11-15-9(a)(8)).
Check B for a purchase of propane for use in poultry houses for heating purposes (WV Code § 11-15-9(a)(18)).
Tax exempt organizations
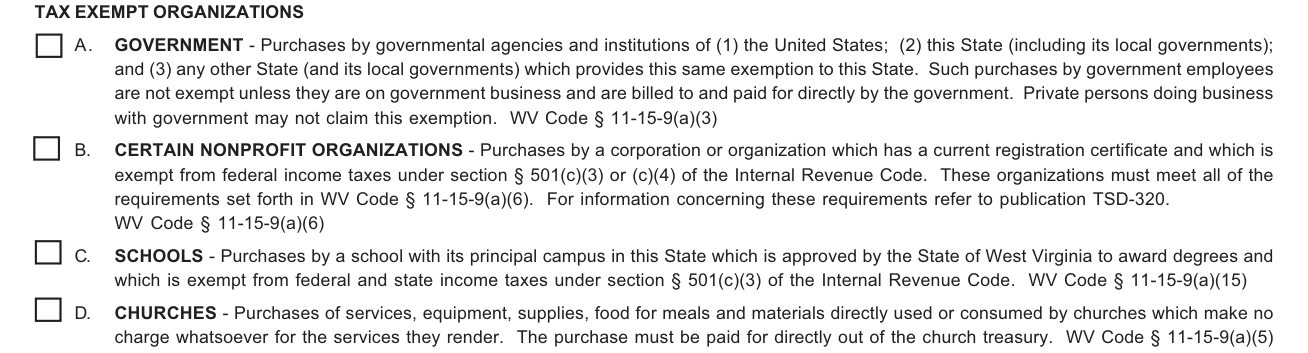
Check A. GOVERNMENT for purchases by governmental agencies and institutions of (1) the United States; (2) this State (including its local governments); and (3) any other State (and its local governments) which provides this same exemption to this State. Such purchases by government employees are not exempt unless they are on government business and are billed to and paid for directly by the government. Private persons doing business with government may not claim this exemption (WV Code § 11-15-9(a)(3)).
Check B. CERTAIN NONPROFIT ORGANIZATIONS: these organizations must meet all of the requirements set forth in WV Code § 11-15-9(a)(6); for information concerning these requirements refer to publication TSD-320. The purchases are by a corporation or organization which has a current registration certificate and which is exempt from federal income taxes under section 501(c)(3) or (c)(4) of the Internal Revenue Code.
Check C. SCHOOLS (WV Code § 11-15-9(a)(15)): purchases by a school with its principal campus in this State which is approved by the State of West Virginia to award degrees and which is exempt from federal and state income taxes under section 501(c)(3) of the Internal Revenue Code.
Check D. CHURCHES for purchases of services, equipment, supplies, food for meals and materials directly used or consumed by churches which make no charge whatsoever for the services they render. The purchase must be paid for directly out of the church treasury (WV Code § 11-15-9(a)(5)).
Purchases of certain specific services and tangible personal property
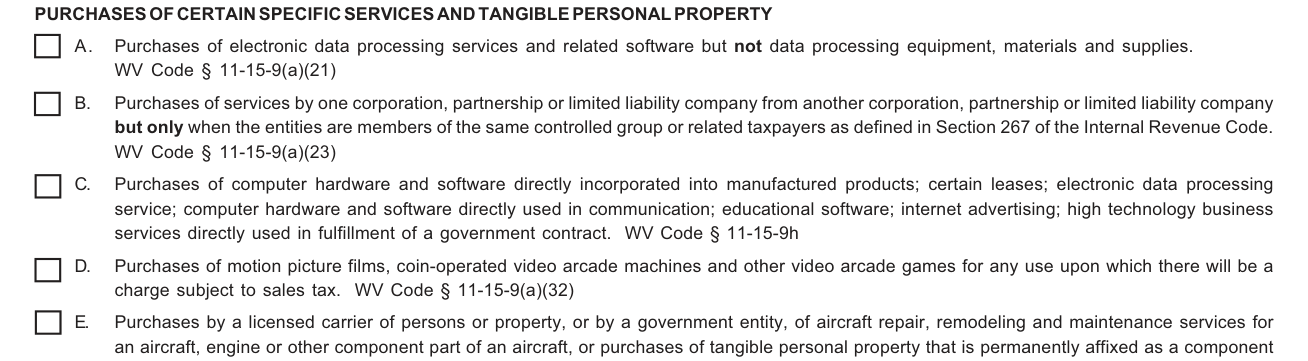
Check A for purchases of electronic data processing services and related software but not data processing equipment, materials and supplies (WV Code § 11-15-9(a)(21)).
Check B for purchases of services by one corporation, partnership or limited liability company from another corporation, partnership or limited liability company. This is only when the entities are members of the same controlled group or related taxpayers as defined in Section 267 of the Internal Revenue Code (WV Code § 11-15-9(a)(23)).
Check C for purchases of computer hardware and software directly incorporated into manufactured products; certain leases; electronic data processing service; computer hardware and software directly used in communication; educational software; internet advertising; high technology business services directly used in fulfillment of a government contract (WV Code § 11-15-9h).
Check D for purchases of motion picture films, coin-operated video arcade machines and other video arcade games for any use upon which there will be a charge subject to sales tax (WV Code § 11-15-9(a)(32)).
Name of purchaser, title and signature
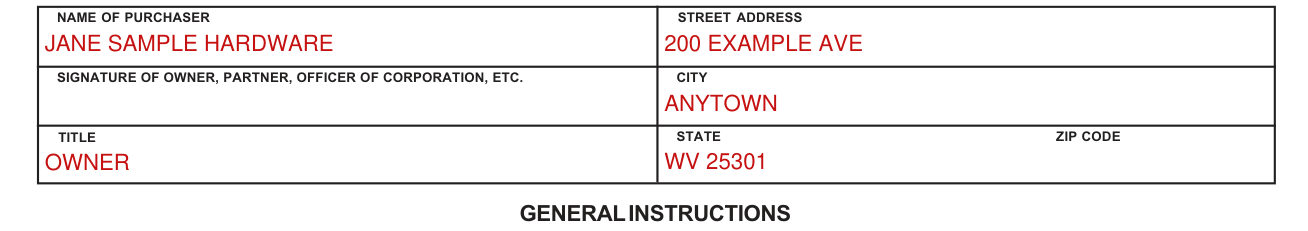
The reverse side of the exemption certificate must be completed to be considered valid.
Enter the name of purchaser, street address, city, state zip code and title.
By signing, you understand that this certificate may not be used to make tax free purchases of items or services which are not for an exempt purpose and that you will pay the Consumers Sales or Use Tax on tangible personal property or services purchased pursuant to this certificate and subsequently used or consumed in a taxable manner.
In addition, you understand that you will be liable for the tax due, plus substantial penalties and interest, for any erroneous or false use of this certificate.
To be properly completed, all entries on this Exemption Certificate must be filled in.
More rules for Form WV/CST-280
Check the applicable box or boxes for the reason you claim an exemption.
If your situation is different
You use a purchase in a non exempt manner or make false or fraudulent use of this certificate
When property or services are purchased tax exempt with an Exemption Certificate, but later used or consumed in a non exempt manner, the purchaser must pay Sales or Use Tax on the purchase price.
Your Business Registration Certificate (and any duplicates) may be suspended or revoked if you or someone acting on your behalf willfully issues this certificate for the purpose of making a tax exempt purchase of tangible personal property and/or services that is not used in a tax exempt manner (as stated on the front of this form).
In the event you make false or fraudulent use of this Certificate with intent to evade the tax, you may be assessed for the tax at any time subsequent to such use.
Common questions about Form WV/CST-280
Is there a penalty?
The willful issuance of a false or fraudulent Exemption Certificate with the intent to evade Sales or Use Tax is a misdemeanor. Your misuse of this Certificate with intent to evade the Sales or Use Tax shall also result in your being subject to a penalty of fifty percent of the tax that would have been due had there not been a misuse of such certificate. This is in addition to any other penalty imposed by the Law. If you, as vendor or as a purchaser, engage in any business activity in West Virginia without possessing a valid Business Registration Certificate (and you do not clearly qualify for an exemption), you shall be subject to a penalty in an amount not exceeding $100 for the first day on which such sales or purchases are made, plus an amount not exceeding $100 for each subsequent day on which such sales or purchases are made (checked October 21, 2026).
When is this form not the right one?
An Exemption Certificate may be used only to claim exemption from tax upon a purchase of tangible personal property or services which will be used for an exempt purpose as stated on the front of this form. It cannot be used to purchase gasoline or special fuel.
Sources
[1] West Virginia Consumers Sales and Service Tax and Use Tax Exemption Certificate, WV/CST-280 (Rev. 905), West Virginia Department of Tax and Revenue (the Official source link on this page).
