
Updated:
An ACH authorization form is a bank account holder’s signed payment permission. It lets a business move money to or from that account over the Automated Clearing House network. Use the free template on this page to create, download, print, and sign yours.
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready
An ACH authorization form is a signed document in which a bank account holder allows a named business or person to move money to or from that account by electronic transfer. The ACH authorization is the permission itself, and the form is the paper or online page that holds it.
ACH stands for Automated Clearing House. The Federal Reserve describes it as a nationwide network through which depository institutions send each other batches of electronic credit and debit transfers (Federal Reserve, Automated Clearinghouse Services).
The form connects that network to one person’s account. It names who is paid, which account is used, how much moves, and on what schedule. It also gives both sides written proof of what was agreed.
You will see the same document called an ACH agreement form, an ACH permission form, or a bank account authorization. The title on the page matters less than whether it covers the parts listed below.
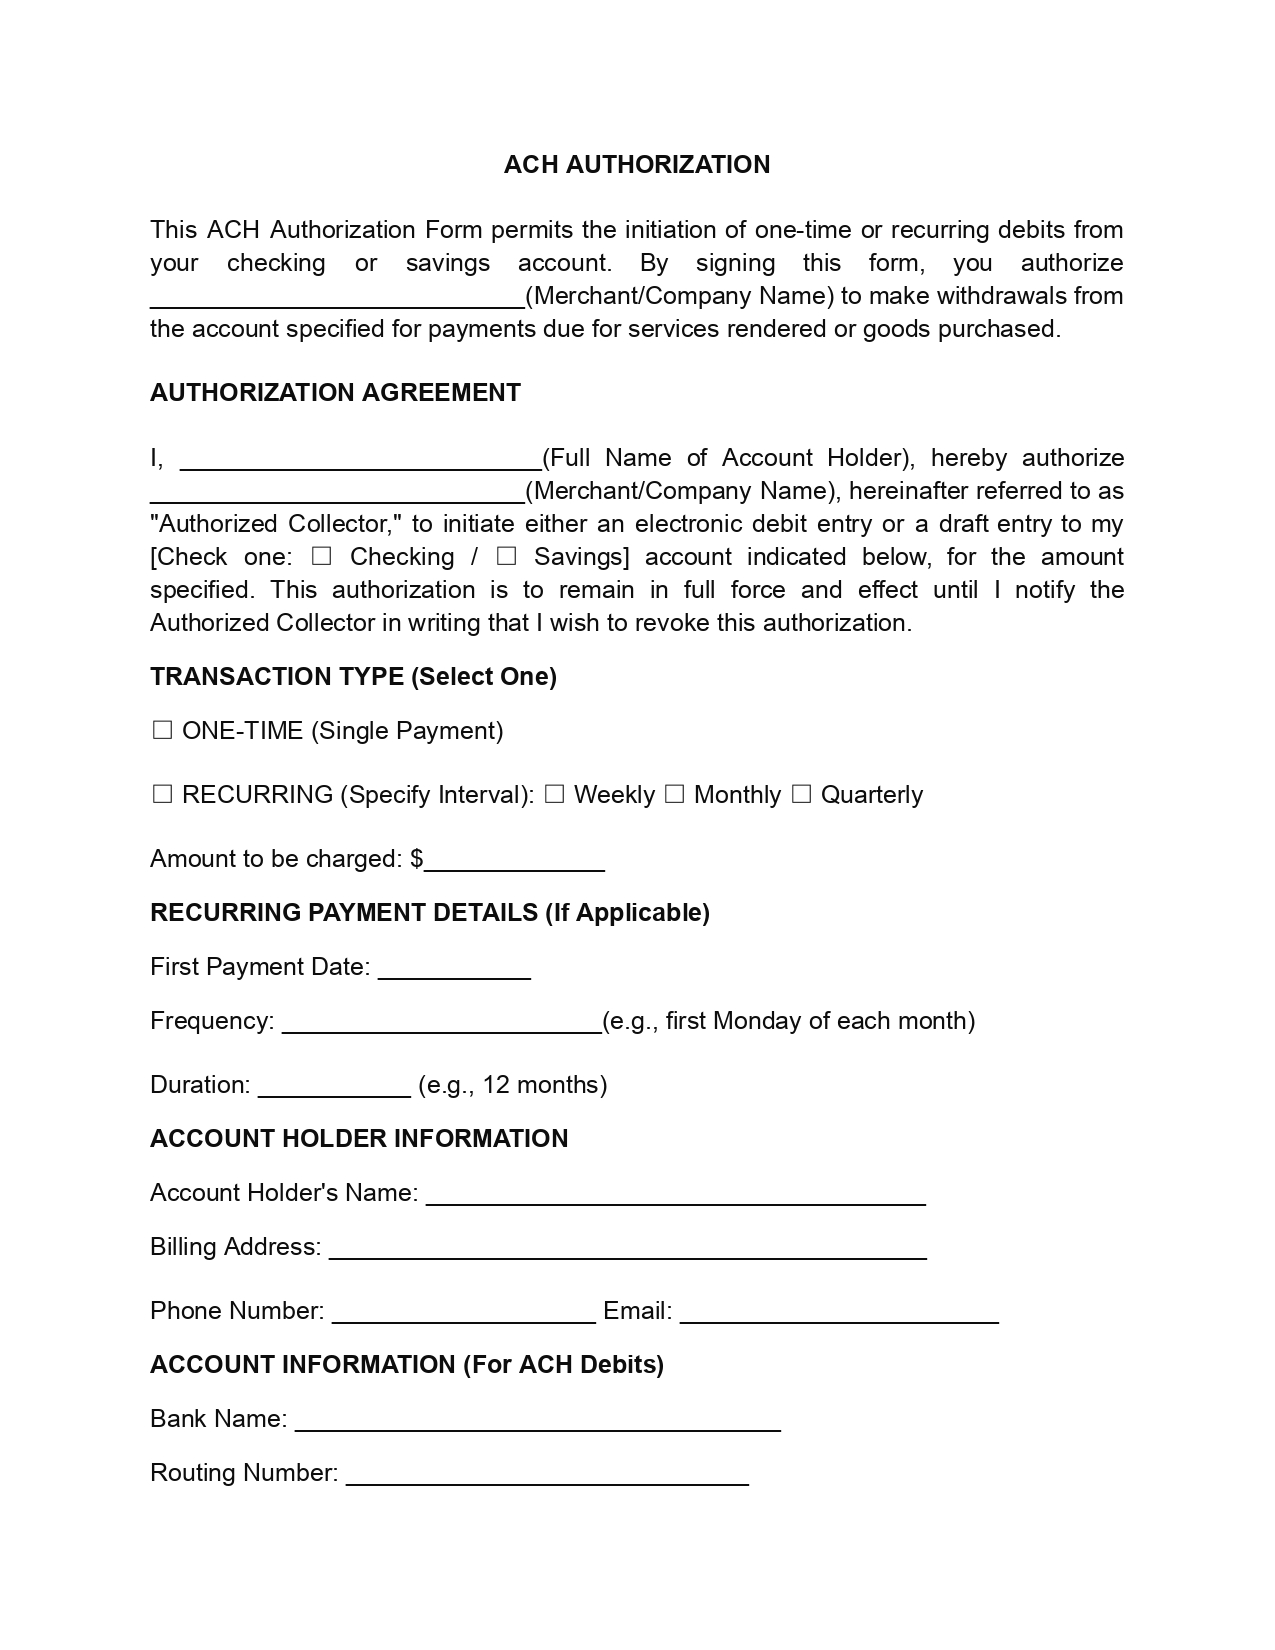
The ACH form template on this page builds your authorization from a few simple questions, so you start with a form that already has every part in place. Click Create My Document to begin. You can save your progress, finish on any device, then download and print it.
A blank template suits a business that collects payments from many customers or pays many vendors. Fill in your company’s details and the purpose once, then leave the bank details and the signature line empty for each person to complete.
The sample below shows how a finished ACH authorization form reads. Every name, number, and date in it is made up.
ACH Debit Authorization (sample)
Account holder: Anna Baker, 123 Main Street, Springfield, (555) 010-0142
Business: Sample Utilities Inc., 45 Market Street, Springfield, (555) 010-0187
Bank: Example Bank. Account type: checking. Routing number: 000000000. Account number: 0001234567.
Payment: $48.00 on the first day of each month, starting March 1, 2027, for utility customer number 77120.
Authorization: I authorize Sample Utilities Inc. to debit my account at Example Bank for the payment above. This authorization stays in place until I cancel it by written notice to Sample Utilities Inc.
Signature: Anna Baker. Date: February 10, 2027.
An ACH authorization form answers who is paying, who is being paid, from which account, how much, how often, and who agreed. The text of 12 CFR 1005.10 prints no list of fields, so treat the list below as a practical checklist and add anything the requesting business or your bank asks for.
Check every number before anyone signs. A wrong digit can send a payment to the wrong account or make it fail, and then the problem takes time to sort out with the bank.
To fill out an ACH authorization form template, work from the top down: enter both parties, the bank details, the amount and schedule, then read the permission sentence, sign, and return the form.
The form carries your bank details, so send it only to the business named on it and only through the channel that business gave you. Once payments begin, compare your next bank statement with the form to confirm the amount and the date.
A business collecting ACH authorization forms fills in its own name, the purpose, and the schedule before sending, and leaves the bank details and signature to the account holder.
Keep signed forms where only the staff who process payments can see them, since each one holds bank details. Tell the account holder before the first payment what will appear on their statement, so the debit is easy to recognize.
An ACH debit authorization lets a business pull money from an account, while an ACH credit authorization lets a sender push money into it. The form looks much the same, and the direction of the money is what changes.
| Type | ACH credit | ACH debit |
|---|---|---|
| Direction of funds | Pushed into a bank account | Pulled from a bank account |
| Typical examples | Direct deposit of payroll, social security benefits, tax refunds | Direct debiting of mortgages and utility bills |
| What the form shows | The recipient’s consent to receive a deposit | The account holder’s permission to withdraw set amounts |
The Federal Reserve names the examples in the table as typical of each kind (Federal Reserve, Automated Clearinghouse Services). Subscriptions and insurance premiums are other common debits.
A debit form deserves the closer read, because money leaves on schedule without a fresh approval each time. On a credit form, the main thing to check is the account number, because that decides where the deposit lands.
Use an ACH authorization form when a business or person needs your standing permission to move money through your bank account by electronic transfer, instead of by check, card, or cash. Common uses include:
A one-time ACH authorization covers a single transfer, while a recurring ACH authorization covers a series of transfers on a set schedule. Under 12 CFR 1005.2, a preauthorized electronic fund transfer is one authorized in advance to recur at substantially regular intervals, so the rules in the next section speak to the recurring kind. The network also handles one-time debits, such as payments made over the telephone and internet (Federal Reserve, Automated Clearinghouse Services).
The rules in the next section cover consumer accounts, because 12 CFR 1005.2 defines an account as a checking, savings, or other consumer asset account established primarily for personal, family, or household purposes. If the account is a business account, ask your bank what its account agreement says about authorizations and stopping payments.
A different document fits when the payment runs on a card and not on a bank account: use a credit card authorization form for that.
The federal rule on recurring transfers from a consumer’s account, 12 CFR 1005.10, part of Regulation E, calls for a writing signed or similarly authenticated by the consumer and a copy for the consumer. The table sets out each rule with its condition.
| Topic | Rule | Source |
|---|---|---|
| Permission | Recurring transfers from a consumer’s account may be authorized only by a writing signed or similarly authenticated by the consumer. | 12 CFR 1005.10(b) |
| Copy | The person that obtains the authorization provides a copy to the consumer. | 12 CFR 1005.10(b) |
| Varying amounts | When a transfer will differ from the previous transfer under the same authorization or from the preauthorized amount, the payee or the bank sends written notice of the amount and date at least 10 days before the scheduled date. | 12 CFR 1005.10(d) |
| Stopping payment | A consumer may stop a recurring transfer by notifying the bank orally or in writing at least three business days before the scheduled date. | 12 CFR 1005.10(c) |
| Loans | No lender may condition credit to a consumer on repayment by recurring transfers, except credit under an overdraft credit plan or credit that maintains a specified minimum balance, and those exceptions do not apply to a covered separate credit feature accessible by a hybrid prepaid-credit card. | 12 CFR 1005.10(e)(1) |
| Jobs and benefits | No one may require a consumer to open an account for receiving electronic transfers at a particular institution as a condition of employment or of receiving a government benefit. | 12 CFR 1005.10(e)(2) |
For the form, 12 CFR 1005.10(b) means a signed page or an authenticated online sign-off, and a copy handed to the account holder. Under 12 CFR 1005.10(b), the words "similarly authenticated" show that a pen signature is not the only route, so follow the instructions you are given for signing online.
If your amount changes from payment to payment, build the notice into your process. Under 12 CFR 1005.10(d), the payee or bank tells the consumer of the right to notice of all varying transfers, and it may offer notice only when a transfer falls outside a specified range or differs from the most recent transfer by more than an agreed amount.
Nacha publishes separate ACH operating rules (Federal Reserve, Automated Clearinghouse Services). This guide does not restate them, so ask your bank how they apply to your payments.
To stop a recurring ACH debit from a consumer account, notify your bank orally or in writing at least three business days before the scheduled transfer date, as 12 CFR 1005.10(c) allows, and tell the business that collects the payment too.
If you call, the bank may ask for written confirmation within 14 days, and under 12 CFR 1005.10(c) it tells you so and gives the address when you call. An oral stop-payment order ceases to be binding after 14 days if you do not send a confirmation the bank asked for (12 CFR 1005.10(c)).
Read the cancellation terms on your form as well, because the notice a business asks for can differ from one agreement to another. Ask the business whether the contract stays open and whether you still owe a balance after the payments stop.
If you decide to stop a payment, these steps help:
Contact both the business and your bank before the next payment date, so there is time to act on your request.
The text of 12 CFR 1005.10 gives no end date for an authorization, so the form itself should say how long it runs. Write an end date on the form, or say that it continues until the account holder cancels it.
A lender cannot condition credit to a consumer on repayment by recurring transfers, with exceptions for an overdraft credit plan and credit that maintains a specified minimum balance, and a limit on those exceptions, under 12 CFR 1005.10(e)(1). You can ask the lender what other ways to pay it accepts.
An employer cannot require you to open an account for receiving electronic transfers at a particular institution as a condition of employment, under 12 CFR 1005.10(e)(2). That section speaks to the choice of institution, so ask your employer about any other pay questions.
Your routing and account numbers are usually printed on your checks, though their place on the check can vary. Ask your bank for the right routing number for electronic transfers if the routing number on a deposit slip differs from the one on your checks, if your checks say they are payable through another institution, or if the account is a savings account without checks.
Yes, one ACH authorization form can cover several payments, because the payment schedule part lets you list a single payment or a repeating schedule, such as monthly.
To start an ACH payment, ask your bank or payment provider how it sets up ACH transfers, then give it the other side’s routing and account numbers. If you will collect money from their account, get their signed authorization first.
An ACH letter to customers says what is changing, why you are asking for bank payment, and when the first payment would run. Enclose the blank authorization form, say how to return it, and name a person to contact with questions.
General information, not legal or tax advice.
