
Updated:
A recurring credit card authorization form is permission for scheduled card charges. The cardholder signs it once, and the business then bills the same card on the agreed schedule. Subscription services, gyms, tutors and service providers use it for monthly or weekly billing.
Key facts
This guide covers what the form includes, how to fill it out and sign it, and how to change or stop the charges later.
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready
The business keeps the form and refers to it for each billing cycle.
A recurring payment is an automatic transaction where a customer authorizes a merchant to charge their credit card for goods or services regularly. The form is the customer's side of that arrangement: it records who agreed, to what amount, how often and for how long.
People search for the same document under several names: recurring payment form, recurring billing authorization, automatic payment authorization and credit card authorization form for recurring payments. The content is the same under each name.
A one-time credit card authorization covers a single charge. A recurring credit card authorization covers repeat charges, which is why it lists a billing schedule and an amount for each charge. A one-time form ends with its single payment, while a recurring form stays in effect until its end date or until the cardholder cancels it.
A card-on-file authorization lets a business store a card and charge it later, often for amounts not known at signing, such as incidentals or usage fees. A recurring authorization is narrower: it ties the stored card to a stated schedule and amount. Some businesses combine both in one form, with a box for each kind of charge.
A bank account authorization asks for the bank's routing number and the account number in place of card details. Many recurring payment forms offer both options, and the customer completes only one.
A debit from a consumer's bank account carries federal rights that a credit card charge does not. A recurring debit card charge also draws on the bank account, so it carries the same rights. Under 12 CFR 1005.10(c), the consumer may stop the debit by telling the bank orally or in writing at least three business days before the scheduled date of the transfer. Under 12 CFR 1005.10(d), when a debit will vary in amount from the previous one or from the authorized amount, the payee or the bank sends written notice of the amount and date at least 10 days before the scheduled date, unless the consumer chose notice only for amounts outside an agreed range.
A recurring credit card authorization fits any service billed on a regular cycle, where the price and the timing are known in advance. Common uses include:
For a business, recurring payments mean steady, predictable income that is easier to plan around. For customers, they remove the need to remember due dates or send each payment by hand.
A single purchase, a deposit or a one-off repair calls for a one-time authorization instead. A charge whose amount changes each month fits a recurring form only when the form states how the amount is set and its maximum.
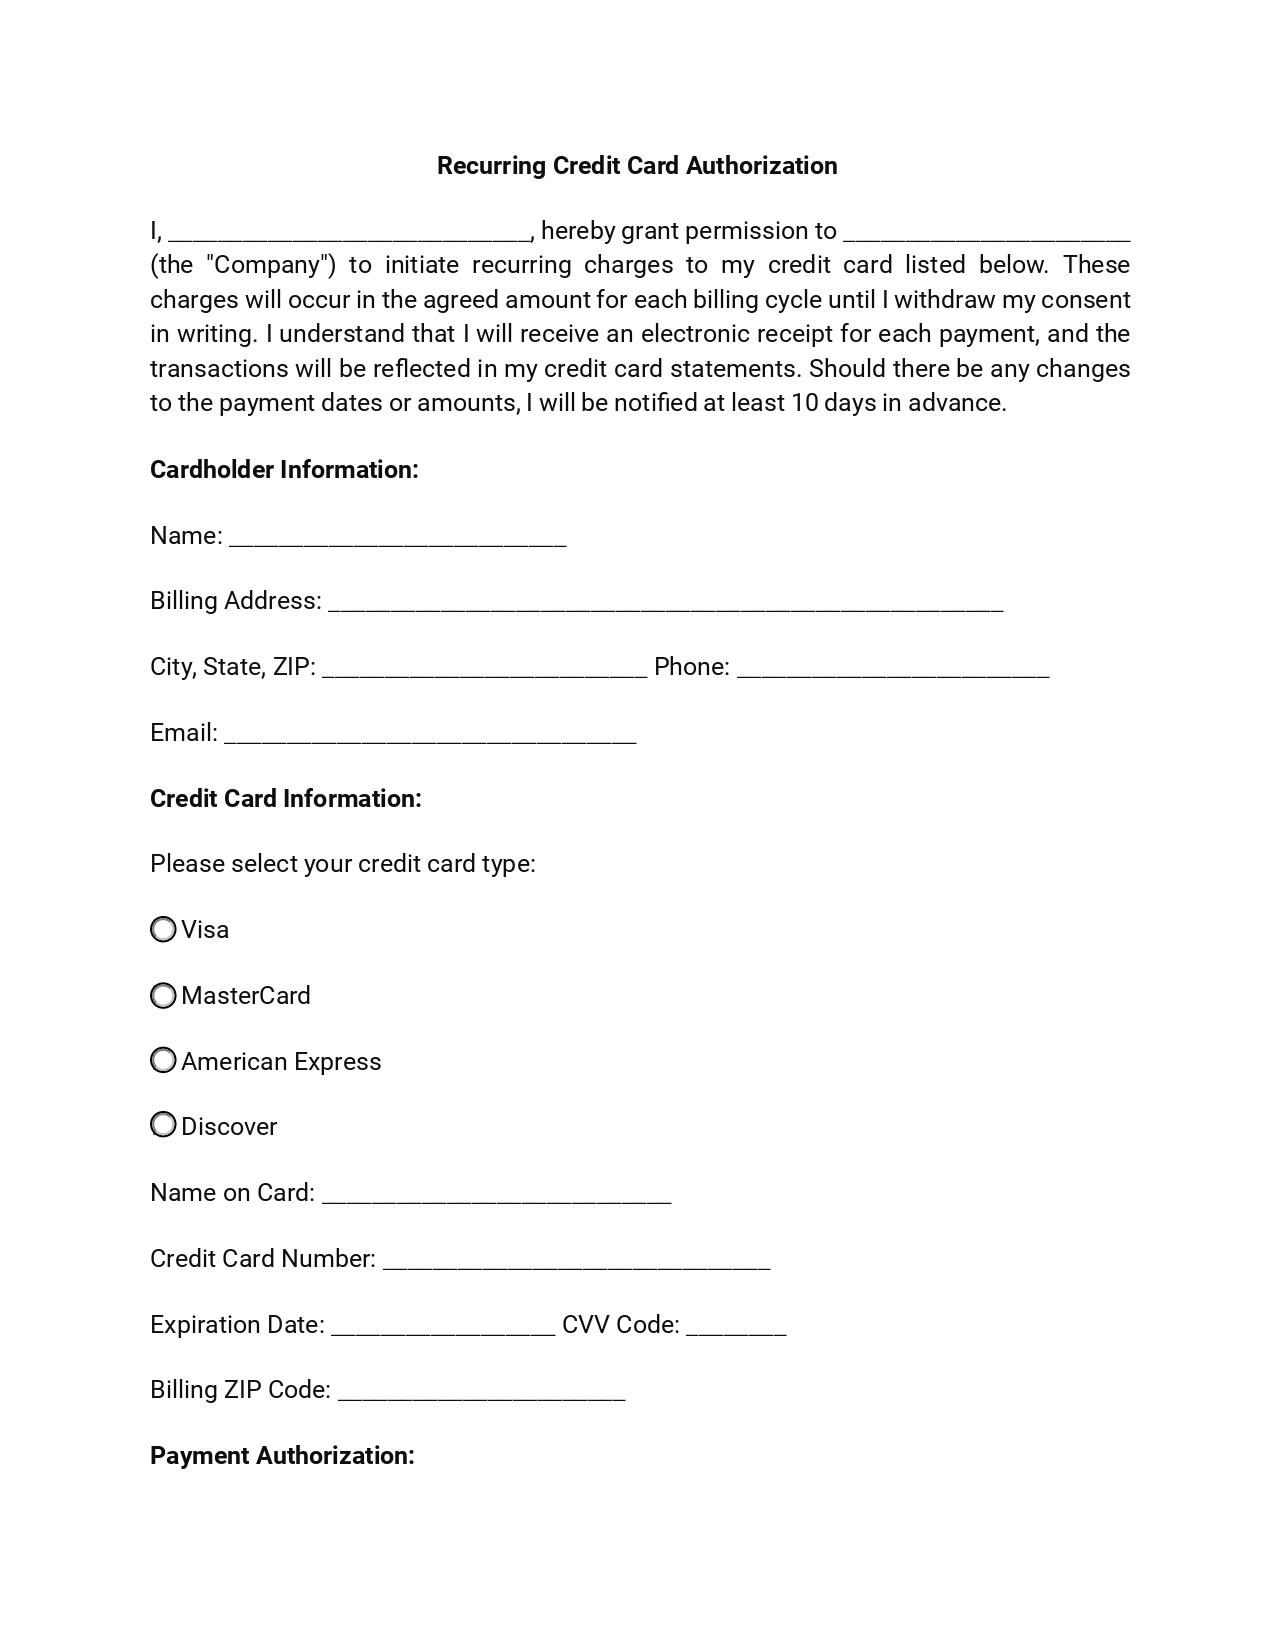
A recurring credit card payment authorization form includes the parties, the payment terms, the card details and the cardholder's signature. Each part answers one question the business or the card issuer may ask later about a charge.
A fixed-amount form names one price that repeats each cycle. A variable-amount form names the basis of the charge, such as the monthly invoice total, and states a maximum per charge. A variable form also says whether the business sends notice before a charge that differs from the last one.
The billing schedule sets how often the card is charged: weekly, every two weeks, monthly, quarterly or yearly. The form also names the day of the cycle, such as the first of each month, and the date of the first charge. A clear first date lets the cardholder check the first charge against the card statement.
The duration clause ends the authorization on a set date, after a set number of payments, or when the cardholder cancels. An open-ended form says "until cancelled" and pairs it with the cancellation terms. A form with an end date stops on that date without further notice from either side.
The authorization statement is the sentence the cardholder signs under: it names the business, the card, the amount and the schedule in one place. The cancellation terms say how the cardholder ends the charges, for example by email or letter, and how much notice the business asks for before the next billing date.
Example authorization statement: I, Jane Doe, authorize Riverside Fitness to charge my Visa card ending in 1234 the amount of $45.00 on the 1st of each month, starting March 1, until I cancel in writing.
A recurring credit card authorization form is filled out by the cardholder, section by section, with the card and the service agreement at hand. The business uses these details for every future payment, so each entry is checked before signing.
Double-check the card number and the expiration date. A wrong digit makes the first payment fail, and the business then contacts you to fill out the form again.
The form takes effect with the cardholder's signature and the date, which confirm consent to the charges it lists. The steps below keep the card details safe on the way to the business.
A review before signing compares the form with your service agreement, line by line. Make sure everything on the page matches what you and the business agreed on.
A recurring payment authorization ends through the cancellation terms written on the form or in the service agreement. Those terms name the way to give notice, such as email, letter or phone, and any notice the business asks for before the next charge.
A bank account (ACH) authorization from a consumer's account can also be stopped through the bank, whatever the form's terms say: under 12 CFR 1005.10(c), the consumer notifies the bank orally or in writing at least three business days before the scheduled date of the transfer.
To change the card, the amount or the schedule, the business usually asks for a new signed form. The new form replaces the old one, so ask the business to confirm that the old authorization is closed.
A charge after cancellation is a matter to raise with your card issuer, using the number on the back of your card. Your card issuer can explain how to dispute the charge and whether a new card number would stop further charges.
Keep all documentation related to the cancellation, including emails, letters, and notes from phone calls (with dates and names of the representatives you spoke with). This documentation can serve as evidence of your attempt to cancel the recurring payment should there be any disputes in the future.
For a business, the signed form is the proof that the cardholder agreed to each charge on the schedule it lists. A charge outside the form's amount, dates or card falls outside that consent.
The card networks and the business's payment processor set their own terms for card-on-file and recurring charges. The merchant agreement with the processor is the place to check those terms.
It lets a business charge your credit card on a regular basis, such as every month. Companies use it for subscriptions, memberships, and routine bills, so the customer does not approve each payment one by one.
The rules for card charges come from the card networks, the business's payment processor and consumer protection laws, which differ from place to place. This page describes the form itself and gives no legal rule; a business with a question about a specific rule can ask its payment processor or a lawyer.
A recurring payment authorization form works the same on paper, as a PDF or through an e-signature service. What matters is the content: the amount, the schedule, the duration, the card details and the cardholder's signature.
The signature on the form belongs to the cardholder. When a parent pays for a child's lessons or a company card pays for a service, the person named on the card signs, and the form can list the customer who uses the service separately.
Keep a signed copy with your billing records and save a digital copy too. Store both somewhere private, since the document lists your card details.
The authorization names one card, so a new expiration date or a new card number means the business needs the new details. Many businesses ask for a new signed form; others accept an update through their secure portal.
General information, not legal or tax advice.
