
Updated:
Get Form Now
IRS Form 4136 is a tax document used to claim a tax credit or refund for federal excise taxes paid on certain fuels used for specific purposes. It is typically filed by taxpayers who use gasoline, diesel fuel, or other taxable fuels for purposes other than powering a motor vehicle on public highways. The form allows taxpayers to recoup some of the excise taxes paid on these fuels when used for qualified purposes, such as farming, aviation, or certain off-highway business uses. Information provided on Form 4136 includes:
By filing Form 4136, taxpayers can claim a credit or refund for the excise taxes paid on eligible fuels, reducing their overall tax liability or obtaining a refund for taxes previously paid. This form helps ensure that taxpayers are not subject to double taxation on fuel used for specific non-highway purposes and provides financial relief for those engaged in qualifying activities that require significant fuel consumption.
Other IRS Forms for Business
Along with the Form 4136, your business might need to prepare plenty of other forms for the IRS. Here are some of the forms businesses most often use.
What it is: Form 4136, Credit for Federal Tax Paid on Fuels: a form to claim a credit for certain nontaxable uses (or sales) of fuel during your income tax year.[2]
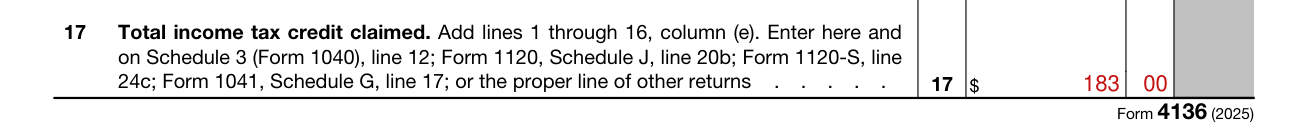
Where and when to file: On line 17, the total income tax credit claimed, add lines 1 through 16, column (e). Enter the total here and on Schedule 3 (Form 1040), line 12; Form 1120, Schedule J, line 20b; Form 1120-S, line 24c; Form 1041, Schedule G, line 17; or the proper line of other returns.
You must have owned or operated a business and conducted a qualifying business activity with qualifying use of qualifying fuels, and meet other requirements to have qualified gallons that are eligible for the credit for federal tax paid on fuels (fuel tax credit) (see instructions for exemption).
Form 4136 can't be used by ultimate vendors to make gasoline claims.[2]
Partnerships (other than electing large partnerships) can't file this form.[2]
A taxpayer who uses gasoline in their vehicle for personal use, commuting to work, or driving for ride sharing services (Uber, Lyft, etc.) does not qualify for the fuel tax credit.[2]
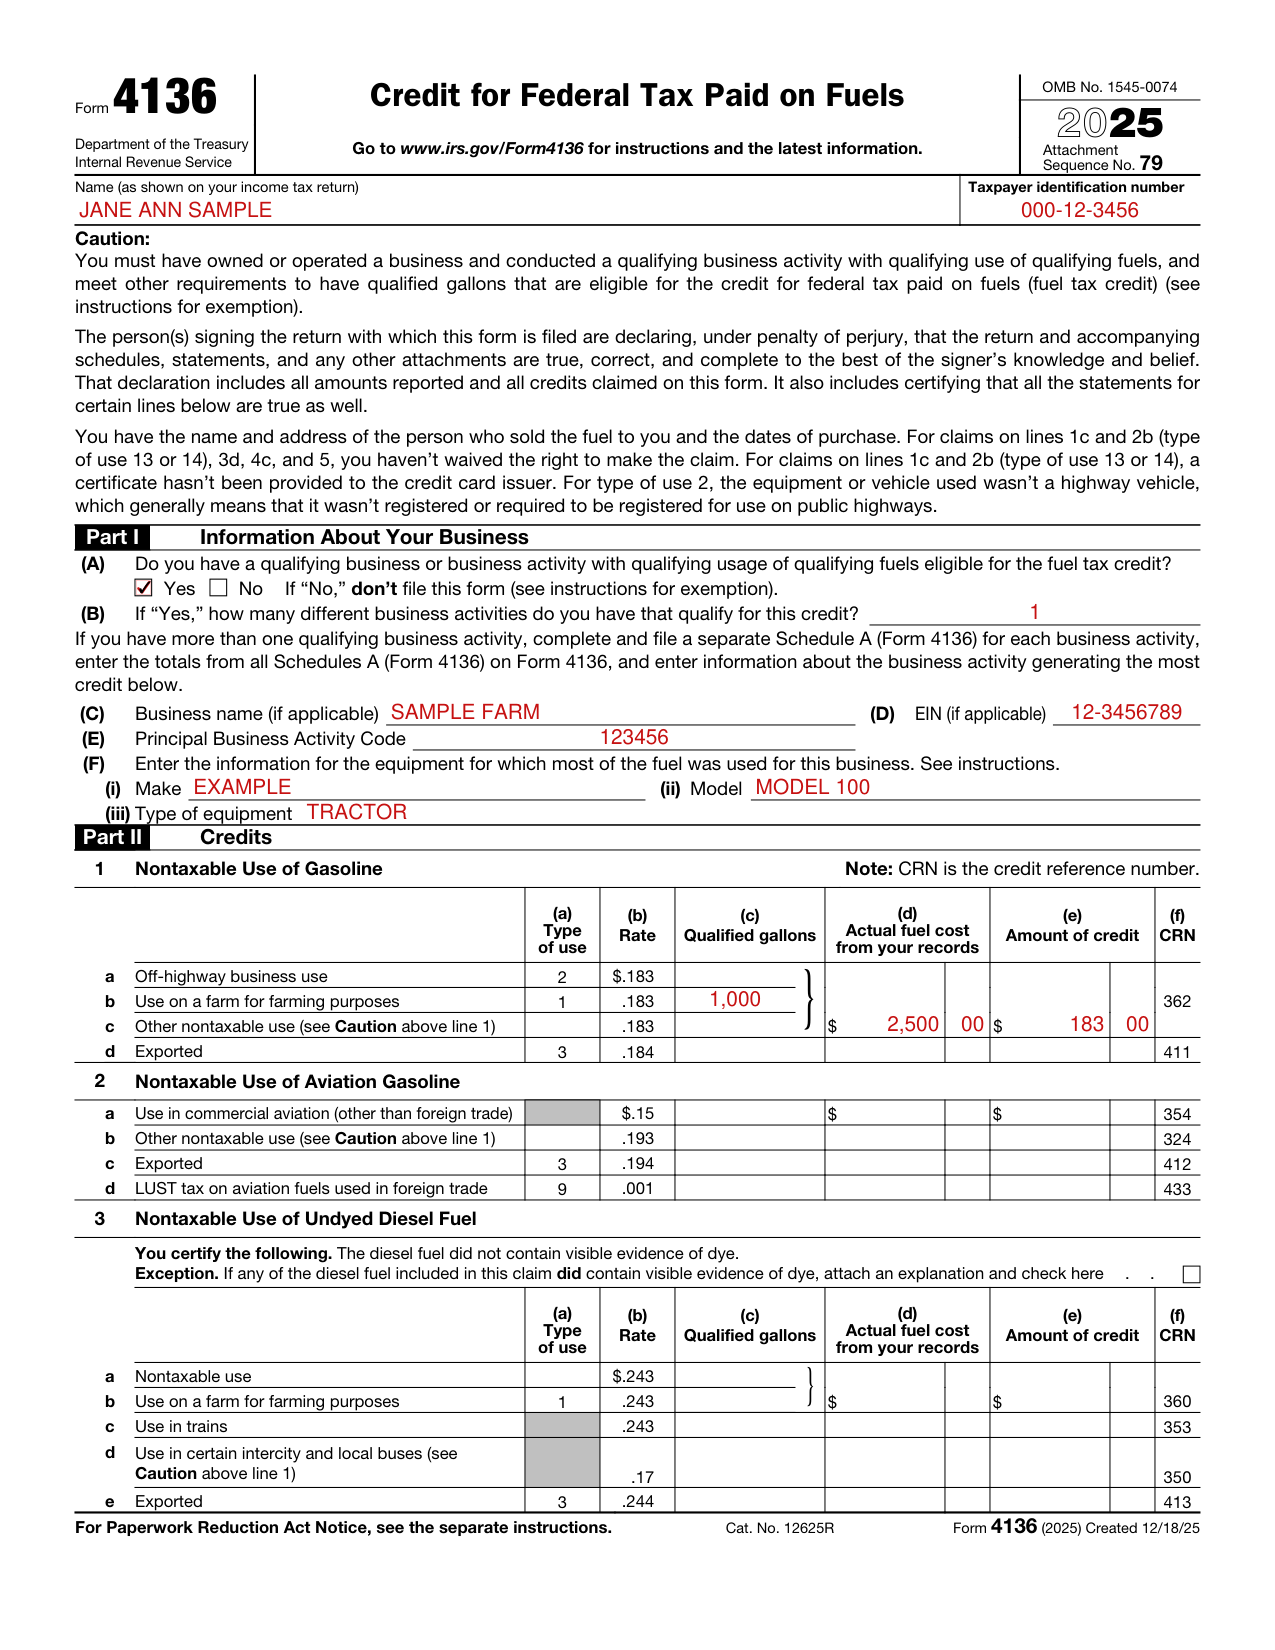
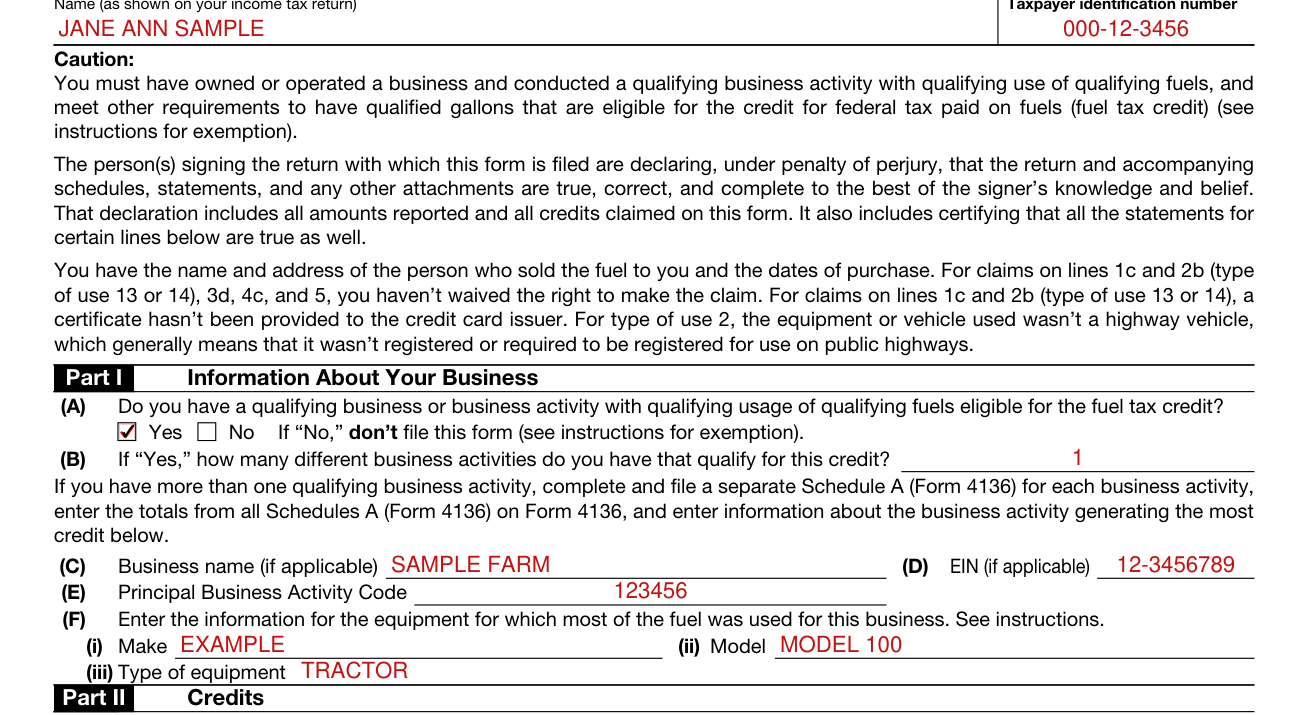
On line A, check Yes or No: do you have a qualifying business or business activity with qualifying usage of qualifying fuels eligible for the fuel tax credit? If "No," don't file this form (see instructions for exemption). On line B, if "Yes," enter how many different business activities you have that qualify for this credit. If you have more than one qualifying business activity, complete and file a separate Schedule A (Form 4136) for each business activity, enter the totals from all Schedules A (Form 4136) on Form 4136, and enter information about the business activity (for example, farming, construction) generating the most credit on Form 4136, Part I, lines (C) through (F).
Exemption: if you are claiming a credit for the tax on undyed kerosene you purchased (other than from a blocked pump) and used in your home during the tax period for heating, lighting, or cooking, answer "Yes" on line A, skip lines B through F, and continue to Part II.
On line D, enter the EIN that was issued to you on Form SS-4. Don't enter your SSN on this line. Don't enter another taxpayer's EIN (for example, from any Forms 1099-MISC that you received). If you don't have an EIN, leave line D blank.
On line E, enter the six-digit principal business activity code.
On line F, describe the make, model, and type of the equipment which used most of the fuel that provided your principal source of income on the business reported on line C.[2]
Complete all information requested for each claim you make. You must enter the number (when requested) from the Type of Use Table, the number of gallons, or gasoline or diesel gallon equivalents (GGE or DGE) (compressed natural gas (CNG), liquefied petroleum gas (LPG), and liquefied natural gas (LNG) only), and the amount of credit.
For the amount of credit, generally multiply the rate by the number of gallons. Enter the result (or the combined result, as indicated by the brackets) in the Amount of credit column.
Enter the actual fuel cost from your records for the credit you claimed in column (d), lines 1 through 16. The amounts in your columns (d) should be a relatively small percentage of your total gross receipts for the activity using the fuel.
The IRS may ask you later for proof, such as receipts of the actual costs you paid for each fuel type. Don't include any receipts or explanation with your tax return. Instead, maintain them with your books and records for your tax return.[2]
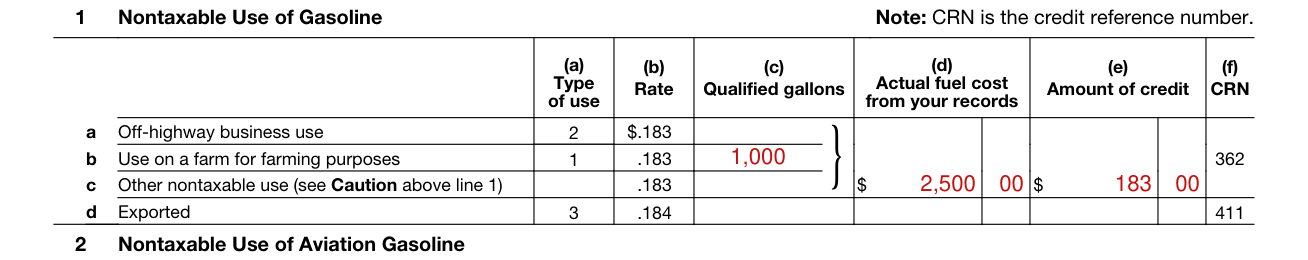
On line 1, Nontaxable Use of Gasoline, the ultimate purchaser of the gasoline is the only person eligible to make this claim.
A claim can't be made for personal use of any fuel on line 1. Also, for lines 1a and 1c, a claim can't be made for any use in a motorboat, other than commercial fishing.
For line 1a, the gasoline must have been used during the period of claim for a business use other than in a highway vehicle registered (or required to be registered) for highway use (type of use 2).
For line 1b, the gasoline must have been used during the period of claim on a farm for farming purposes (type of use 1).
For line 1c, the gasoline must have been used during the income tax year for type of use 4, 5, 7, 11, 13, 14, or 15. For type of use 13 or 14, the claimant must not have waived the right to make a claim.[2]
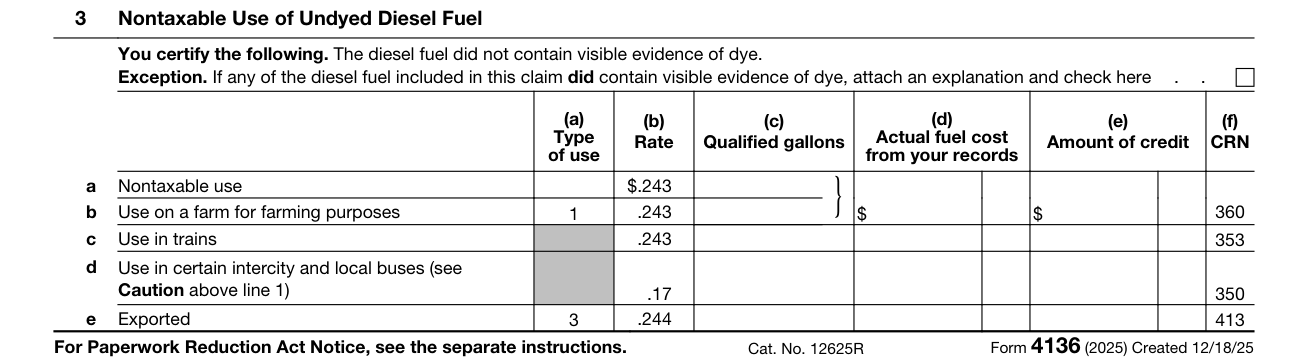
On line 3, Nontaxable Use of Undyed Diesel Fuel, the ultimate purchaser of the diesel fuel is the only person eligible to make this claim.
On line 3, Nontaxable Use of Undyed Diesel Fuel, you certify the following. The diesel fuel did not contain visible evidence of dye. Exception. If any of the diesel fuel included in this claim did contain visible evidence of dye, attach an explanation and check here.
For line 3a, the diesel fuel must have been used during the period of claim for type of use 2, 6, 7, 8, 11, 13, 14, or 15.[2]
The person(s) signing the return with which this form is filed are declaring, under penalty of perjury, that the return and accompanying schedules, statements, and any other attachments are true, correct, and complete to the best of the signer's knowledge and belief.
That declaration includes all amounts reported and all credits claimed on this form.
You must keep records to support any credits claimed on this return for at least 3 years from the date the return is due or filed, whichever is later.[2]
The section 6426/6427 credits/refunds for alternative fuel and alternative fuel mixture credit expired for sales, uses, or removals after 2024.[2]
On line 11, Nontaxable Use of Alternative Fuel, there is a reduced credit rate for use in certain intercity and local buses (type of use 5). Write "Bus" in the space to the left of column (a). Enter the correct claim rate in column (b).[2]
You can't make a claim on lines 6 through 8 if you haven't received your IRS-issued Form 637 registration number and placed it on the applicable lines.[2]
Falsely claiming the fuel tax credit will result in severe consequences, including civil and criminal penalties.[2]
The fuel tax credit does not apply to off-highway business use of gasoline for vehicles used for personal use or commuting to work; non-business, off-highway use (minibikes, snowmobiles, power lawn mowers, chain saws and other yard equipment); and other vehicles that are registered or required to be registered to drive on public highways.[2]
[1] Form 4136 (2025), Credit for Federal Tax Paid on Fuels, Internal Revenue Service (the Official source link on this page).