
Updated:
Get Form Now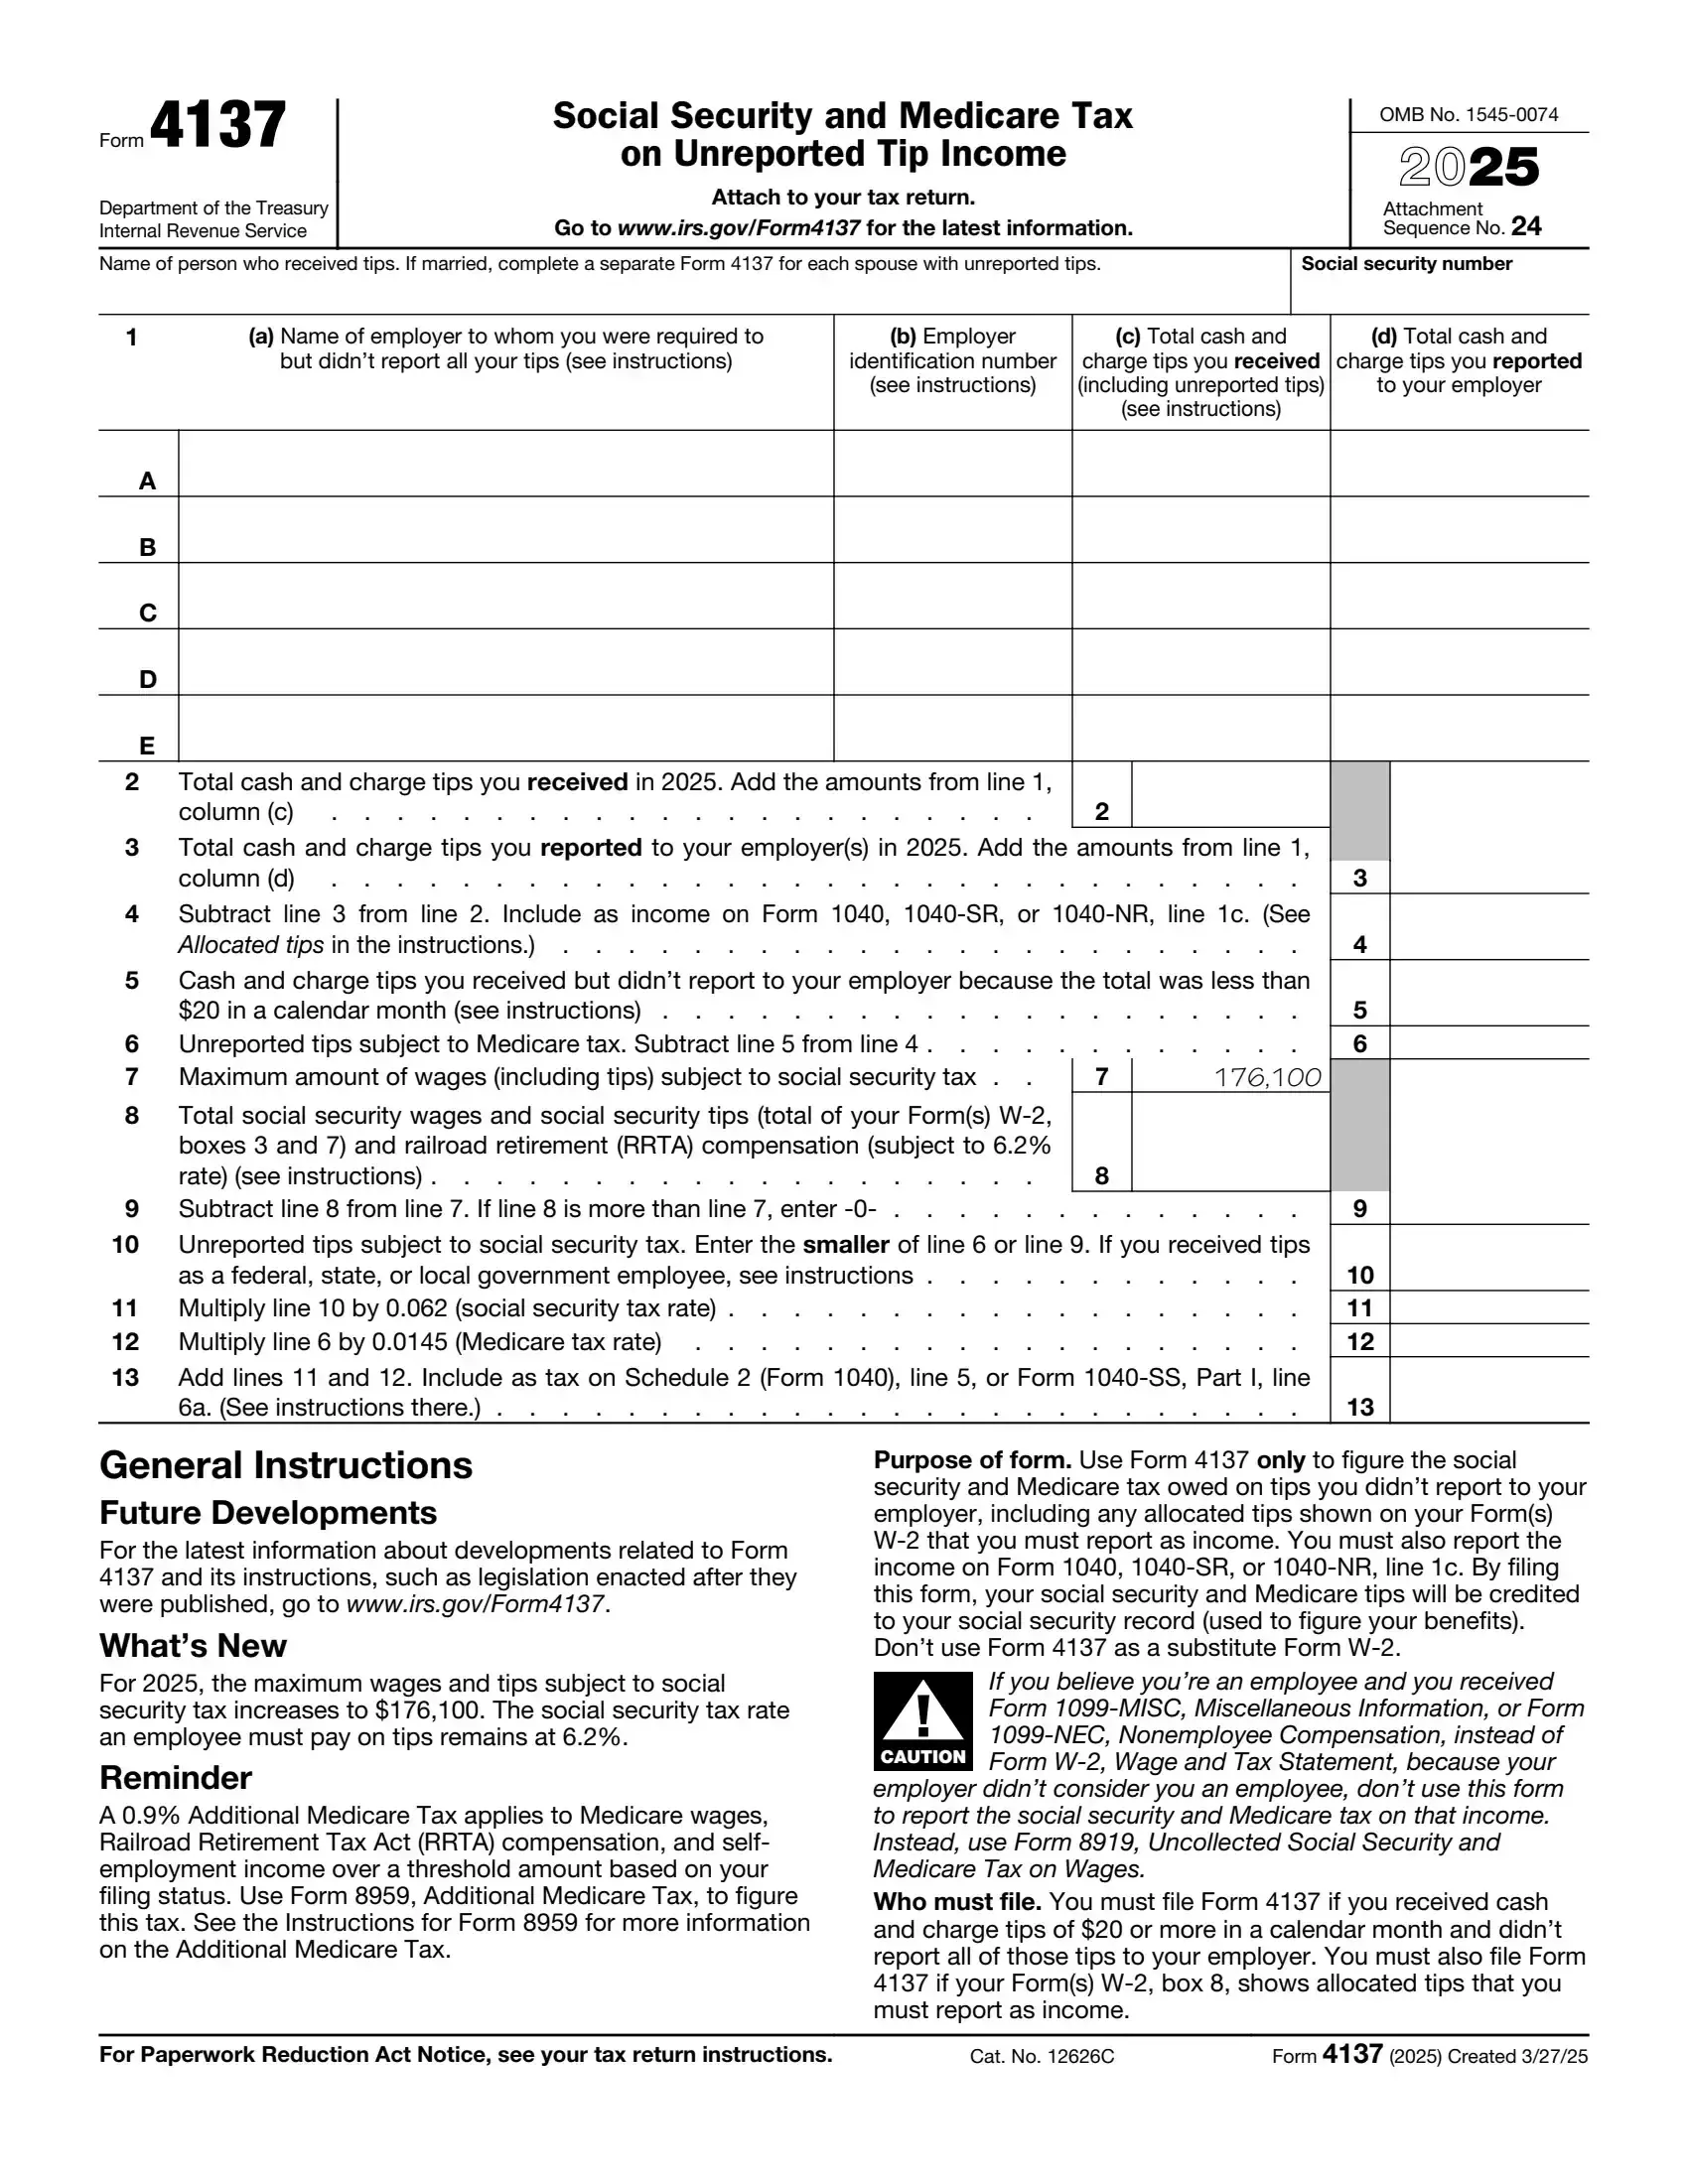
Form 4137, titled “Social Security and Medicare Tax on Unreported Tip Income,” is a tax form used by employees to report and pay their share of Social Security and Medicare taxes on unreported tip income. This form is typically used by food and beverage industry employees who receive tips directly from customers but fail to report them to their employers for tax withholding purposes. Form 4137 allows these employees to calculate and report the Social Security and Medicare taxes owed on their unreported tip income, ensuring compliance with tax laws and regulations.
The primary purpose of Form 4137 is to help employees who receive tip income accurately report and pay their taxes, particularly their share of Social Security and Medicare taxes. By using this form, employees can avoid underreporting their income and potentially facing penalties from the Internal Revenue Service (IRS). Form 4137 provides a structured process for calculating and reporting unreported tip income, helping employees fulfill their tax obligations and maintain compliance with tax laws related to tip reporting.
Other IRS Forms for Individuals
Here, we have plenty of other forms that you might need as an individual taxpayer.
What it is: Form 4137 (2025) is Social Security and Medicare Tax on Unreported Tip Income. Use it only to figure the social security and Medicare tax owed on tips you didn't report to your employer.
Where and when to file: Attach to your tax return.
You must file Form 4137 if you received cash and charge tips of $20 or more in a calendar month and didn't report all of those tips to your employer (checked October 19, 2026).
You must also file Form 4137 if your Form(s) W-2, box 8, shows allocated tips that you must report as income.
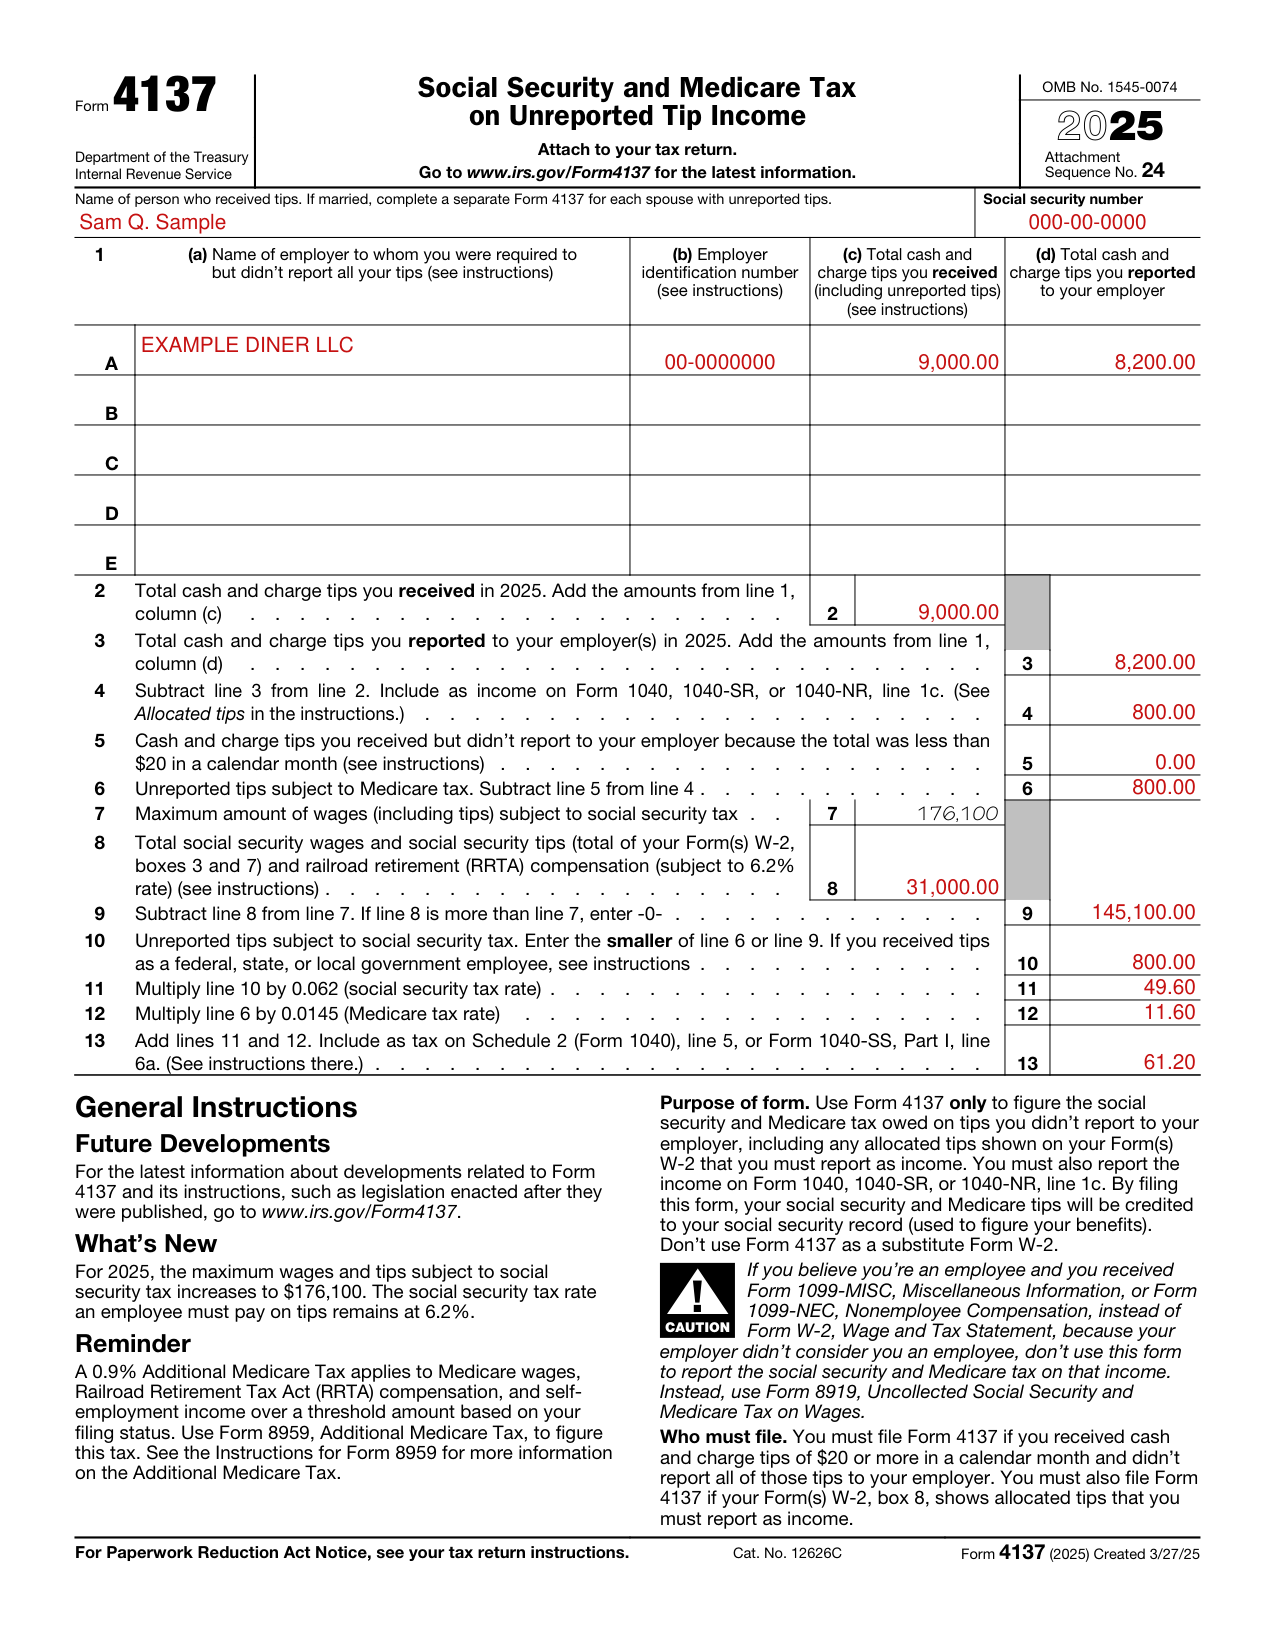
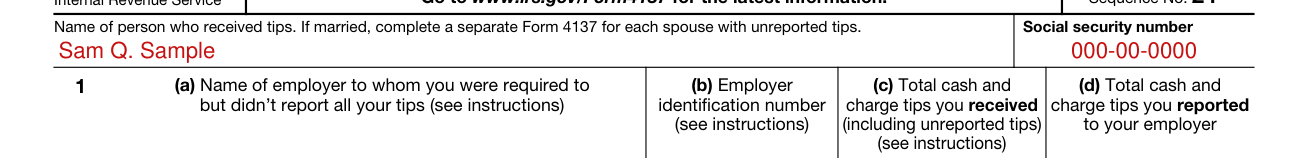
Enter the name of the person who received tips and the social security number.
If married, complete a separate Form 4137 for each spouse with unreported tips.
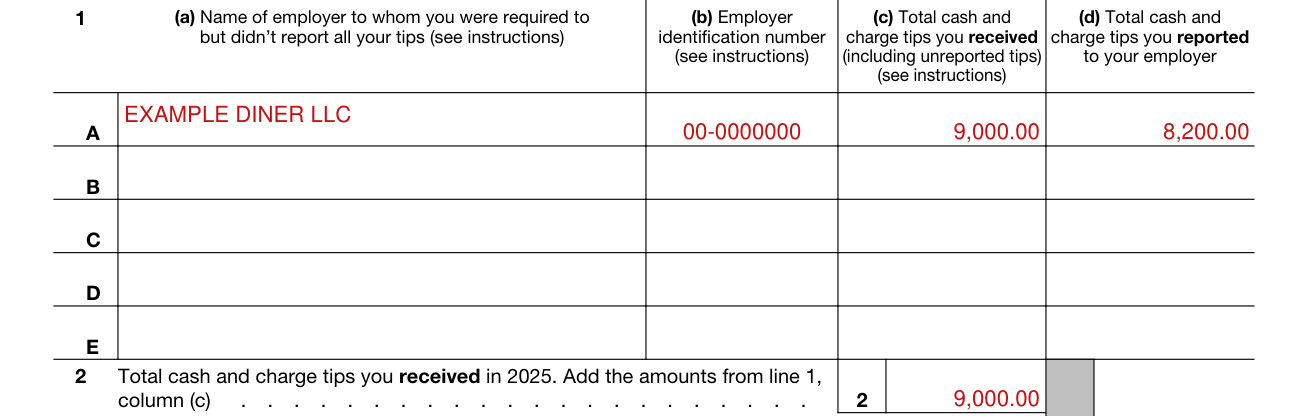
On line 1, complete a separate row for each employer.
Column (a) is the name of the employer to whom you were required to but didn't report all your tips: enter your employer's name exactly as shown on your Form W-2.
In column (b), for each employer you listed, enter the employer identification number (EIN) or the words “Applied For” exactly as shown on your Form W-2.
In column (c), enter the total cash and charge tips you received (including unreported tips). In column (d), enter the total cash and charge tips you reported to your employer. Include all cash and charge tips you received. All of the following tips must be included.
Include in column (c) the tips you didn't report at all, and include any allocated tips shown on your Form(s) W-2, box 8, unless you can prove that your unreported tips are less than the amount in box 8. These tips are considered income to you in the month you actually received them.
Include in column (c) the tips you received that you weren't required to report to your employer because they totaled less than $20 during the month (checked October 19, 2026).
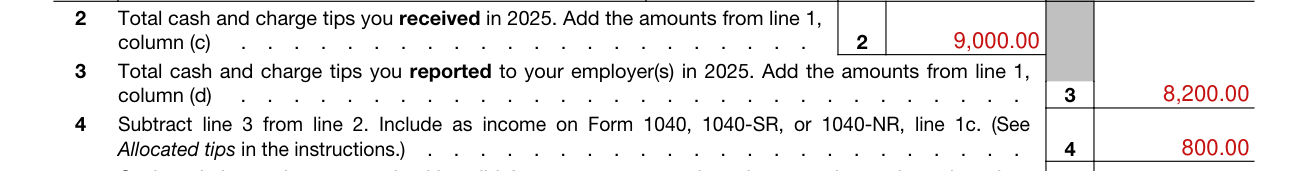
Line 2: total cash and charge tips you received in 2025. Add the amounts from line 1, column (c).
Line 3: total cash and charge tips you reported to your employer(s) in 2025. Add the amounts from line 1, column (d).
Line 4: subtract line 3 from line 2. Include as income on Form 1040, 1040-SR, or 1040-NR, line 1c.

On line 5, enter only the tips you weren't required to report to your employer because the total received was less than $20 in a calendar month (checked October 19, 2026).
These tips aren't subject to social security and Medicare tax.
Line 6: unreported tips subject to Medicare tax. Subtract line 5 from line 4. Enter this amount on Form 8959, line 2, if you're required to file that form.

Line 7 is the maximum amount of wages (including tips) subject to social security tax: 176,100.
Line 8: total social security wages and social security tips (total of your Form(s) W-2, boxes 3 and 7) and railroad retirement (RRTA) compensation (subject to 6.2% rate).
On line 8, for railroad retirement (RRTA) compensation, don't include an amount greater than $176,100, which is the amount subject to the 6.2% rate for 2025 (checked October 19, 2026).
Line 9: subtract line 8 from line 7. If line 8 is more than line 7, enter -0-.
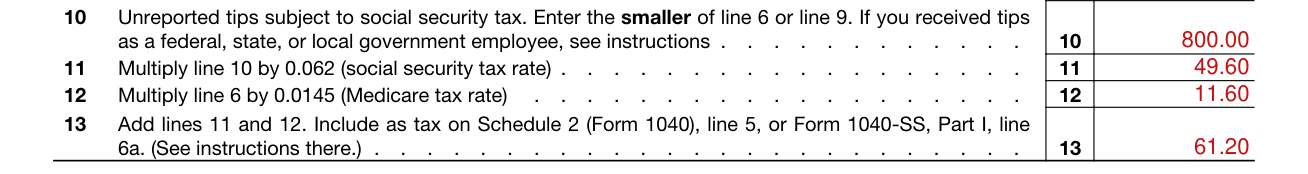
Line 10: unreported tips subject to social security tax. Enter the smaller of line 6 or line 9.
On line 10, if line 6 includes tips you received for work you did as a federal, state, or local government employee and your pay was subject only to the 1.45% Medicare tax, subtract the amount of those tips from the line 6 amount only for the purpose of comparing lines 6 and 9. Don't reduce the actual entry on line 6. Enter “1.45% tips” and the amount you subtracted on the dotted line next to line 10.
Line 11: multiply line 10 by 0.062 (social security tax rate).
Line 12: multiply line 6 by 0.0145 (Medicare tax rate).
Line 13: add lines 11 and 12. Include as tax on Schedule 2 (Form 1040), line 5, or Form 1040-SS, Part I, line 6a.
Don't use Form 4137 as a substitute Form W-2.
You must report your tips to your employer by the 10th day of the month following the month you received them.
If the 10th day of the month falls on a Saturday, Sunday, or legal holiday, give your employer the report by the next business day.
If, in any month, you worked for two or more employers and received tips while working for each, the $20 rule applies separately to the tips you received while working for each employer and not to the total you received (checked October 19, 2026).
Enter on Form 1040, 1040-SR, or 1040-NR, line 1c, only the tips you received in 2025 and didn't report to your employer. This should include any allocated tips shown on your Form(s) W-2, box 8, unless you have adequate records to show that your unreported tips are less than the amount in box 8.
If you believe you're an employee and you received Form 1099-MISC, Miscellaneous Information, or Form 1099-NEC, Nonemployee Compensation, instead of Form W-2, Wage and Tax Statement, because your employer didn't consider you an employee, don't use this form to report the social security and Medicare tax on that income. Instead, use Form 8919, Uncollected Social Security and Medicare Tax on Wages.
Don't use Form 4137 to report tips received for work covered by the Railroad Retirement Tax Act.
To get railroad retirement credit, you must report these tips to your employer.
If you receive $20 or more in cash tips (defined next), you must report 100% of those tips to your employer through a written report (checked October 19, 2026). Cash tips include tips paid by cash, check, debit card, and credit card.
Any tips you reported to your employer in 2025 are included in the wages shown on your Form W-2, box 1. Although allocated tips are shown on your Form W-2, box 8, they aren't included in Form W-2, box 1, and no tax is withheld from these tips.
You must report all your tips from 2025, including both cash tips and noncash tips, as income on Form 1040, 1040-SR, or 1040-NR.
Attach to your tax return.
If you didn't report tips to your employer as required, you may be charged a penalty equal to 50% of the social security, Medicare, and Additional Medicare Taxes due on those tips. You can avoid this penalty if you can show (in a statement attached to your return) that your failure to report tips to your employer was due to reasonable cause and not due to willful neglect.
[1] Form 4137 (2025), Social Security and Medicare Tax on Unreported Tip Income, Internal Revenue Service (the Official source link on this page).