
Updated:
Get Form Now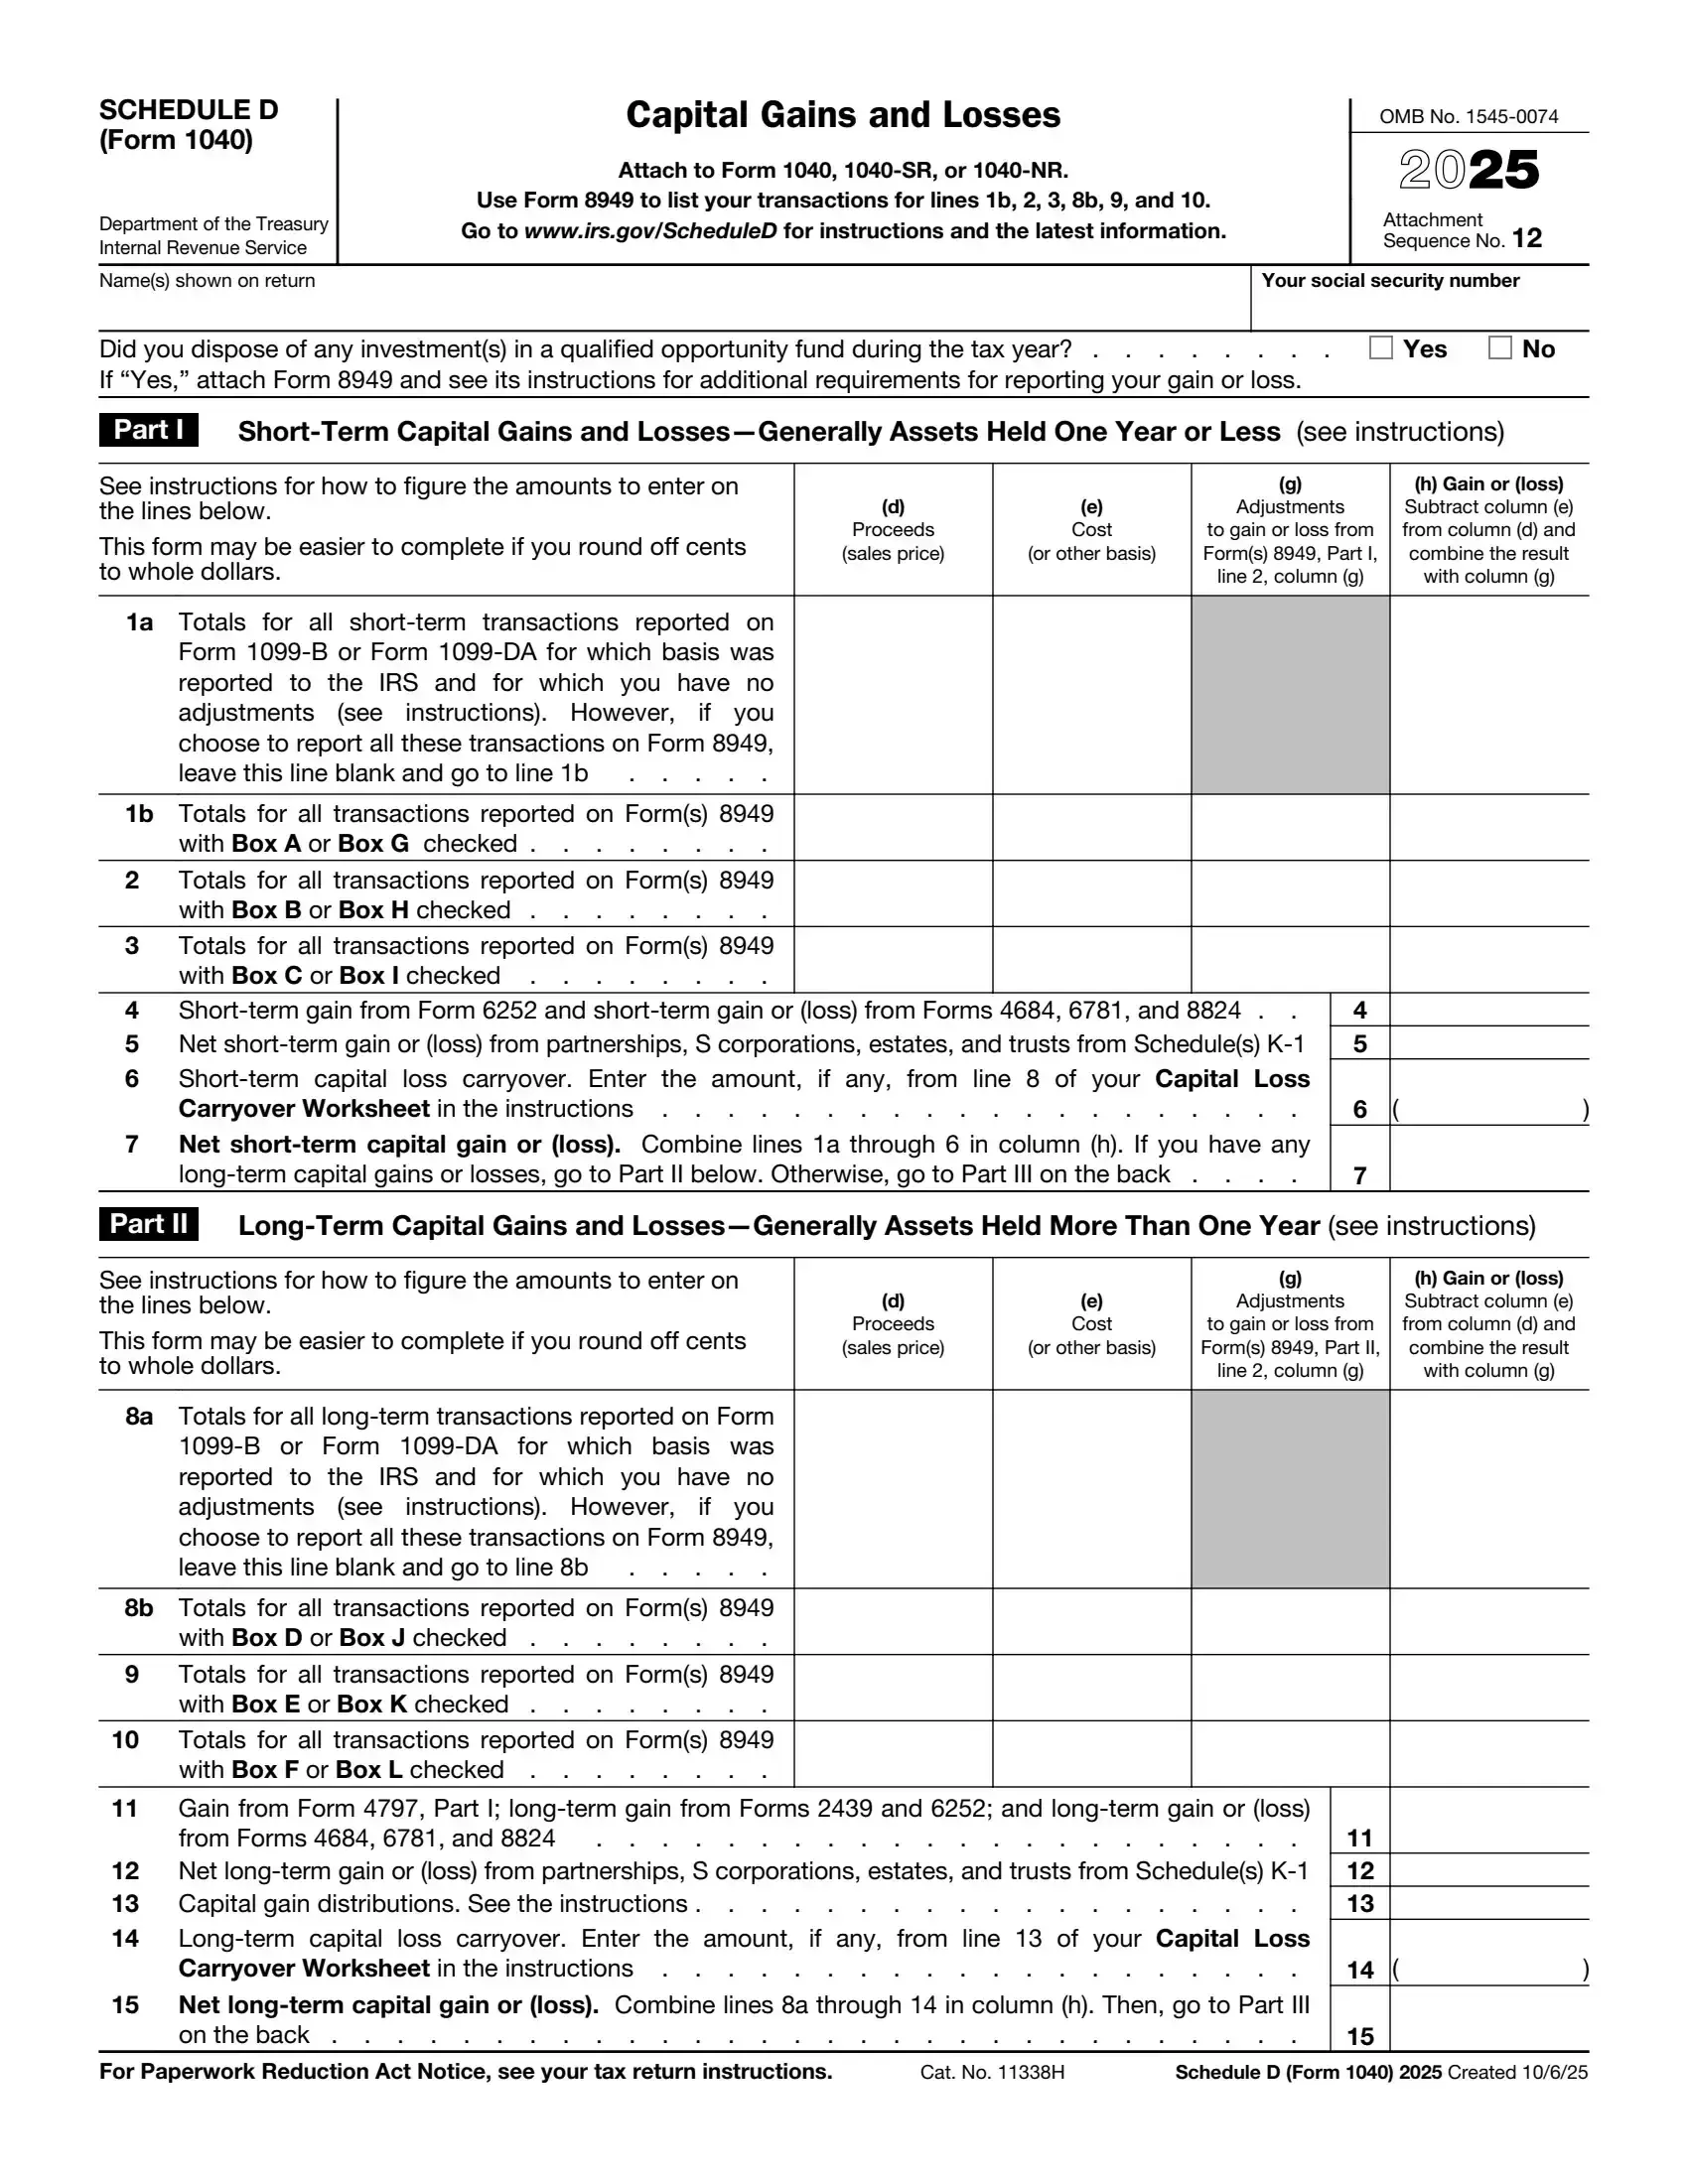
IRS Schedule D (Form 1040 or 1040-SR) is a tax form taxpayers use to report the capital gains and losses resulting from the sale or exchange of capital assets. This includes profits or losses from assets such as stocks, bonds, real estate, and other forms of property. The primary purpose of Schedule D is to calculate the total capital gains tax that may be owed based on these transactions.
Schedule D is divided into sections to differentiate between short-term and long-term capital gains and losses. Short-term capital gains from assets held for one year or less are taxed at the taxpayer’s ordinary income tax rate, whereas long-term gains from assets held for more than a year benefit from lower tax rates. This form also helps taxpayers apply losses against gains to reduce taxable income, with the ability to carry excess losses to future tax years.
Other IRS Forms for Individuals
An individual’s tax return might go with some schedules that contain additional information for the IRS. Read about other schedules and IRS forms that you might need.
What it is: Schedule D (Form 1040) is Capital Gains and Losses.
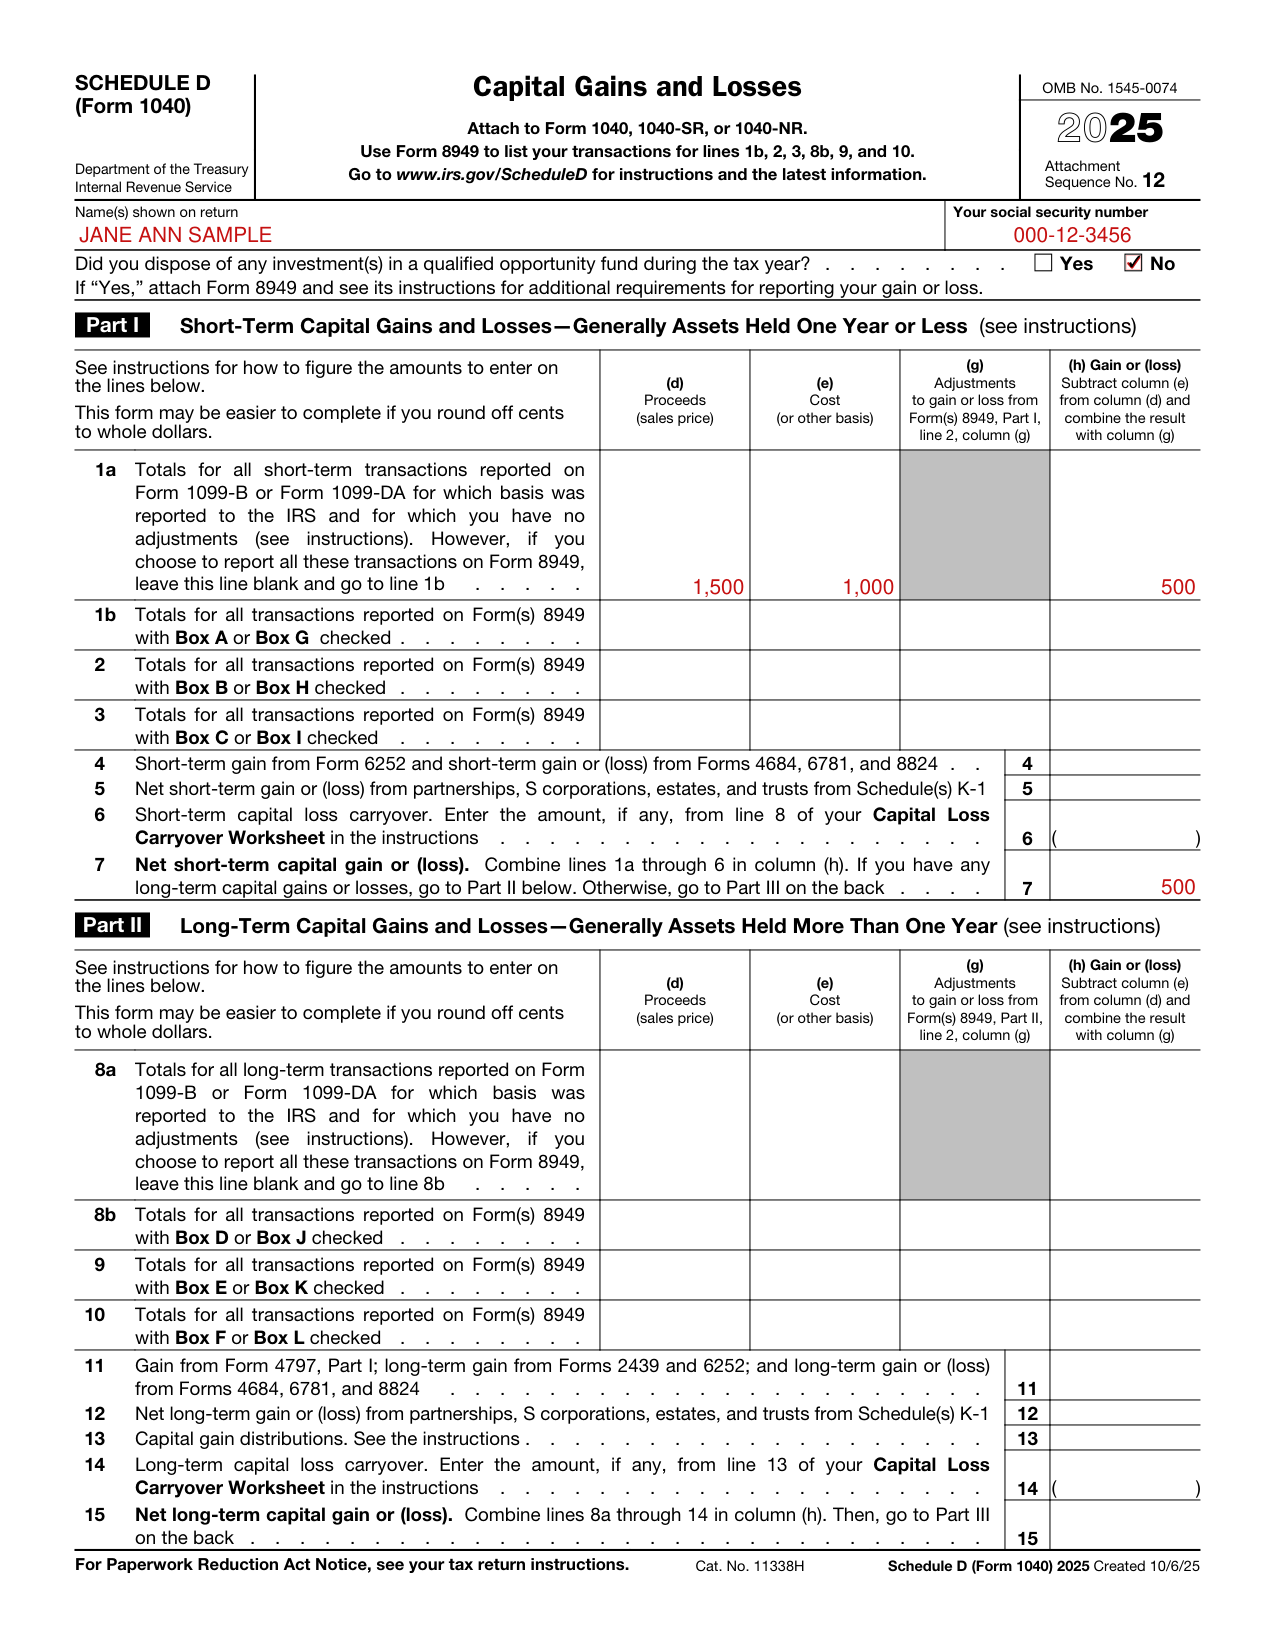

Enter the Name(s) shown on return and Your social security number.
Did you dispose of any investment(s) in a qualified opportunity fund during the tax year? Yes No. If "Yes," attach Form 8949 and see its instructions for additional requirements for reporting your gain or loss.
Use Schedule D to figure the overall gain or loss from transactions reported on Form 8949; to report certain transactions you don't have to report on Form 8949; to report a gain from Form 2439 or 6252 or Part I of Form 4797.[2]
Complete Form 8949 before you complete line 1b, 2, 3, 8b, 9, or 10 of Schedule D.
Attach to Form 1040, 1040-SR, or 1040-NR. Use Form 8949 to list your transactions for lines 1b, 2, 3, 8b, 9, and 10.[2]
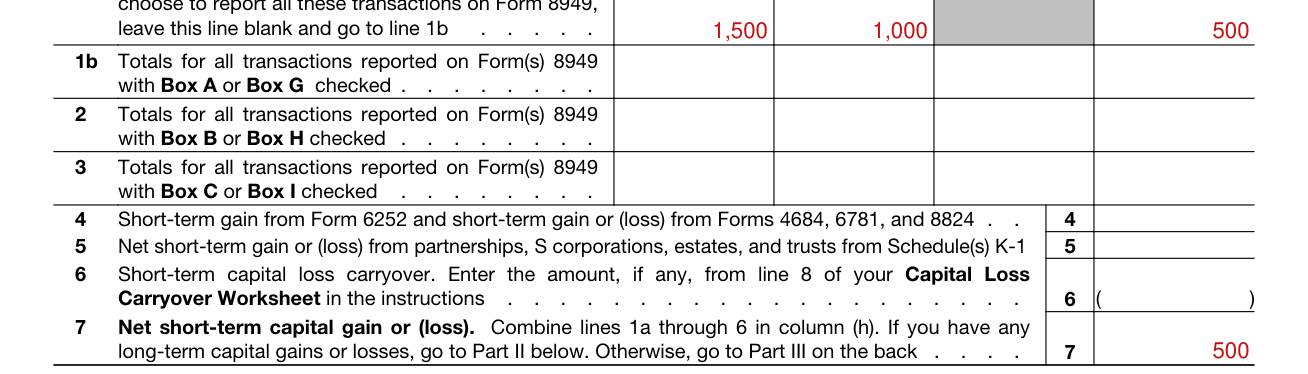
Part I is Short-Term Capital Gains and Losses, Generally Assets Held One Year or Less (see instructions).
Report short-term gains or losses in Part I. Report long-term gains or losses in Part II.
See instructions for how to figure the amounts to enter on the lines of Part I. This form may be easier to complete if you round off cents to whole dollars.
On line 1a, enter totals for all short-term transactions reported on Form 1099-B or Form 1099-DA for which basis was reported to the IRS and for which you have no adjustments (see instructions). However, if you choose to report all these transactions on Form 8949, leave this line blank and go to line 1b.
On line 1b, enter totals for all transactions reported on Form(s) 8949 with Box A or Box G checked. On line 2, enter totals for all transactions reported on Form(s) 8949 with Box B or Box H checked. On line 3, enter totals for all transactions reported on Form(s) 8949 with Box C or Box I checked. On line 4, enter short-term gain from Form 6252 and short-term gain or (loss) from Forms 4684, 6781, and 8824. On line 5, enter net short-term gain or (loss) from partnerships, S corporations, estates, and trusts from Schedule(s) K-1. On line 6, enter the short-term capital loss carryover: the amount, if any, from line 8 of your Capital Loss Carryover Worksheet in the instructions. On line 7, enter the net short-term capital gain or (loss): combine lines 1a through 6 in column (h). If you have any long-term capital gains or losses, go to Part II. Otherwise, go to Part III on the back.[2]
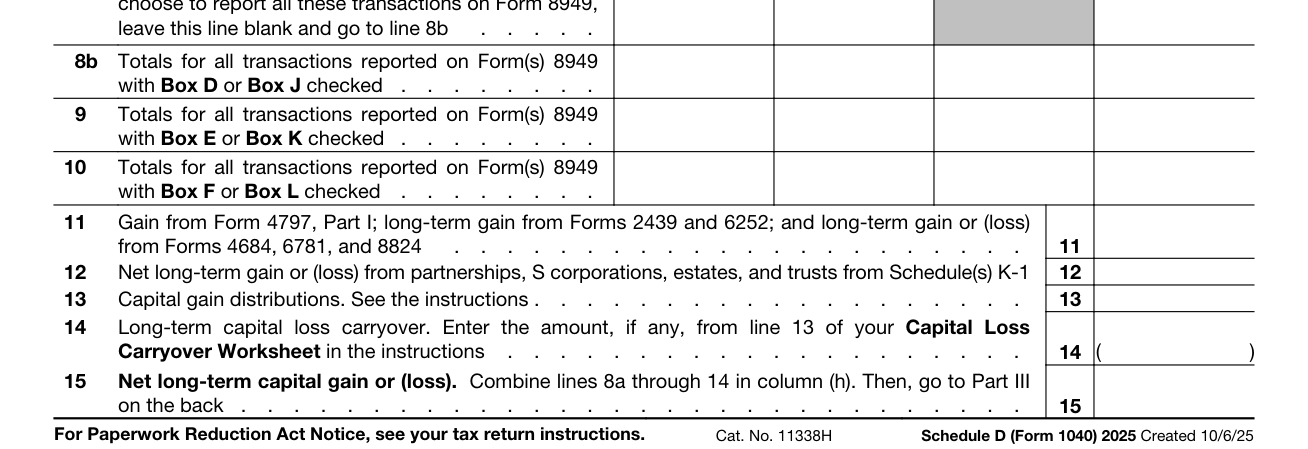
Part II is Long-Term Capital Gains and Losses, Generally Assets Held More Than One Year (see instructions).
On line 8a, enter totals for all long-term transactions reported on Form 1099-B or Form 1099-DA for which basis was reported to the IRS and for which you have no adjustments (see instructions). However, if you choose to report all these transactions on Form 8949, leave this line blank and go to line 8b.
On line 8b, enter totals for all transactions reported on Form(s) 8949 with Box D or Box J checked. On line 9, enter totals for all transactions reported on Form(s) 8949 with Box E or Box K checked. On line 10, enter totals for all transactions reported on Form(s) 8949 with Box F or Box L checked.
On line 11, enter gain from Form 4797, Part I; long-term gain from Forms 2439 and 6252; and long-term gain or (loss) from Forms 4684, 6781, and 8824. On line 12, enter net long-term gain or (loss) from partnerships, S corporations, estates, and trusts from Schedule(s) K-1. On line 13, enter capital gain distributions: see the instructions. On line 14, enter the long-term capital loss carryover: the amount, if any, from line 13 of your Capital Loss Carryover Worksheet in the instructions. On line 15, enter the net long-term capital gain or (loss): combine lines 8a through 14 in column (h). Then, go to Part III on the back.
Enter on Schedule D, line 13, the total capital gain distributions paid to you during the year, regardless of how long you held your investment. This amount is shown in box 2a of Form 1099-DIV.[2]
Part III Summary. On line 16, combine lines 7 and 15 and enter the result.
If line 16 is a gain, enter the amount from line 16 on Form 1040, 1040-SR, or 1040-NR, line 7a. Then, go to line 17.
If line 16 is a loss, skip lines 17 through 20. Then, go to line 21. Also be sure to complete line 22.
If line 16 is zero, skip lines 17 through 21 and enter -0- on Form 1040, 1040-SR, or 1040-NR, line 7a. Then, go to line 22.
Line 17: Are lines 15 and 16 both gains? If Yes, go to line 18. If No, skip lines 18 through 21, and go to line 22.
On line 18, if you are required to complete the 28% Rate Gain Worksheet (see instructions), enter the amount, if any, from line 7 of that worksheet.
On line 19, if you are required to complete the Unrecaptured Section 1250 Gain Worksheet (see instructions), enter the amount, if any, from line 18 of that worksheet.
Line 20: Are lines 18 and 19 both zero or blank and you are not filing Form 4952? If Yes, complete the Qualified Dividends and Capital Gain Tax Worksheet in the instructions for Form 1040, line 16. Don't complete lines 21 and 22. If No, complete the Schedule D Tax Worksheet in the instructions. Don't complete lines 21 and 22.
On line 21, if line 16 is a loss, enter here and on Form 1040, 1040-SR, or 1040-NR, line 7a, the smaller of: the loss on line 16; or ($3,000), or if married filing separately, ($1,500). When figuring which amount is smaller, treat both amounts as positive numbers. (checked November 16, 2026)
Line 22: Do you have qualified dividends on Form 1040, 1040-SR, or 1040-NR, line 3a? If Yes, complete the worksheet in the instructions for Form 1040, line 16. If No, complete the rest of Form 1040, 1040-SR, or 1040-NR.
You may not need to report the sale or exchange of your main home. If you must report it, complete Form 8949 before Schedule D.[2]
Complete the Schedule D Tax Worksheet to figure your tax only if line 18 or line 19 of Schedule D is more than zero and lines 15 and 16 of Schedule D are gains or if you file Form 4952 and you have an amount on line 4g, even if you don't need to file Schedule D. Otherwise, complete the Qualified Dividends and Capital Gain Tax Worksheet in the instructions for Form 1040, line 16 (or in the instructions for Form 1040-NR, line 16) to figure your tax.[2]
You can deduct capital losses up to the amount of your capital gains plus $3,000 ($1,500 if married filing separately). You may be able to use capital losses that exceed this limit in future years. Be sure to report all of your capital gains and losses even if you can't use all of your losses in 2025. (checked November 16, 2026)[2]
[1] Schedule D (Form 1040) 2025, Capital Gains and Losses, Internal Revenue Service (the Official source link on this page).
[2] 2025 Instructions for Schedule D (Form 1040), Capital Gains and Losses, Internal Revenue Service.