

Form 100-WE at a glance
What it is: The 2025 California Water's-Edge Election form, by which the electing corporation elects to file on a water's-edge basis.
Who signs: An officer of the electing corporation must sign and date the election.
The electing corporation elects to file on a water's-edge basis pursuant to California Revenue and Taxation Code (R&TC) Sections 25110 and 25113.
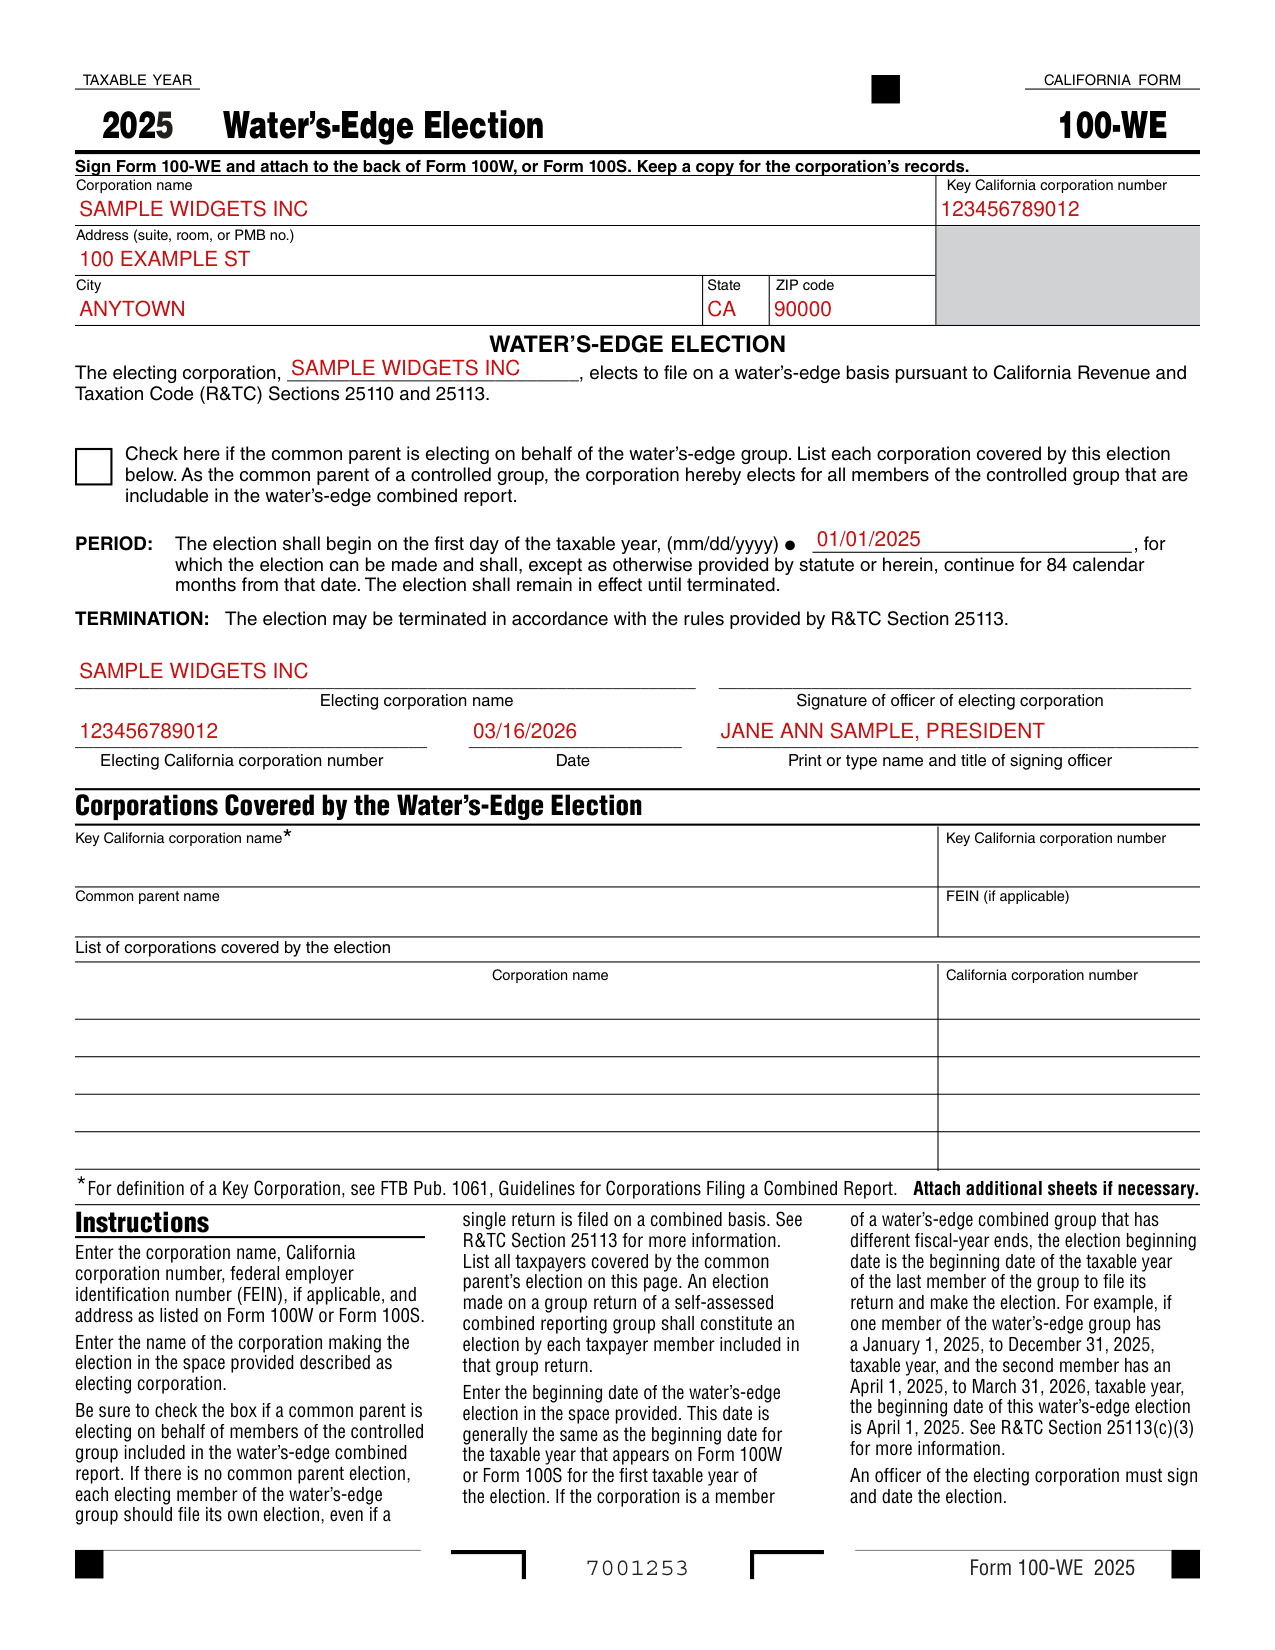
A filled-in Form 100-WE example: a single corporation makes its own election
How to fill out Form 100-WE, box by box
Corporation name, number and address
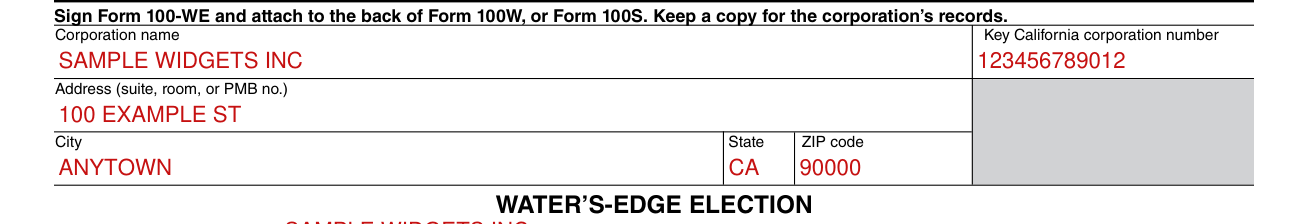
Enter the corporation name, California corporation number, federal employer identification number (FEIN), if applicable, and address as listed on Form 100W or Form 100S.
Enter the Address (suite, room, or PMB no.), City, State and ZIP code.
Sign the form and attach to the back of Form 100W, or Form 100S.
Keep a copy for the corporation's records.
The electing corporation and the election date
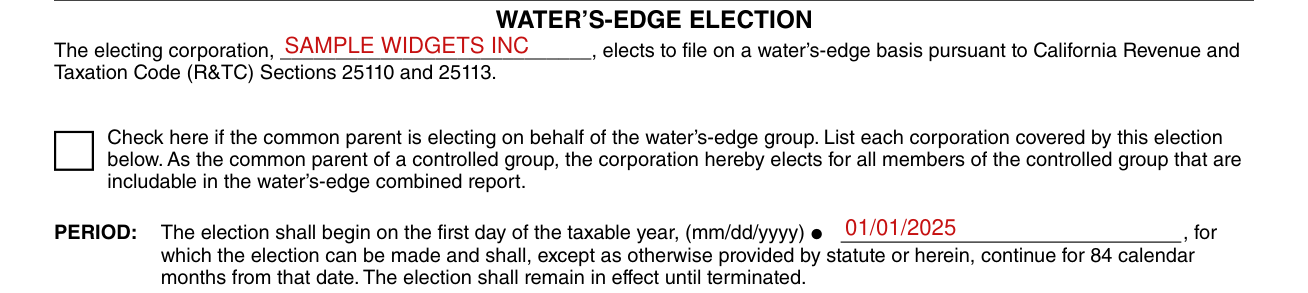
Enter the name of the corporation making the election in the space provided described as electing corporation.
Enter the beginning date of the water's-edge election in the space provided. This date is generally the same as the beginning date for the taxable year that appears on Form 100W or Form 100S for the first taxable year of the election.
The election shall begin on the first day of the taxable year, (mm/dd/yyyy), for which the election can be made and shall, except as otherwise provided by statute or herein, continue for 84 calendar months from that date. The election shall remain in effect until terminated.
Common parent election and corporations covered
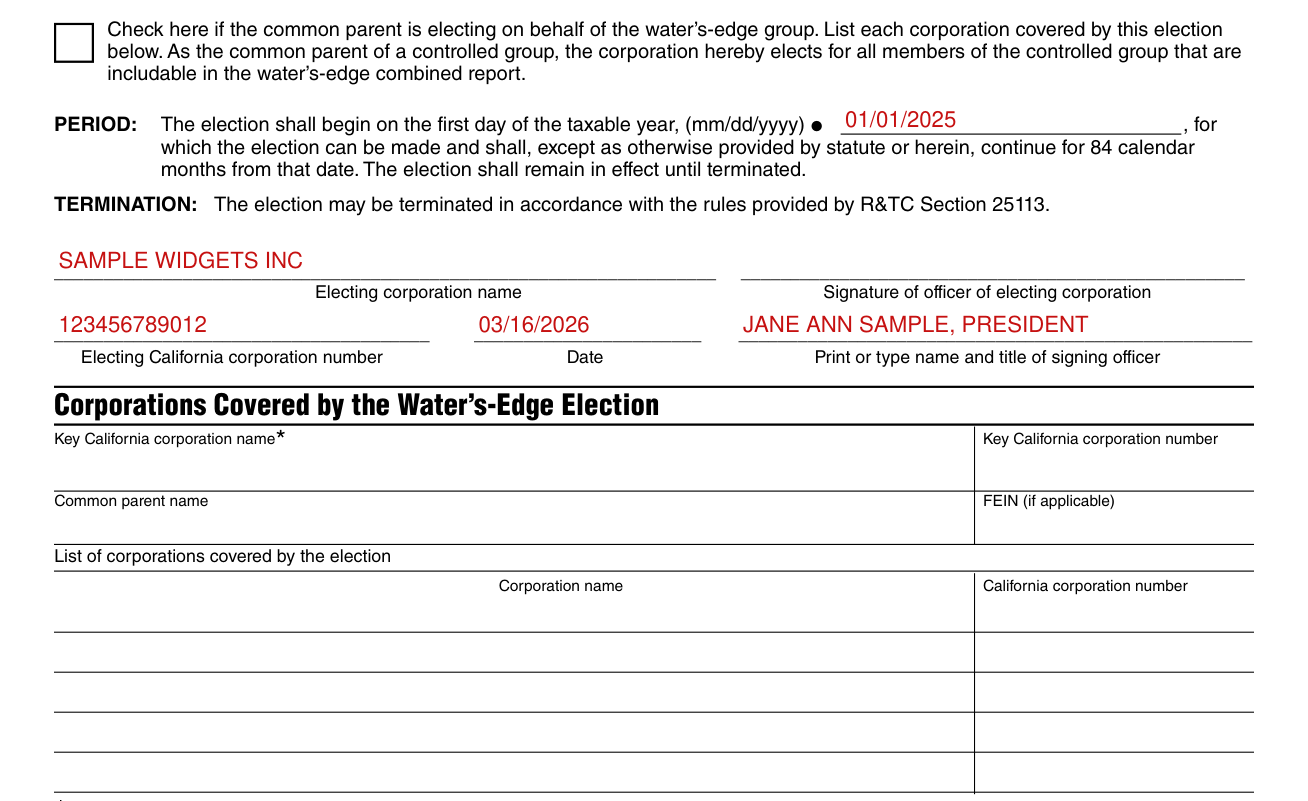
Check here if the common parent is electing on behalf of the water's-edge group. List each corporation covered by this election under List of corporations covered by the election.
Be sure to check the box if a common parent is electing on behalf of members of the controlled group included in the water's-edge combined report.
Enter the Key California corporation name and number, and the Common parent name and FEIN (if applicable).
List all taxpayers covered by the common parent's election in the list of corporations covered by the election.
An election made on a group return of a self-assessed combined reporting group shall constitute an election by each taxpayer member included in that group return.
Attach additional sheets if necessary.
For definition of a Key Corporation (the * on Key California corporation name), see FTB Pub. 1061, Guidelines for Corporations Filing a Combined Report.
Signing the election
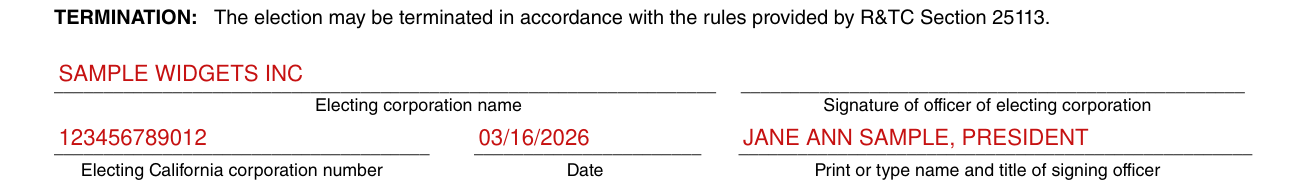
Enter the Electing corporation name, Electing California corporation number and Date, then Print or type name and title of signing officer, and the Signature of officer of electing corporation.
More rules for Form 100-WE
The election may be terminated in accordance with the rules provided by R&TC Section 25113.
Groups and fiscal years
There is no common parent election
If there is no common parent election, each electing member of the water's-edge group should file its own election, even if a single return is filed on a combined basis. See R&TC Section 25113 for more information.
The water's-edge group has different fiscal-year ends
If the corporation is a member of a water's-edge combined group that has different fiscal-year ends, the election beginning date is the beginning date of the taxable year of the last member of the group to file its return and make the election. For example, if one member of the water's-edge group has a January 1, 2025, to December 31, 2025, taxable year, and the second member has an April 1, 2025, to March 31, 2026, taxable year, the beginning date of this water's-edge election is April 1, 2025. See R&TC Section 25113(c)(3) for more information.
Sources
[1] Form 100-WE (2025), Water's-Edge Election, California Franchise Tax Board (the Official source link on this page).