
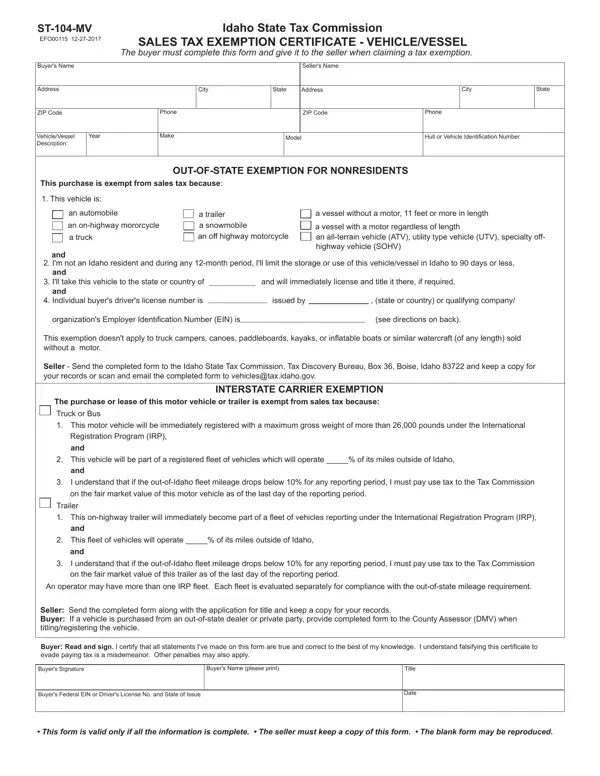
Form ST-104-MV at a glance
What it is: The buyer must complete the Idaho State Tax Commission's Sales Tax Exemption Certificate - Vehicle/Vessel, Form ST-104-MV, and give it to the seller when claiming a tax exemption.
Where and when to file: For the Out-of-State Exemption for Nonresidents, seller - Send the completed form to the Idaho State Tax Commission, Tax Discovery Bureau, Box 36, Boise, Idaho 83722 and keep a copy for your records or scan and email the completed form to vehicles@tax.idaho.gov. For the Interstate Carrier Exemption, seller: Send the completed form along with the application for title and keep a copy for your records. Buyer: If a vehicle is purchased from an out-of-state dealer or private party, provide completed form to the County Assessor (DMV) when titling/registering the vehicle.
A filled-in Form ST-104-MV example: a nonresident buys an automobile
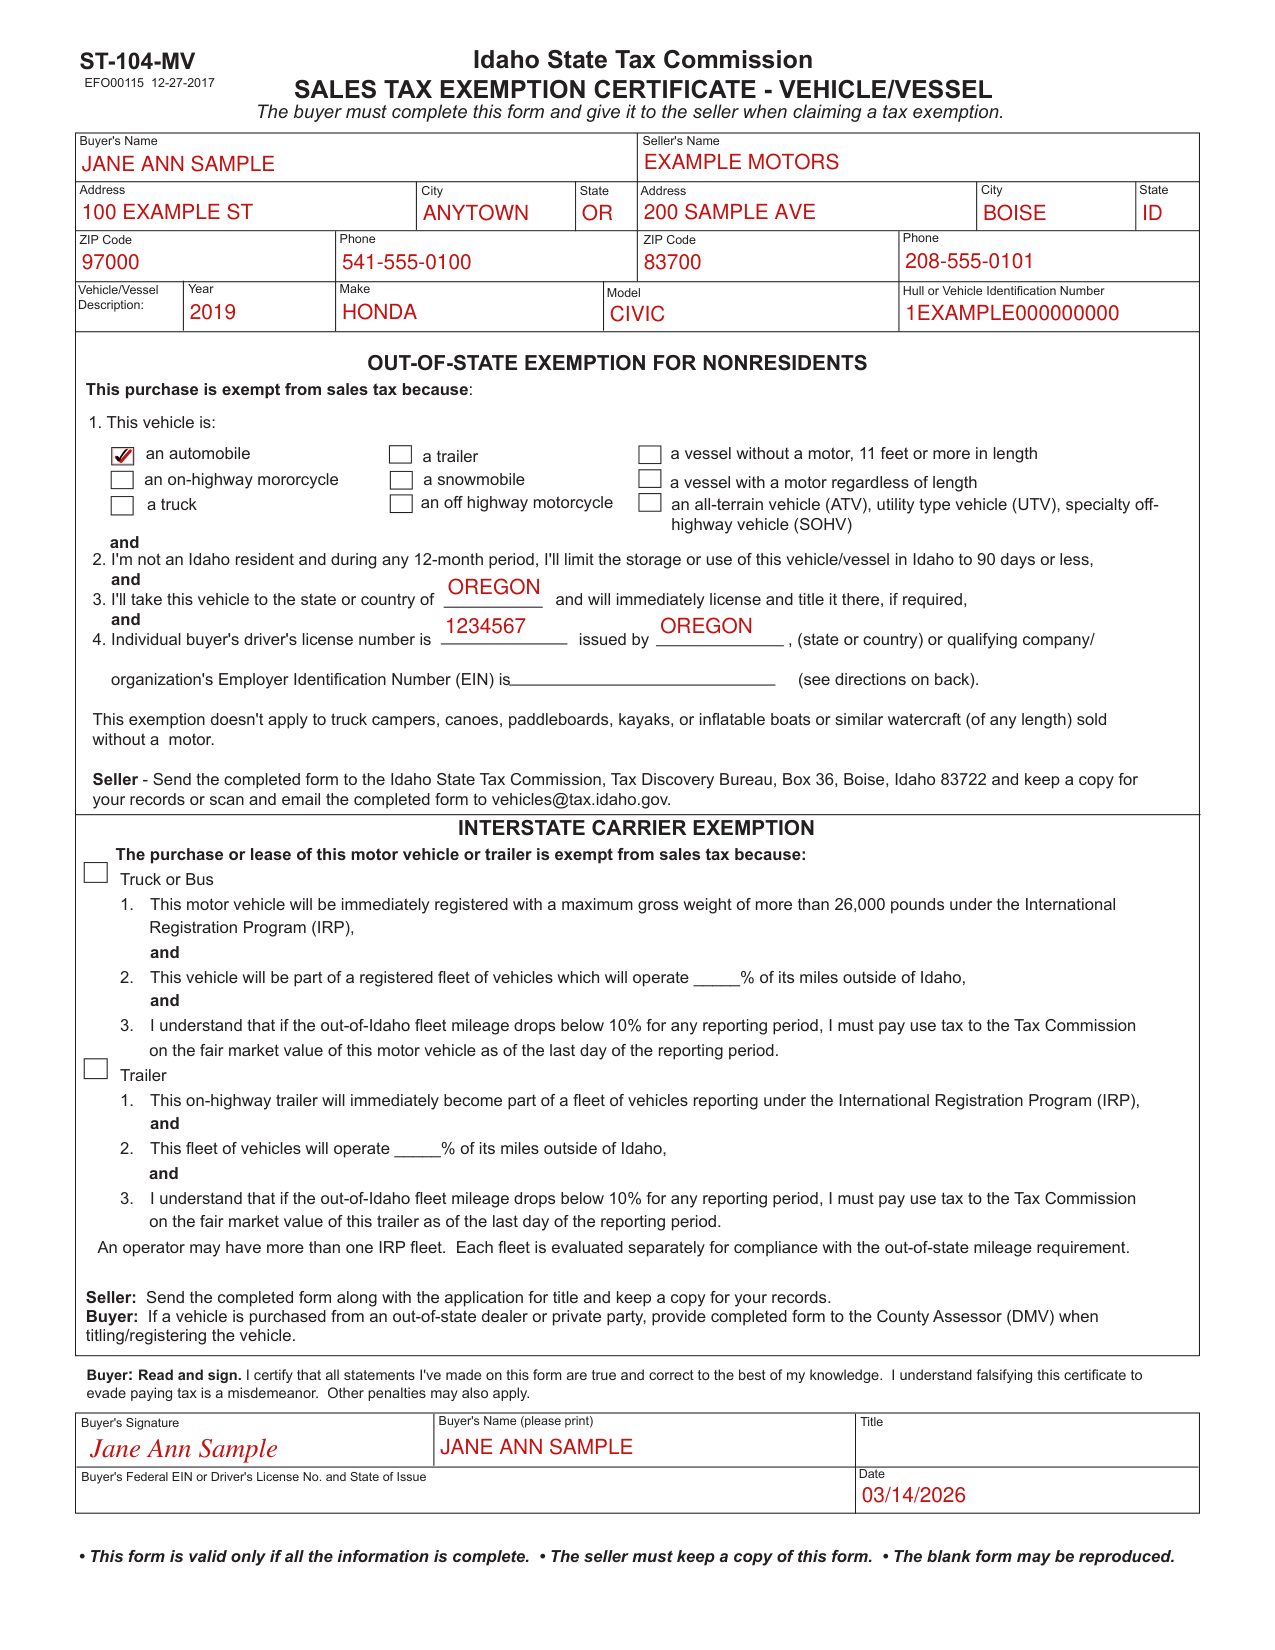
How to fill out Form ST-104-MV, box by box
Buyer's Name and Seller's Name
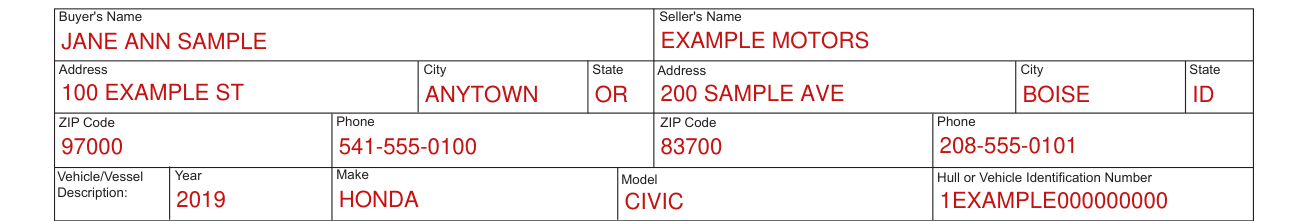
Fill in the Buyer's Name, Address, City, State, ZIP Code and Phone, and the Seller's Name, Address, City, State, ZIP Code and Phone.
Vehicle/Vessel Description

Fill in the Year, Make and Model, the Vehicle/Vessel Description and the Hull or Vehicle Identification Number.
Out-of-State Exemption for Nonresidents
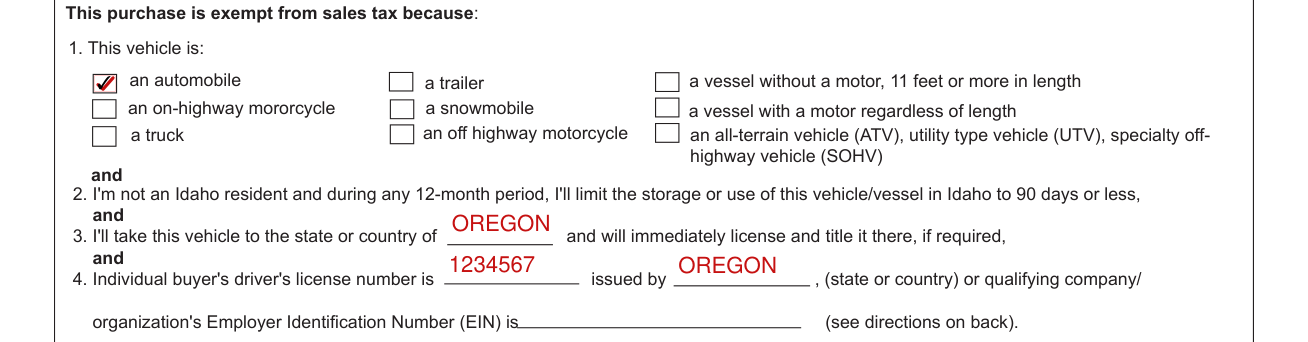
OUT-OF-STATE EXEMPTION FOR NONRESIDENTS: This purchase is exempt from sales tax because 1. This vehicle is: an automobile, a truck, a trailer, a snowmobile, an on-highway motorcycle, an all-terrain vehicle (ATV), utility type vehicle (UTV), specialty off-highway vehicle (SOHV), an off highway motorcycle, a vessel without a motor, 11 feet or more in length, or a vessel with a motor regardless of length.
and 2. I'm not an Idaho resident and during any 12-month period, I'll limit the storage or use of this vehicle/vessel in Idaho to 90 days or less, and 3. I'll take this vehicle to the state or country of ___ and will immediately license and title it there, if required, and 4. Individual buyer's driver's license number is ___ issued by ___ (state or country) or qualifying company/organization's Employer Identification Number (EIN) is ___ (see directions on back).
This exemption doesn't apply to truck campers, canoes, paddleboards, kayaks, or inflatable boats or similar watercraft (of any length) sold without a motor.
To claim an exemption the buyer must complete a Form ST-104-MV (Sales Tax Exemption Certificate - Vehicle/Vessel) stating that the vehicle or vessel: Will immediately be taken out of Idaho and titled and registered in another state or country (if required), and won't be stored or used in Idaho for more than 90 days in any 12-month period.
Idaho residents can't claim this exemption.
A company/organization qualifies for this exemption only if it meets all three of the following criteria:
It's a corporation, partnership, limited liability company, or other organization that isn't formed under the laws of Idaho, and it's not required to be registered with the Idaho Secretary of State to do business in Idaho, and it doesn't have significant contacts and consistent operations in Idaho.
Interstate Carrier Exemption
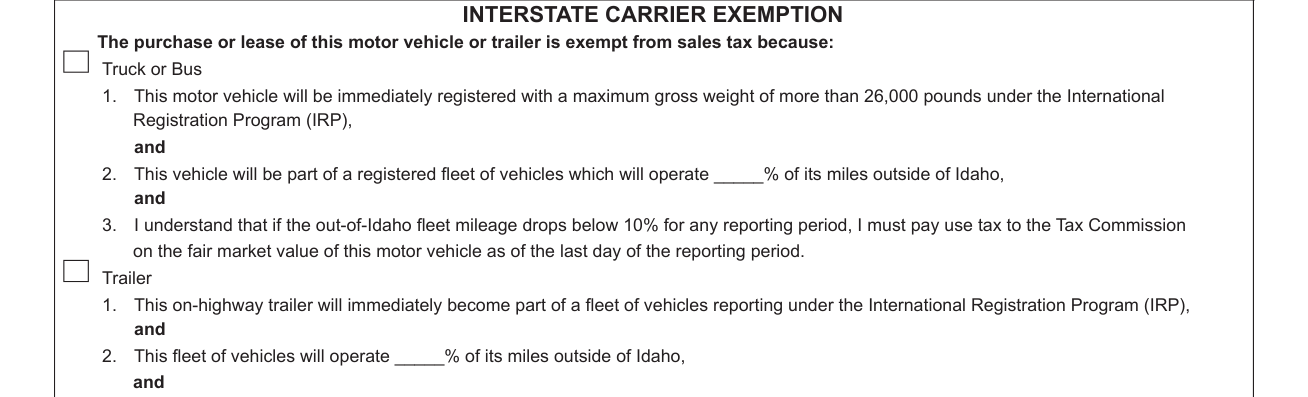
Sales of motor vehicles for use in interstate commerce are exempt if the vehicle will be immediately registered with a maximum gross registered weight of more than 26,000 pounds under the International Registration Plan, and at least 10% of the purchaser's total fleet mileage is outside of Idaho.
In Interstate Carrier Exemption, Truck or Bus: 1. This motor vehicle will be immediately registered with a maximum gross weight of more than 26,000 pounds under the International Registration Program (IRP), and 2. This vehicle will be part of a registered fleet of vehicles which will operate ___% of its miles outside of Idaho, and 3. "I understand that if the out-of-Idaho fleet mileage drops below 10% for any reporting period, I must pay use tax to the Tax Commission on the fair market value of this motor vehicle as of the last day of the reporting period." In Interstate Carrier Exemption, Trailer: 1. This on-highway trailer will immediately become part of a fleet of vehicles reporting under the International Registration Program (IRP), and 2. This fleet of vehicles will operate ___% of its miles outside of Idaho, and 3. "I understand that if the out-of-Idaho fleet mileage drops below 10% for any reporting period, I must pay use tax to the Tax Commission on the fair market value of this trailer as of the last day of the reporting period."
An operator may have more than one IRP fleet. Each fleet is evaluated separately for compliance with the out-of-state mileage requirement.
The exemption applies only to purchases of trucks, buses, and trailers, but not their repair or maintenance. However, the sale of a "glider kit" isn't taxable when used to assemble a glider kit vehicle that will be registered in an IRP fleet and will meet the weight and mileage requirements listed in this exemption.
Buyer's Signature
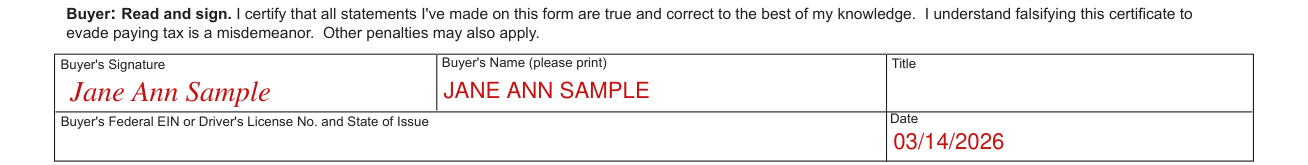
Buyer: Read and sign. "I certify that all statements I've made on this form are true and correct to the best of my knowledge. I understand falsifying this certificate to evade paying tax is a misdemeanor. Other penalties may also apply."
Sign in Buyer's Signature, fill in Buyer's Name (please print) and Title, enter the Buyer's Federal EIN or Driver's License No. and State of Issue, and enter the Date.
More rules for Form ST-104-MV
This form is valid only if all the information is complete. The seller must keep a copy of this form. The blank form may be reproduced.
If your situation is different
You don't receive an exemption certificate from the buyer
EFO00115 12-27-2017 Rule 128 states that if you don't receive an exemption certificate from the buyer at the time of sale, the sale is presumed to be taxable. If you receive an exemption certificate after the sale, but don't get it within a reasonable length of time, the Tax Commission will review the certificate with all other available evidence to determine whether you have clearly proven that the sale was exempt from tax.
Sources
[1] Form ST-104-MV (EFO00115 12-27-2017), Sales Tax Exemption Certificate - Vehicle/Vessel, Idaho State Tax Commission (the Official source link on this page).