

Maryland Form 502CR at a glance
What it is: Maryland Form 502CR is used to claim personal income tax credits for individuals (including resident fiduciaries).
Where and when to file: Form 502CR must be attached to the annual return (Form 502, 504, 505, or 515).
For Part A, the credit for income taxes paid to other states and localities: if you are a Maryland resident (including a resident fiduciary) and you paid income tax to another state, you may be eligible for State and local tax credits on your Maryland return.
For Part F, the credit for preservation and conservation easements: PTE members may not use the Form 502CR to claim this credit.
A filled-in Maryland Form 502CR example: a Maryland resident claims a credit for Georgia tax
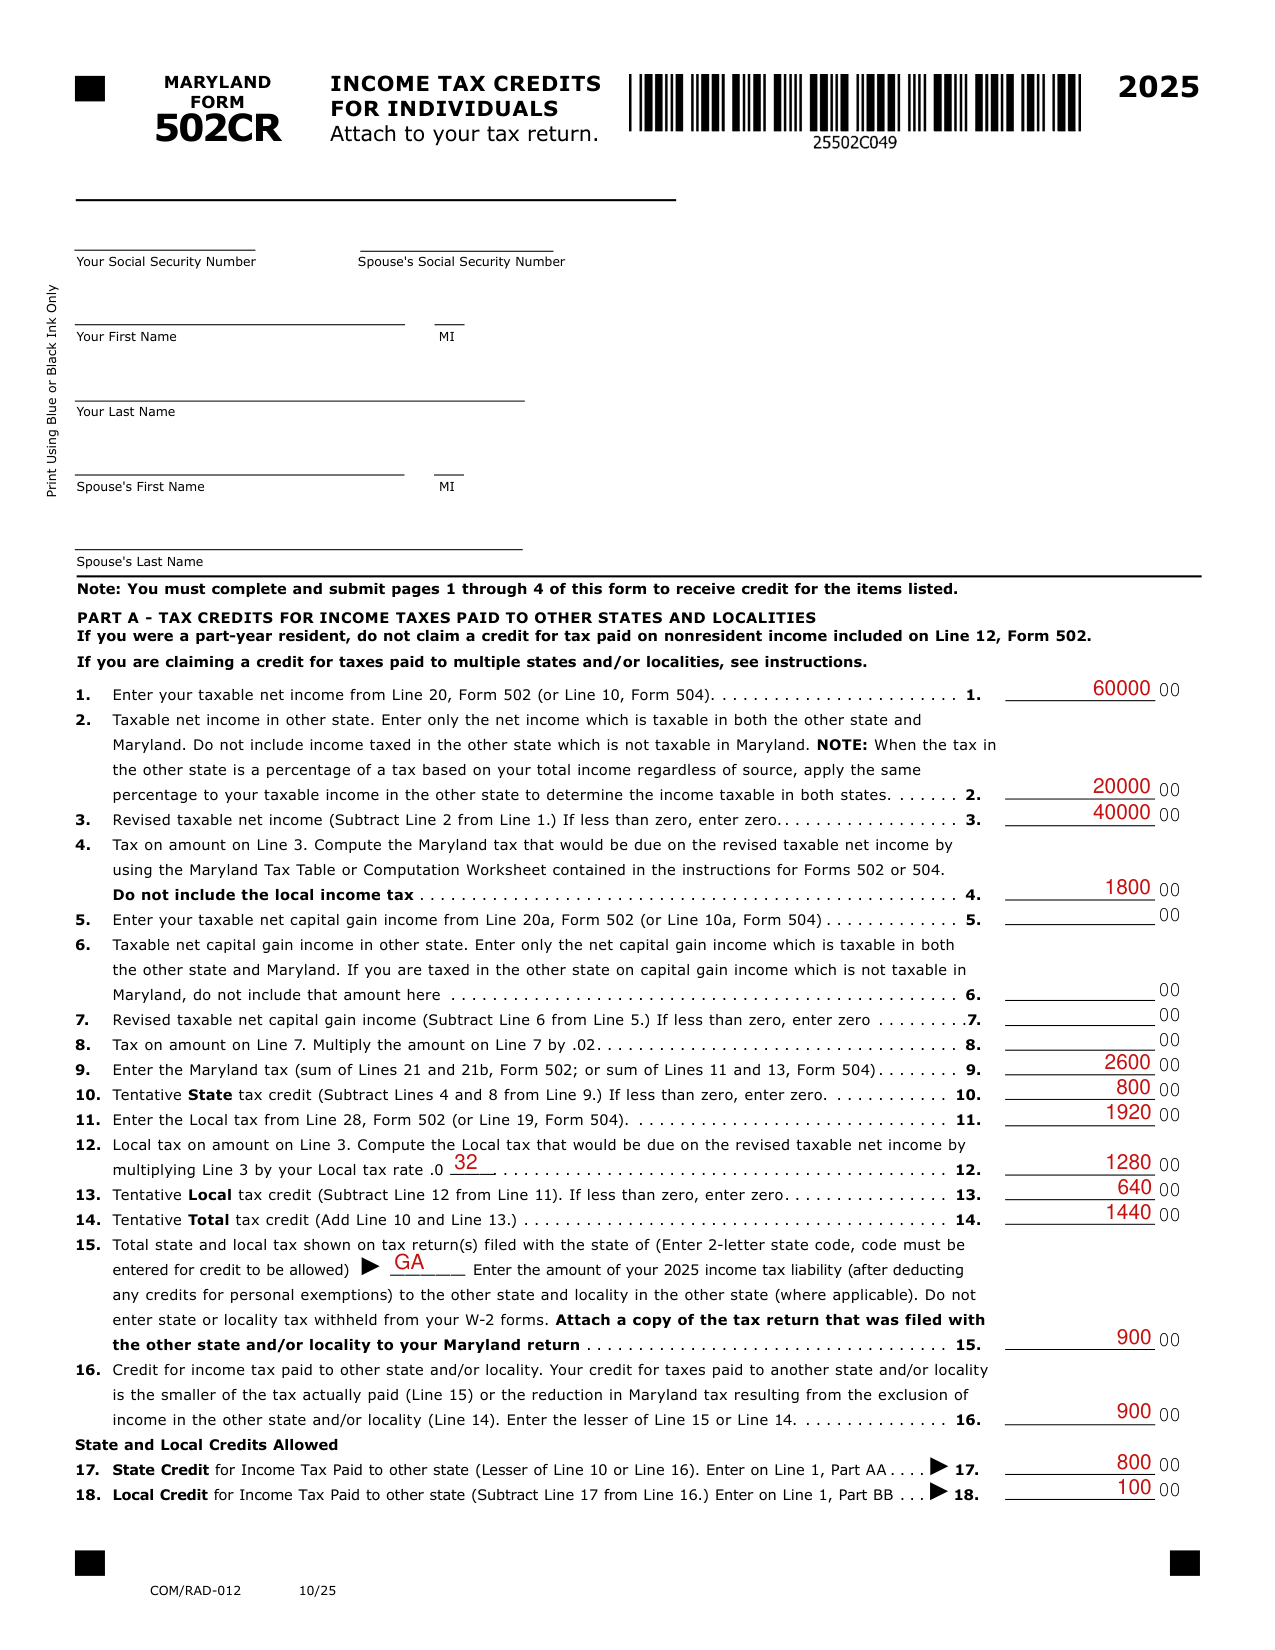
How to fill out Maryland Form 502CR, box by box
Attach Form 502CR to your tax return
For Part A, the credit for income taxes paid to other states and localities, review Administrative Release 42 for additional instructions and required documentation. You must file your Maryland income tax return on Form 502 and complete Lines 1 through 21b and Line 28 of that form, or on Form 504 and complete Lines 1 through 13 and Line 19. Then complete Form 502CR Parts A, AA, and BB and attach to Form 502 or 504.
Group I, Group II or Group III: the other state
Group I is nonreciprocal: credit is taken on the Maryland resident return. To claim a credit for taxes paid to the other state, and/or local jurisdiction in the other state, complete Form 502CR and attach it and a copy of the other state's nonresident income tax return (not just your W-2 Form) and, if applicable, the local jurisdiction's nonresident income tax return to your Maryland return.
Group I states: Alabama, Arizona, Arkansas, California, Colorado, Connecticut, Delaware, Georgia, Hawaii, Idaho, Illinois, Indiana, Iowa, Kansas, Kentucky, Louisiana, Maine, Massachusetts, Michigan, Minnesota, Mississippi, Missouri, Montana, Nebraska, New Hampshire, New Jersey, New Mexico, New York, North Carolina, North Dakota, Ohio, Oklahoma, Oregon, Pennsylvania (except wage income), Rhode Island, South Carolina, Tennessee, Texas, Utah, Vermont, Virginia (except wage income), Washington, DC (except wage income), West Virginia (except wage income), Wisconsin, and the Territories and Possessions of the United States: American Samoa, Guam, Northern Mariana Island, Puerto Rico, U.S. Virgin Islands. A Maryland resident (including a resident fiduciary) having income from one of these states must report the income on the Maryland return Form 502 or 504.
Group II is reciprocal for wages, salaries, tips and commission income only: Pennsylvania, Washington, DC, Virginia and West Virginia. Maryland has a reciprocal agreement with the states included in Group II. The agreement applies only to wages, salaries, tips and commissions. It does not apply to business income, farm income, rental income, gain from the sale of tangible property, etc. If you had such income subject to tax in these states, complete Form 502CR and attach it and a copy of the other state's nonresident income tax return (not just your W-2 Form) and, if applicable, the local tax jurisdiction's nonresident income tax return to your Maryland return. If you had wages subject to tax in a locality in Pennsylvania, you may file Form 502CR to claim a State and local tax credit. Enter the amount of tax that you paid to the locality on Line 15, Part A of the Form 502CR.
Group III has no state income tax, so no credit is allowed: Alaska, South Dakota, Florida, Washington, Nevada and Wyoming. You must report income from these states on your Maryland resident return. You cannot claim any credit for income earned in these states because you did not pay any income tax to the other state.
Do not use the income or withholding tax reported on the wage and tax statement (W-2 form) issued by your employer for the credit computation.
Income taxable in both states: Lines 1 to 4
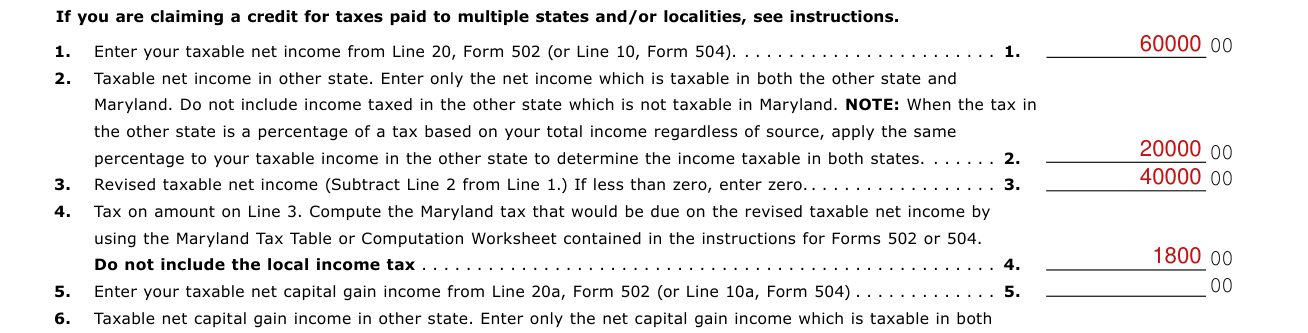
On Line 1, enter your taxable net income from Line 20, Form 502 (or Line 10, Form 504).
On Line 2, enter only the net income which is taxable in both the other state and Maryland. Do not include income taxed in the other state which is not taxable in Maryland. When the tax in the other state is a percentage of a tax based on your total income regardless of source, apply the same percentage to your taxable income in the other state to determine the income taxable in both states.
On Line 3, subtract Line 2 from Line 1. If less than zero, enter zero.
On Line 4, compute the Maryland tax that would be due on the revised taxable net income by using the Maryland Tax Table or Computation Worksheet contained in the instructions for Forms 502 or 504. Do not include the local income tax.
Capital gain income: Lines 5 to 8
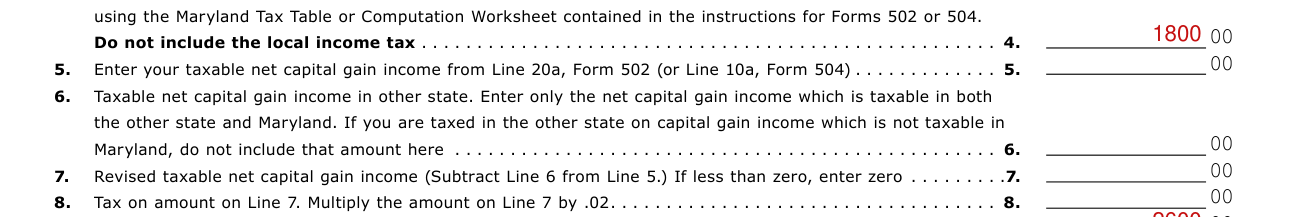
On Line 5, enter your taxable net capital gain income from Line 20a, Form 502 (or Line 10a, Form 504).
On Line 6, enter only the net capital gain income which is taxable in both the other state and Maryland. If you are taxed in the other state on capital gain income which is not taxable in Maryland, do not include that amount here.
On Line 7, subtract Line 6 from Line 5. If less than zero, enter zero.
On Line 8, multiply the amount on Line 7 by .02.
Maryland tax and tentative State tax credit: Lines 9 and 10
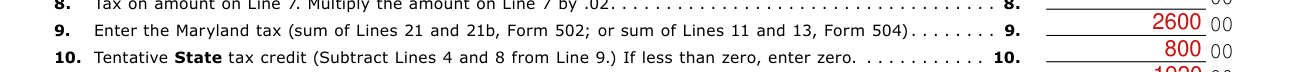
On Line 9, enter the Maryland tax (sum of Lines 21 and 21b, Form 502; or sum of Lines 11 and 13, Form 504).
On Line 10, subtract Lines 4 and 8 from Line 9. If less than zero, enter zero.
Local tax and tentative Total tax credit: Lines 11 to 14
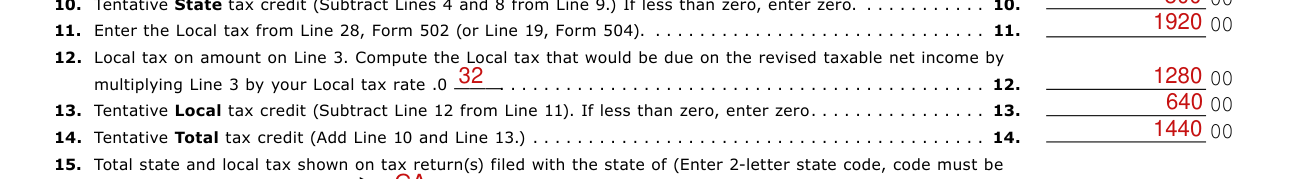
On Line 11, enter the Local tax from Line 28, Form 502 (or Line 19, Form 504).
On Line 12, compute the Local tax that would be due on the revised taxable net income by multiplying Line 3 by your Local tax rate.
On Line 13, subtract Line 12 from Line 11. If less than zero, enter zero.
On Line 14, add Line 10 and Line 13.
Tax paid to the other state: Lines 15 and 16
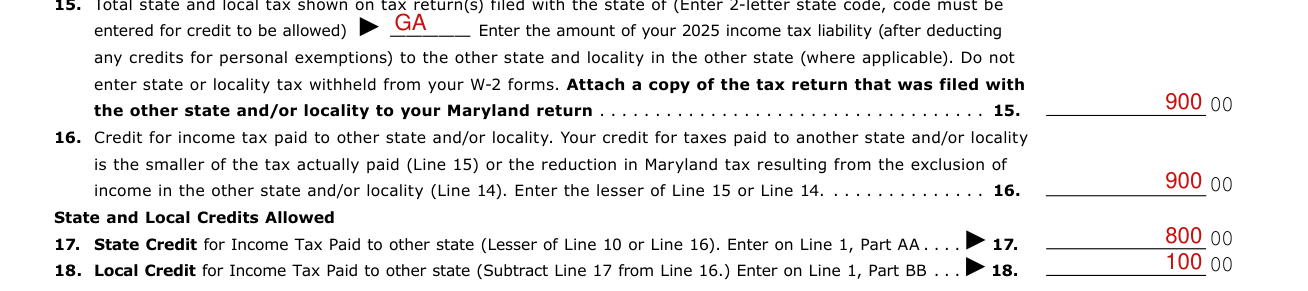
On Line 15, enter the 2-letter state code of the state your tax return(s) were filed with; the code must be entered for credit to be allowed.
Enter the amount of your 2025 income tax liability (after deducting any credits for personal exemptions) to the other state and locality in the other state (where applicable). Do not enter state or locality tax withheld from your W-2 forms.
On Line 16, your credit for taxes paid to another state and/or locality is the smaller of the tax actually paid (Line 15) or the reduction in Maryland tax resulting from the exclusion of income in the other state and/or locality (Line 14). Enter the lesser of Line 15 or Line 14.
State and Local Credits Allowed: Lines 17 and 18
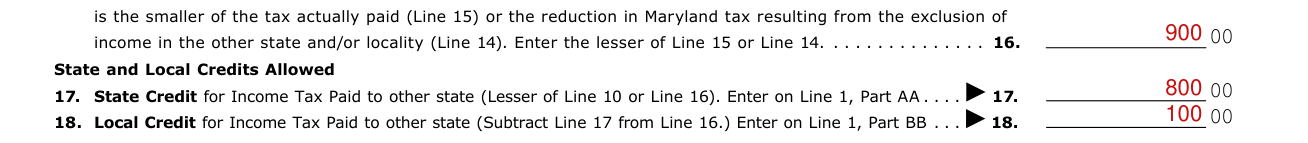
On Line 17, enter the lesser of Line 10 or Line 16. Enter it on Line 1, Part AA.
On Line 18, subtract Line 17 from Line 16. Enter it on Line 1, Part BB.
Part AA and Part BB: the credit summary
In Part AA, the income tax credit summary, enter on Line 1 the amount from Part A, Line 17 (If more than one state, see Instructions.).
In Part BB, the local income tax credit summary, enter on Line 1 the amount from Part A, Line 18 (If more than one state, see Instructions.). Enter this amount on Line 31 of Form 502; Line 20 of Form 504.
More rules for Maryland Form 502CR
You must file Form 500CR electronically to claim any business income tax credit other than the Community Investment and Endow Maryland Tax Credits.
Resident fiduciaries may use Form 502CR to claim only a credit for income taxes paid to other states and/or localities or a credit for Preservation and Conservation Easements.
If your situation is different
You paid tax to multiple states
If you are claiming credit for taxes paid to multiple states, a separate Form 502CR must be completed for each state.
You were a part-year resident
If you were a part-year resident, do not claim a credit for tax paid on nonresident income included on Line 12, Form 502.
Common questions about Maryland Form 502CR
What are the instructions for completing form 502CR in Maryland?
Maryland Form 502CR is used to claim personal income tax credits for individuals (including resident fiduciaries). You must complete and submit pages 1 through 4 of this form to receive credit for the items listed.
When is this form not the right one?
Nonresidents (filing Form 505, 515 or 504) are not eligible for the Part A credit.
Sources
[1] Maryland Form 502CR (COM/RAD-012 10/25), Income Tax Credits for Individuals, Comptroller of Maryland (the Official source link on this page).