
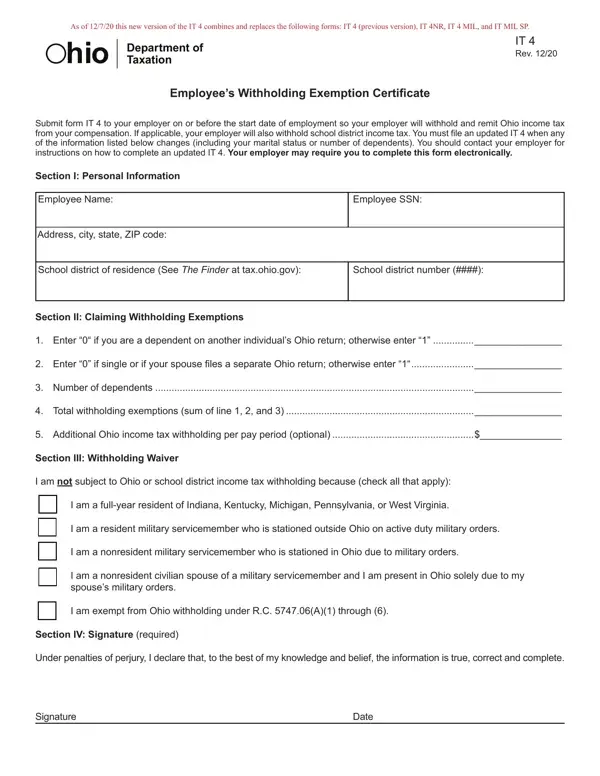

Form IT 4 at a glance
What it is: Form IT 4, the Employee's Withholding Exemption Certificate, is what you submit to your employer so your employer will withhold and remit Ohio income tax from your compensation.
Who signs: Under penalties of perjury, I declare that, to the best of my knowledge and belief, the information is true, correct and complete.
Employees who are subject to Ohio income tax (and school district income tax, if applicable) should complete sections I, II, and IV of the IT 4.
Certain employees may be exempt from Ohio withholding because their income is not subject to Ohio tax. Such employees should complete sections I, III, and IV of the IT 4 only.
A filled-in Form IT 4 example: a single employee fills out the IT 4
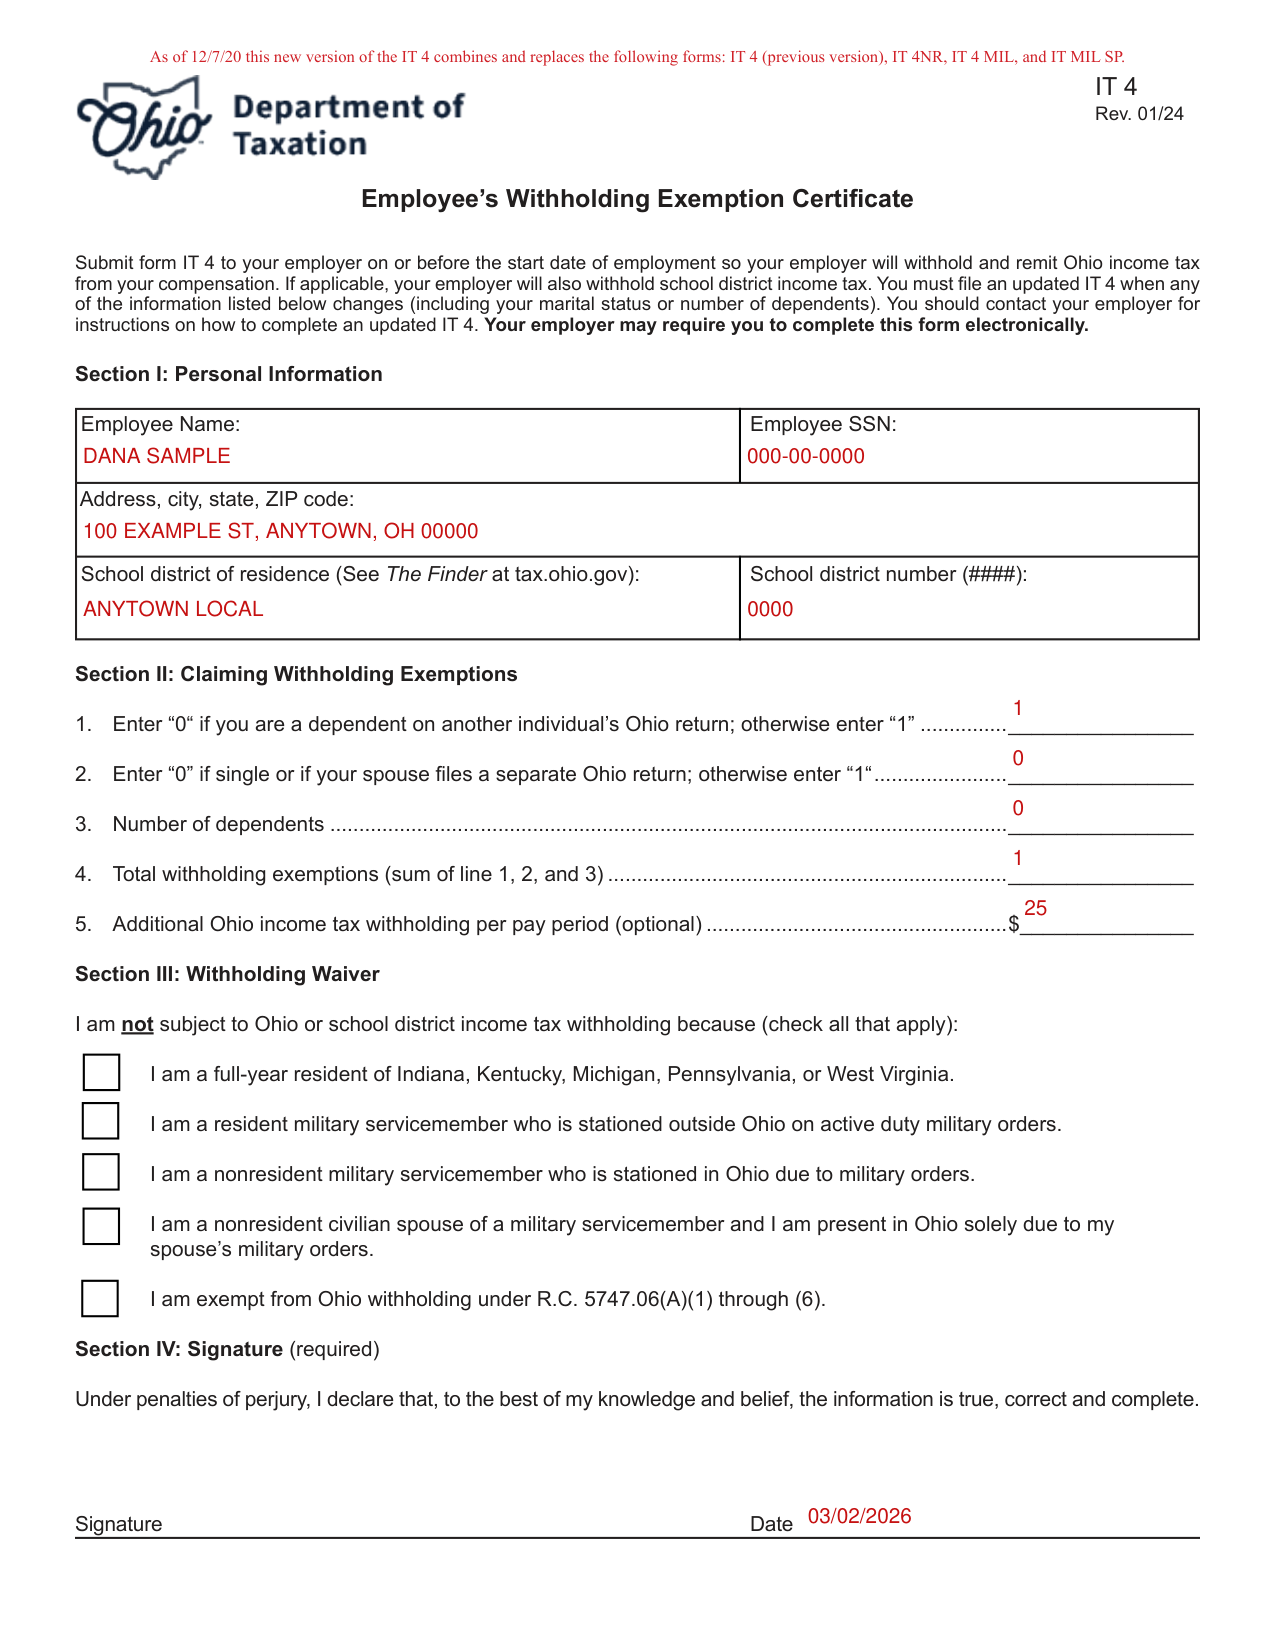
How to fill out Form IT 4, box by box
Section I: Personal Information
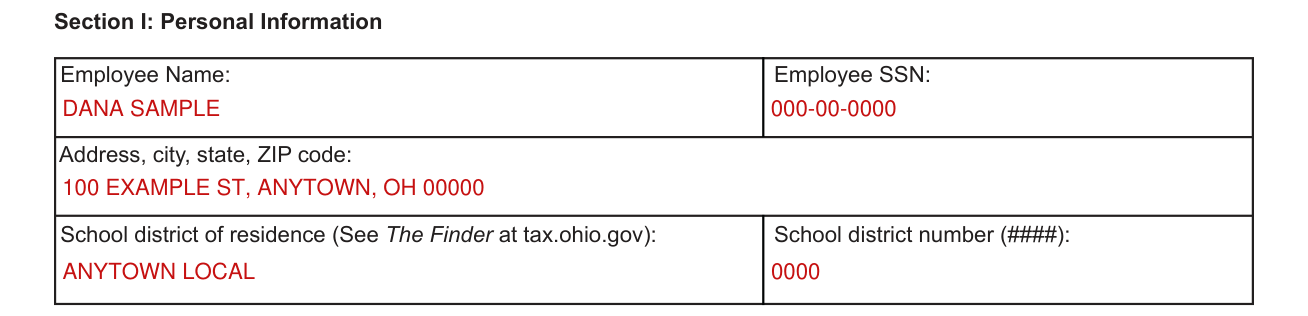
Enter the four-digit school district number of your primary address. If you do not know your school district of residence or its school district number, use The Finder at tax.ohio.gov.
You can also verify your school district by contacting your county auditor or county board of elections.
If you move during the tax year, complete an updated IT 4 immediately reflecting your new address or school district of residence.
Section II: Claiming Withholding Exemptions
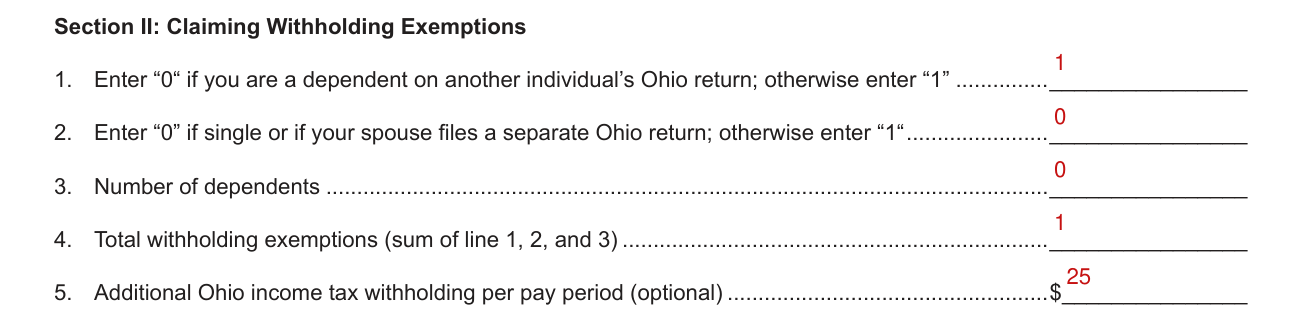
Line 1: If you can be claimed on someone else's Ohio income tax return as a dependent, enter 0 on this line. Everyone else may enter 1.
Line 2: If you are single, enter 0 on this line. If you are married and you and your spouse file separate Ohio income tax returns as Married filing Separately, enter 0 on this line.
Line 3: You are allowed one exemption for each dependent. Your dependents for Ohio income tax purposes are the same as your dependents for federal income tax purposes.
Line 5: Additional Ohio income tax withholding per pay period is optional. This amount should be reported in whole dollars.
If you do not request additional withholding from your compensation, you may need to make estimated income tax payments using form IT 1040ES or estimated school district income tax payments using the SD 100ES.
Individuals who commonly owe more in Ohio income taxes than what is withheld from their compensation include spouses who file a joint Ohio income tax return and both report income, and individuals who have multiple jobs, all of which are subject to Ohio withholding.
Section III: Withholding Waiver
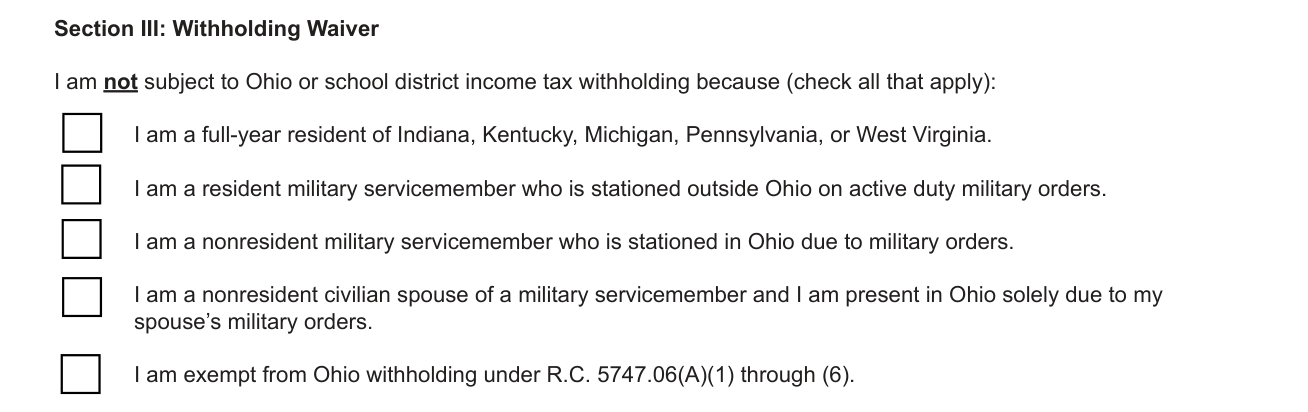
Section III: Withholding Waiver is for individuals whose income is deductible or excludable from Ohio income tax, and thus employer withholding is not required. Check all that apply.
Check the appropriate box to indicate which exemption applies to you. Checking the box will cause your employer to not withhold Ohio income tax and/or school district income tax.
Reciprocity Exemption: If you are a resident of Indiana, Kentucky, Pennsylvania, Michigan or West Virginia and you work in Ohio, you do not owe Ohio income tax on your compensation. Instead, you should have your employer withhold income tax for your resident state. R.C. 5747.05(A)(2). Resident Military Servicemember Exemption: If you are an Ohio resident and a member of the United States Army, Air Force, Navy, Marine Corps, or Coast Guard (or the reserve components of these branches of the military) or a member of the National Guard, you do not owe Ohio income tax or school district income tax on your active duty military pay and allowances received while stationed outside of Ohio. This exemption does not apply to compensation for nonactive duty status or received while you are stationed in Ohio. R.C. 5747.01(A)(21). Nonresident Military Servicemember Exemption: If you are a nonresident of Ohio and a member of the uniformed services (as defined in 10 U.S.C. §101), you do not owe Ohio income tax or school district income tax on your military pay and allowances. Nonresident Civilian Spouse of a Military Servicemember Exemption: If you are the civilian spouse of a military servicemember, your pay may be exempt from Ohio income tax and school district income tax if all of the following are true: your spouse is stationed in Ohio on military orders; and you are present in Ohio solely to be with your spouse. For the Nonresident Civilian Spouse of a Military Servicemember Exemption, you must provide a copy of the employee's spousal military identification card issued to the employee by the Department of Defense when completing the IT 4.
I am exempt from Ohio withholding under R.C. 5747.06(A)(1) through (6). While the employer is not required to withhold on these amounts, the income is still subject to Ohio income tax and school district income tax (if applicable). As such, you may need to make estimated income tax payments using form IT 1040ES and/or estimated school district income tax payments using form SD 100ES.
Section IV: Signature (required)
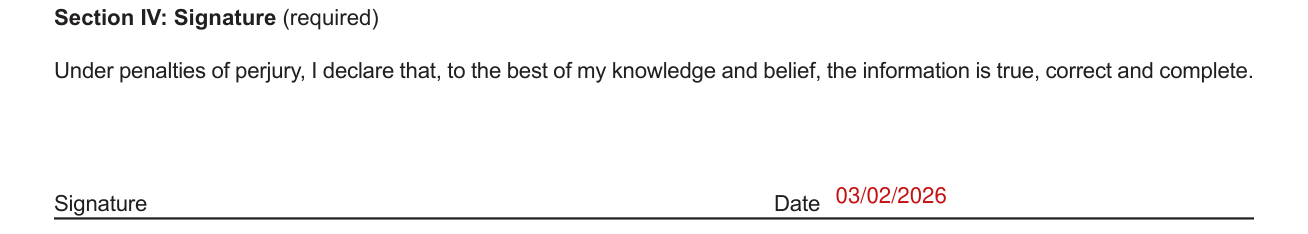
Section IV: Signature (required). Sign, and enter the Date.
More rules for Form IT 4
You must file an updated IT 4 when any of the information listed on the form changes (including your marital status or number of dependents).
If the employee does not complete the IT 4 and return it to his/her employer, the employer will withhold Ohio tax based on the employee claiming zero exemptions, and will not withhold school district income tax, even if the employee lives in a taxing school district.
Common questions about Form IT 4
How many exemptions should I claim in Ohio?
Line 4: Total withholding exemptions is the sum of line 1, 2, and 3.
What should I set my tax withholding to?
Line 5: If you expect to owe more Ohio income tax than the amount withheld from your compensation, you can request that your employer withhold an additional amount of Ohio income tax.
Is there a deadline?
Submit form IT 4 to your employer on or before the start date of employment.
Where do I file it?
The IT 4 does not need to be filed with the Department of Taxation. Your employer must maintain a copy as part of its records.
Is there a penalty?
An individual may be subject to an interest penalty for underpayment of estimated taxes (on form IT/SD 2210) based on under-withholding.
Sources
[1] Form IT 4 (Rev. 01/24), Employee's Withholding Exemption Certificate, Ohio Department of Taxation (the Official source link on this page).