
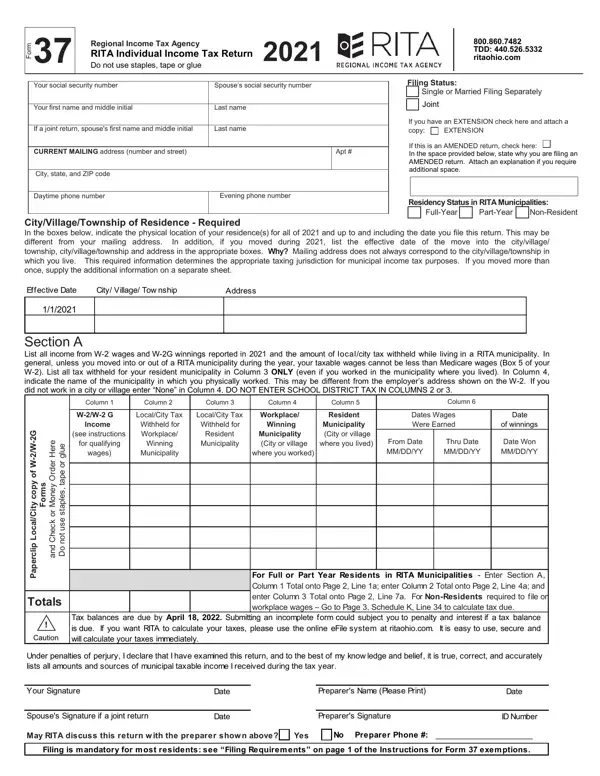

Form 37 at a glance
What it is: Form 37 (2025) is the Regional Income Tax Agency RITA Individual Income Tax Return. Do not use staples, tape or glue.
Where and when to file: Tax balances are due by April 15, 2026. Submitting an incomplete form could subject you to penalty and interest if a tax balance is due. If you want RITA to calculate your taxes, please use the online eFile system at ritaohio.com. It is easy to use, secure and will calculate your taxes immediately.
Filing is mandatory for most residents: see “Filing Requirements” on page 1 of the Instructions for Form 37 exemptions.
What to bring and attach to Form 37
Paperclip the Local/City copy of W-2/W-2G Forms and the Check or Money Order. Do not use staples, tape or glue.
A filled-in Form 37 example: a single resident who lives and works in one city
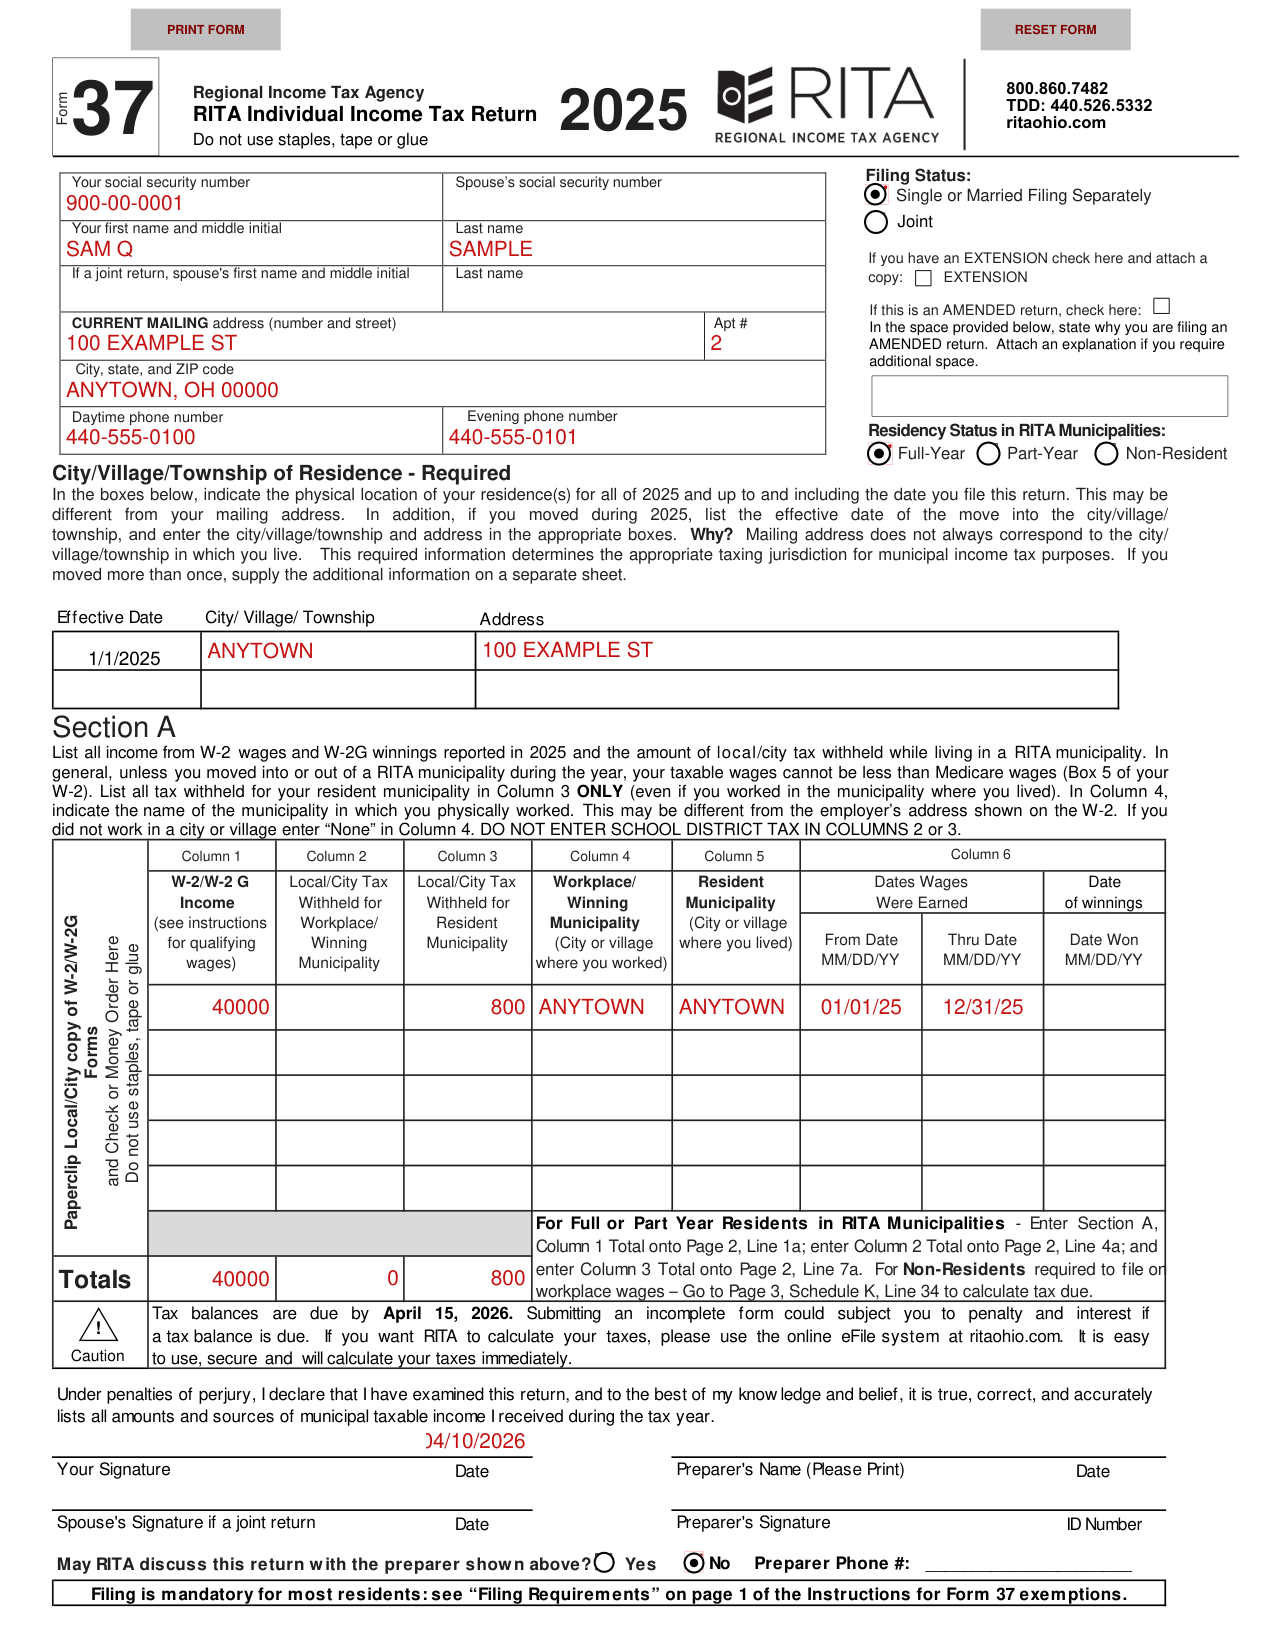
How to fill out Form 37, box by box
Filing Status

Filing Status: Single or Married Filing Separately, or Joint.
Your and your spouse's names and social security numbers
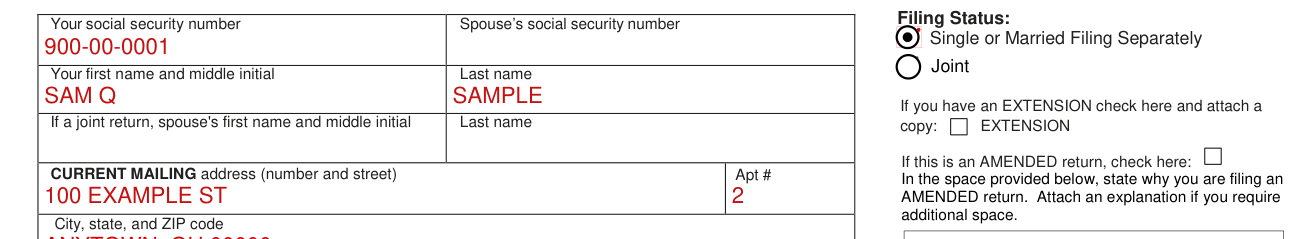
Enter Your social security number and Spouse's social security number.
Enter Your first name and middle initial and Last name. If a joint return, enter spouse's first name and middle initial and Last name.
Mailing address and phone numbers
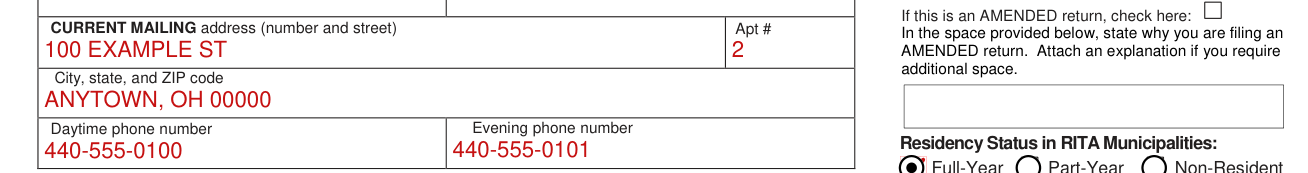
Enter CURRENT MAILING address (number and street), Apt #, and City, state, and ZIP code.
Enter Daytime phone number and Evening phone number.
EXTENSION and AMENDED return
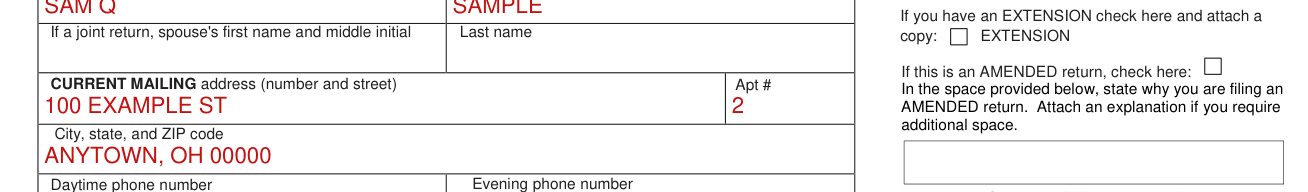
If you have an EXTENSION check here and attach a copy: EXTENSION.
If this is an AMENDED return, check here. In the space provided, state why you are filing an AMENDED return. Attach an explanation if you require additional space.
Residency Status in RITA Municipalities
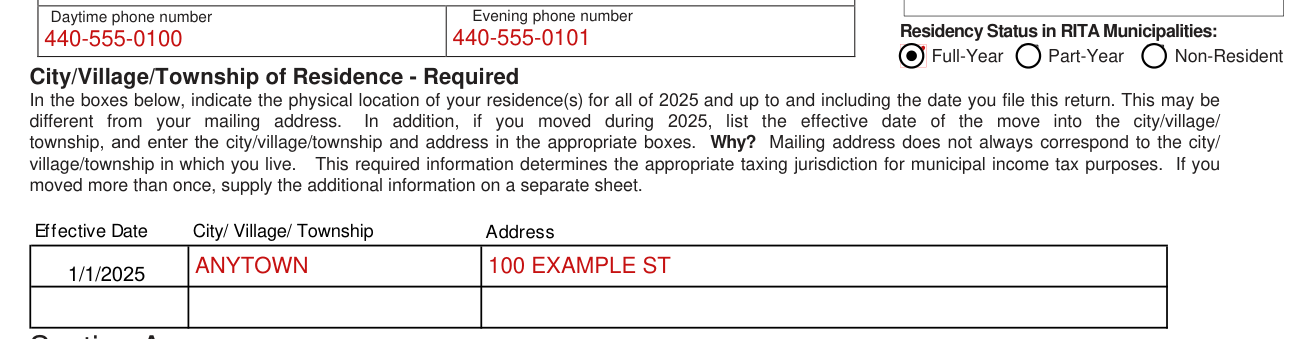
Residency Status in RITA Municipalities: Full-Year Part-Year Non-Resident City/Village/Township of Residence - Required In the boxes, indicate the physical location of your residence(s) for all of 2025 and up to and including the date you file this return. This may be different from your mailing address. In addition, if you moved during 2025, list the effective date of the move into the city/village/ township, and enter the city/village/township and address in the appropriate boxes. Why? Mailing address does not always correspond to the city/ village/township in which you live. This required information determines the appropriate taxing jurisdiction for municipal income tax purposes. If you moved more than once, supply the additional information on a separate sheet. Effective Date, City/Village/Township, Address.
Section A - W-2 and W-2G income and tax withheld
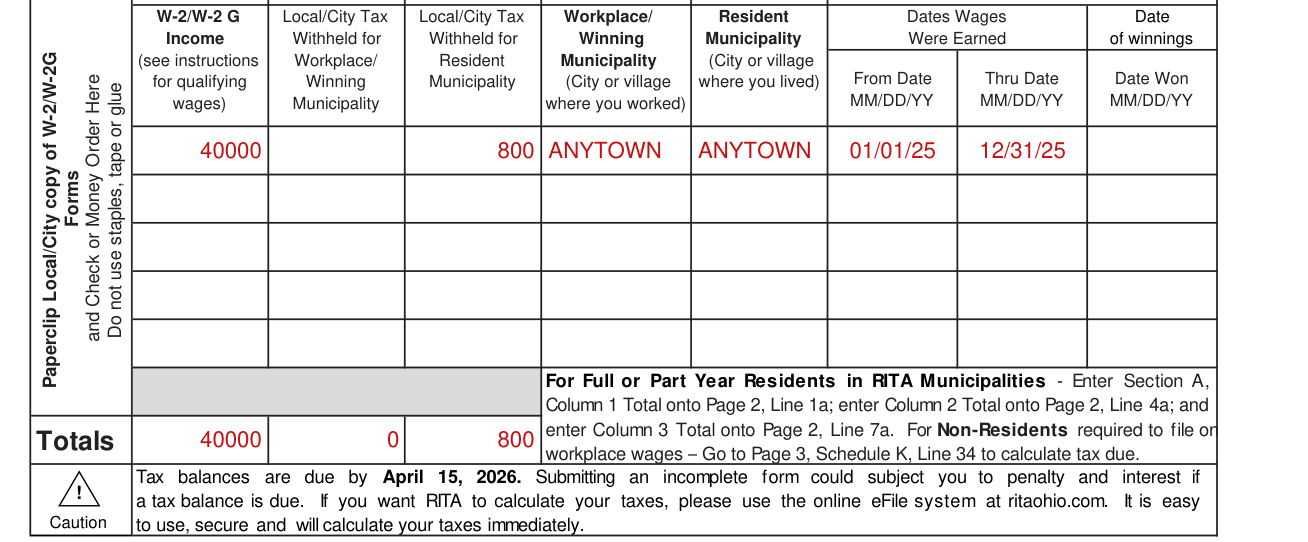
Section A List all income from W-2 wages and W-2G winnings reported in 2025 and the amount of local/city tax withheld while living in a RITA municipality. In general, unless you moved into or out of a RITA municipality during the year, your taxable wages cannot be less than Medicare wages (Box 5 of your W-2). List all tax withheld for your resident municipality in Column 3 ONLY (even if you worked in the municipality where you lived). In Column 4, indicate the name of the municipality in which you physically worked. This may be different from the employer's address shown on the W-2. If you did not work in a city or village enter “None” in Column 4. DO NOT ENTER SCHOOL DISTRICT TAX IN COLUMNS 2 or 3.
For Full or Part Year Residents in RITA Municipalities - Enter Section A, Column 1 Total onto Page 2, Line 1a; enter Column 2 Total onto Page 2, Line 4a; and enter Column 3 Total onto Page 2, Line 7a. For Non-Residents required to file on workplace wages - Go to Page 3, Schedule K, Line 34 to calculate tax due.
Signatures and preparer
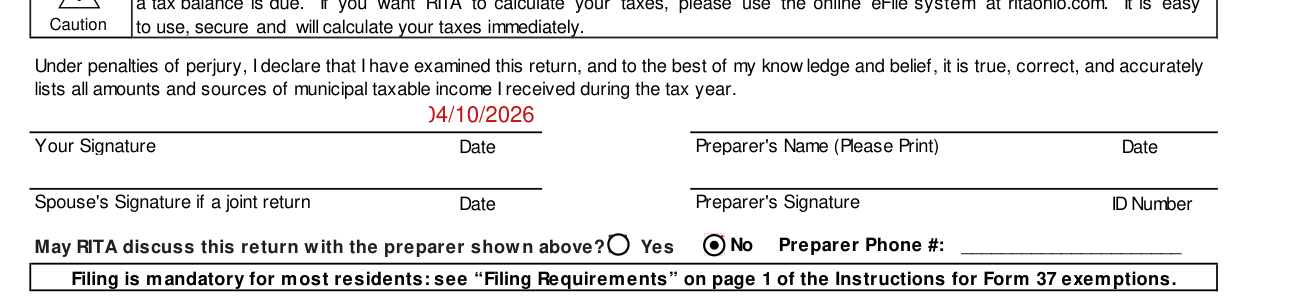
Under penalties of perjury, I declare that I have examined this return, and to the best of my know ledge and belief, it is true, correct, and accurately lists all amounts and sources of municipal taxable income I received during the tax year.
Your Signature and Date. Spouse's Signature if a joint return and Date. Preparer's Name (Please Print). Preparer's Signature, Date and ID Number.
May RITA discuss this return with the preparer? Yes No. Preparer Phone #: ______________________
Section B - Lines 1a to 9: Total taxable income and tax
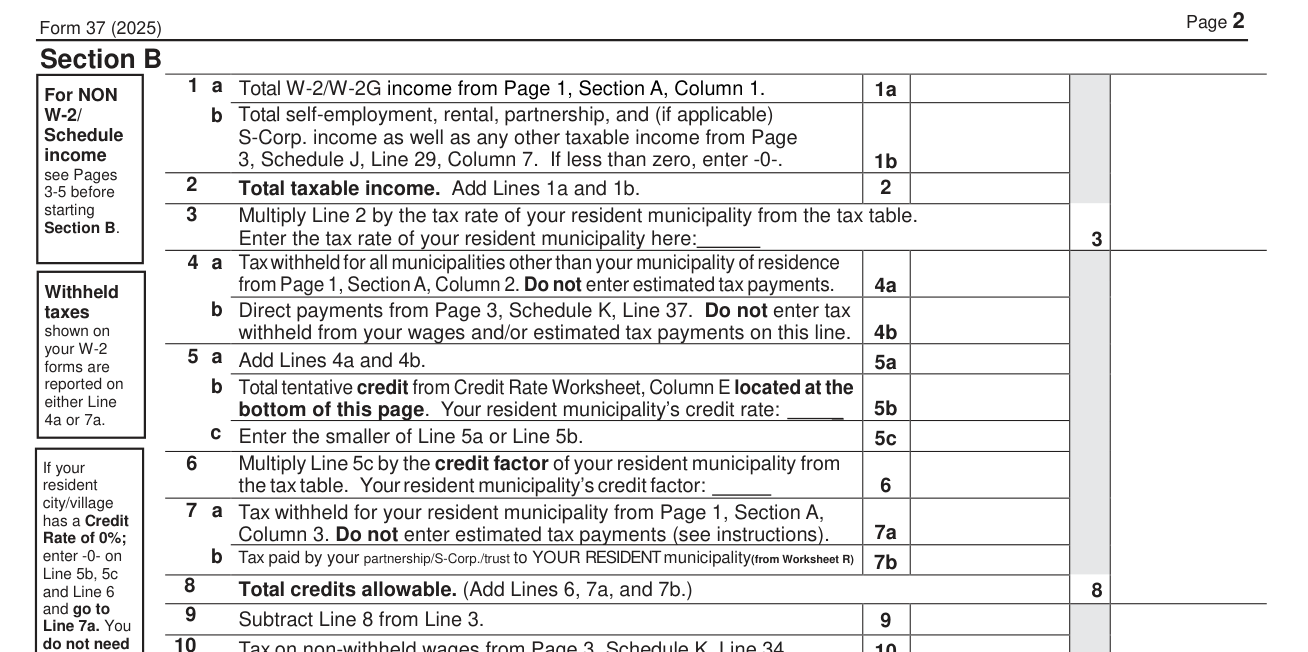
Enter Total W-2/W-2G income from Page 1, Section A, Column 1 on Line 1a.
Line 1b is Total self-employment, rental, partnership, and (if applicable) S-Corp. income as well as any other taxable income from Page 3, Schedule J, Line 29, Column 7. If less than zero, enter -0-. For NON W-2/ Schedule income see Pages 3-5 before starting Section B.
Line 2 is Total taxable income: Add Lines 1a and 1b.
Line 3: Multiply Line 2 by the tax rate of your resident municipality from the tax table. Enter the tax rate of your resident municipality here.
Tax withheld for all municipalities other than your municipality of residence from Page 1, Section A, Column 2. Do not enter estimated tax payments.
Tax withheld for your resident municipality from Page 1, Section A, Column 3. Do not enter estimated tax payments (see instructions).
Line 9: Subtract Line 8 from Line 3.
Section B - Lines 12 to 22: tax due, payments and refund
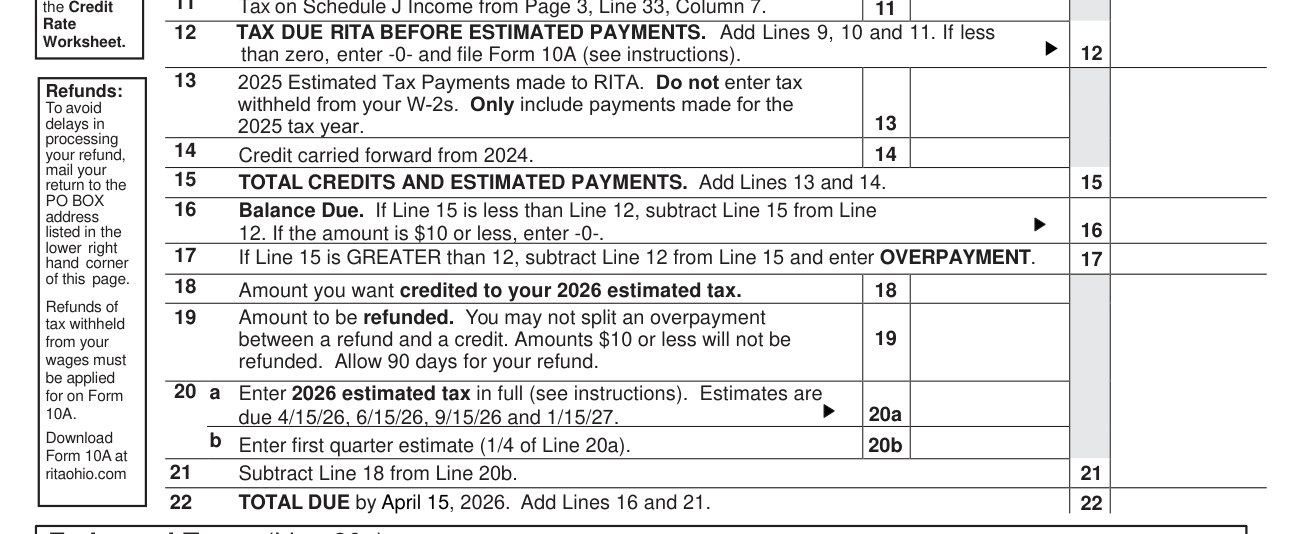
Line 12 is TAX DUE RITA BEFORE ESTIMATED PAYMENTS: Add Lines 9, 10 and 11. If less than zero, enter -0- and file Form 10A (see instructions).
Line 16 is Balance Due. If Line 15 is less than Line 12, subtract Line 15 from Line 12. If the amount is $10 or less, enter -0- (checked October 20, 2026).
Line 17 (16 17): If Line 15 is GREATER than 12, subtract Line 12 from Line 15 and enter OVERPAYMENT.
After Line 17, Line 18 is Amount you want credited to your 2026 estimated tax. Line 19 is Amount to be refunded. You may not split an overpayment between a refund and a credit.
Refunds: To avoid delays in processing your refund, mail your return to the PO BOX address. Allow 90 days for your refund. Refunds of tax withheld from your wages must be applied for on Form 10A.
Common questions about Form 37
What is Ohio RITA form 37?
Form 37 (2025) is the Regional Income Tax Agency RITA Individual Income Tax Return. Do not use staples, tape or glue. See RITA Municipalities at ritaohio.com.
Is there a deadline?
Line 22 is TOTAL DUE by April 15, 2026: Add Lines 16 and 21.
Where do I file it?
Mail your return with W-2s and a copy of your federal schedules to: With payment made payable to RITA: Regional Income Tax Agency PO Box 6600 Cleveland, OH 44101-2004. Without payment: Regional Income Tax Agency PO Box 94801 Cleveland, OH 44101-4801. Refund with an amount on Line 19: Regional Income Tax Agency PO Box 89409 Cleveland, OH 44101-6409.
Is there a penalty?
If your estimated tax payments are not 90% of the tax due or not equal to or greater than your prior year's total tax liability, you may be subject to penalty and interest.
Sources
[1] Form 37 (2025), Regional Income Tax Agency RITA Individual Income Tax Return, Regional Income Tax Agency (the Official source link on this page).