

Form RUT-50 Private Party Vehicle Use Tax Chart at a glance
What it is: Illinois Department of Revenue Private Party Vehicle Use Tax Chart for 2026 (Use with Form RUT-50). Effective January 1, 2026, through December 31, 2026.
The Form RUT-50 Private Party Vehicle Use Tax Chart: read it on screen or print it
How to read Form RUT-50 Private Party Vehicle Use Tax Chart, part by part
Illinois Private Party Vehicle Use Tax
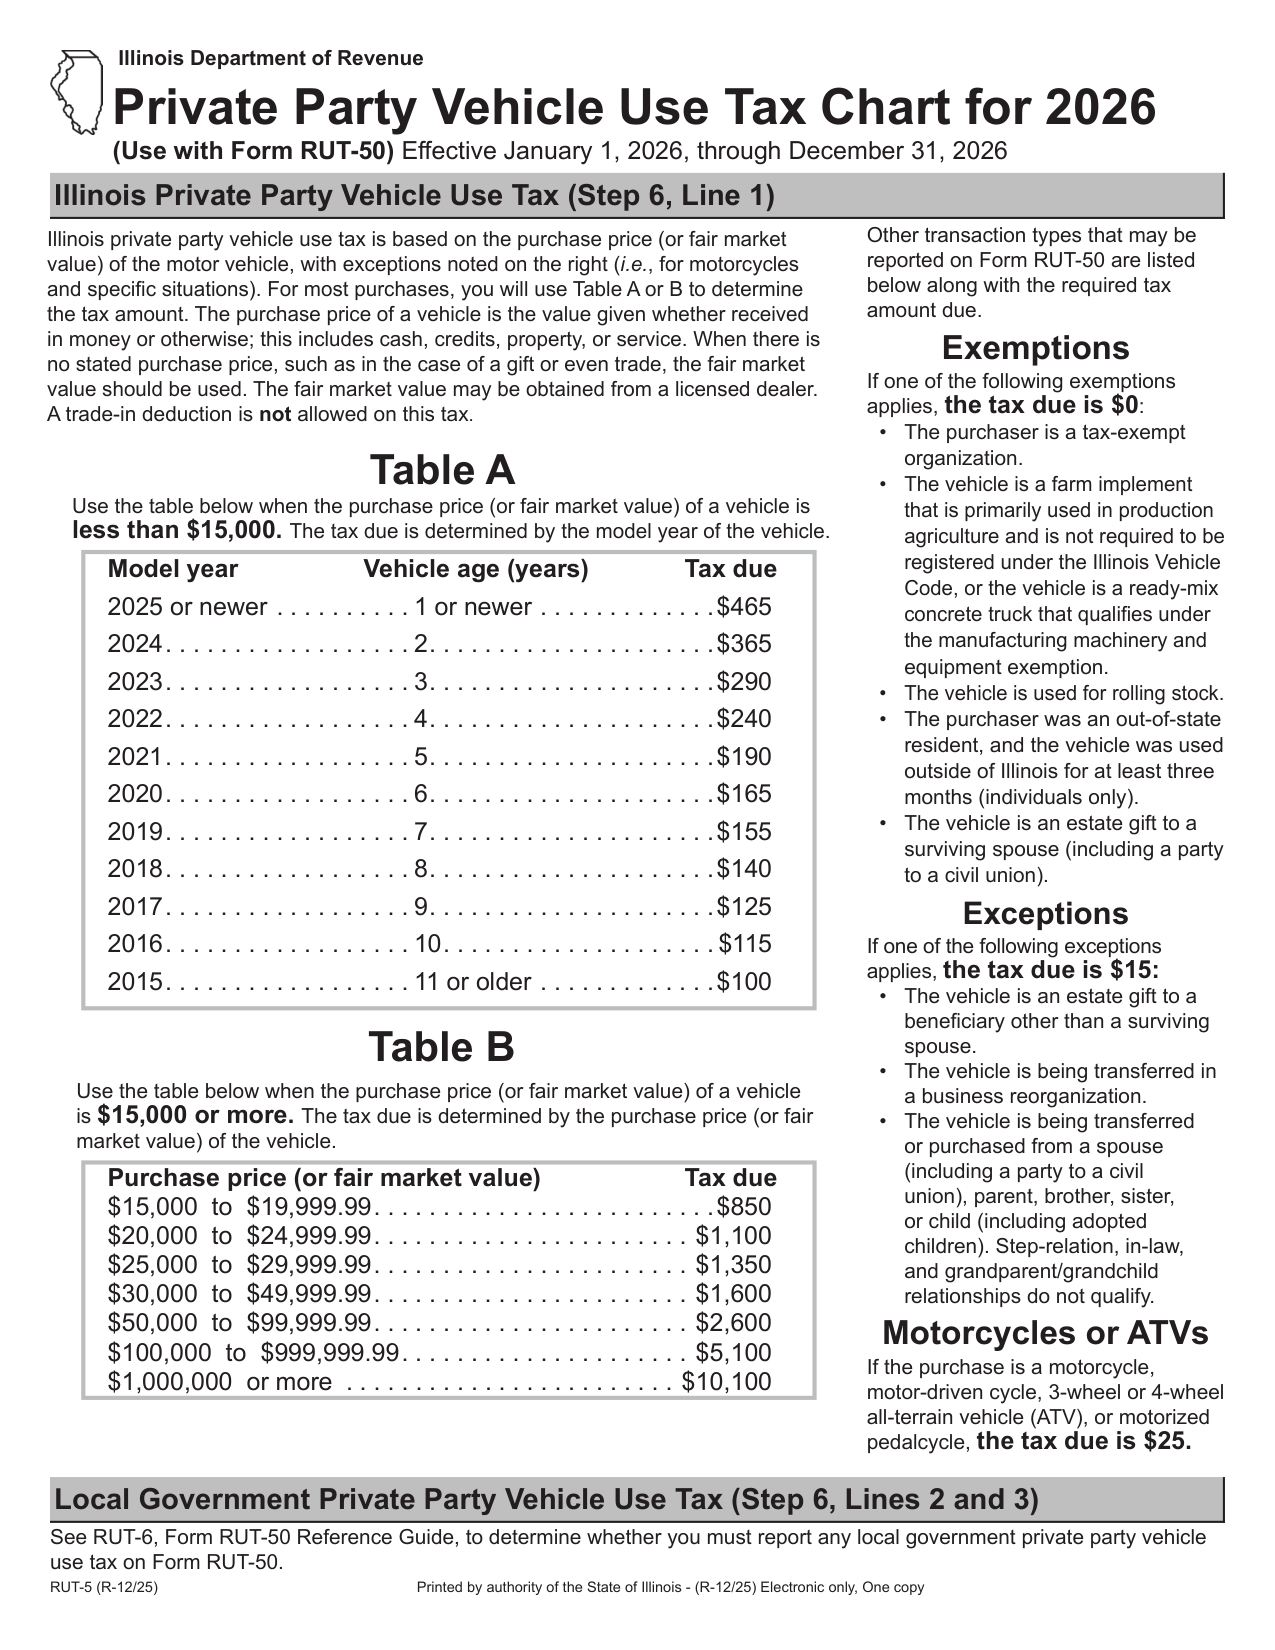
Illinois private party vehicle use tax is based on the purchase price (or fair market value) of the motor vehicle, with exceptions noted. For most purchases, you will use Table A or B to determine the tax amount. The purchase price of a vehicle is the value given whether received in money or otherwise; this includes cash, credits, property, or service. When there is no stated purchase price, such as in the case of a gift or even trade, the fair market value should be used. The fair market value may be obtained from a licensed dealer. A trade-in deduction is not allowed on this tax. Table A: Use Table A when the purchase price (or fair market value) of a vehicle is less than $15,000. The tax due is determined by the model year of the vehicle. Model year 2025 or newer, vehicle age 1 or newer: $465. 2024, 2: $365. 2023, 3: $290. 2022, 4: $240. 2021, 5: $190. 2020, 6: $165. 2019, 7: $155. 2018, 8: $140. 2017, 9: $125. 2016, 10: $115. 2015, 11 or older: $100. Table B: Use Table B when the purchase price (or fair market value) of a vehicle is $15,000 or more. The tax due is determined by the purchase price (or fair market value) of the vehicle. $15,000 to $19,999.99: $850. $20,000 to $24,999.99: $1,100. $25,000 to $29,999.99: $1,350. $30,000 to $49,999.99: $1,600. $50,000 to $99,999.99: $2,600. $100,000 to $999,999.99: $5,100. $1,000,000 or more: $10,100. Exemptions: If one of the following exemptions applies, the tax due is $0: The purchaser is a tax-exempt organization. The vehicle is a farm implement that is primarily used in production agriculture and is not required to be registered under the Illinois Vehicle Code, or the vehicle is a ready-mix concrete truck that qualifies under the manufacturing machinery and equipment exemption. The vehicle is used for rolling stock. The purchaser was an out-of-state resident, and the vehicle was used outside of Illinois for at least three months (individuals only). The vehicle is an estate gift to a surviving spouse (including a party to a civil union). Exceptions: If one of the following exceptions applies, the tax due is $15: The vehicle is an estate gift to a beneficiary other than a surviving spouse. The vehicle is being transferred in a business reorganization. The vehicle is being transferred or purchased from a spouse (including a party to a civil union), parent, brother, sister, or child (including adopted children). Step-relation, in-law, and grandparent/grandchild relationships do not qualify. Motorcycles or ATVs: If the purchase is a motorcycle, motor-driven cycle, 3-wheel or 4-wheel all-terrain vehicle (ATV), or motorized pedalcycle, the tax due is $25. (checked November 15, 2026)
Local Government Private Party Vehicle Use Tax
See RUT-6, Form RUT-50 Reference Guide, to determine whether you must report any local government private party vehicle use tax on Form RUT-50.
Sources
[1] Illinois Department of Revenue, Private Party Vehicle Use Tax Chart for 2026 (Use with Form RUT-50) (the Official source link on this page).
