

Form ST-9 at a glance
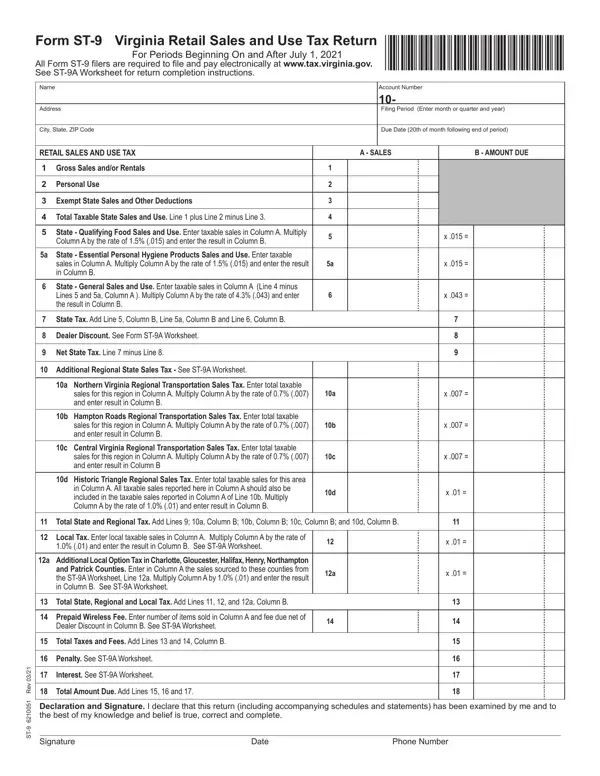
What it is: Form ST-9 is the Virginia Retail Sales and Use Tax Return for periods beginning on and after July 1, 2021.
Where and when to file: All ST-9 filers must file and pay electronically unless a request for a temporary waiver is approved. Return and payment are due on 20th of month following end of period.
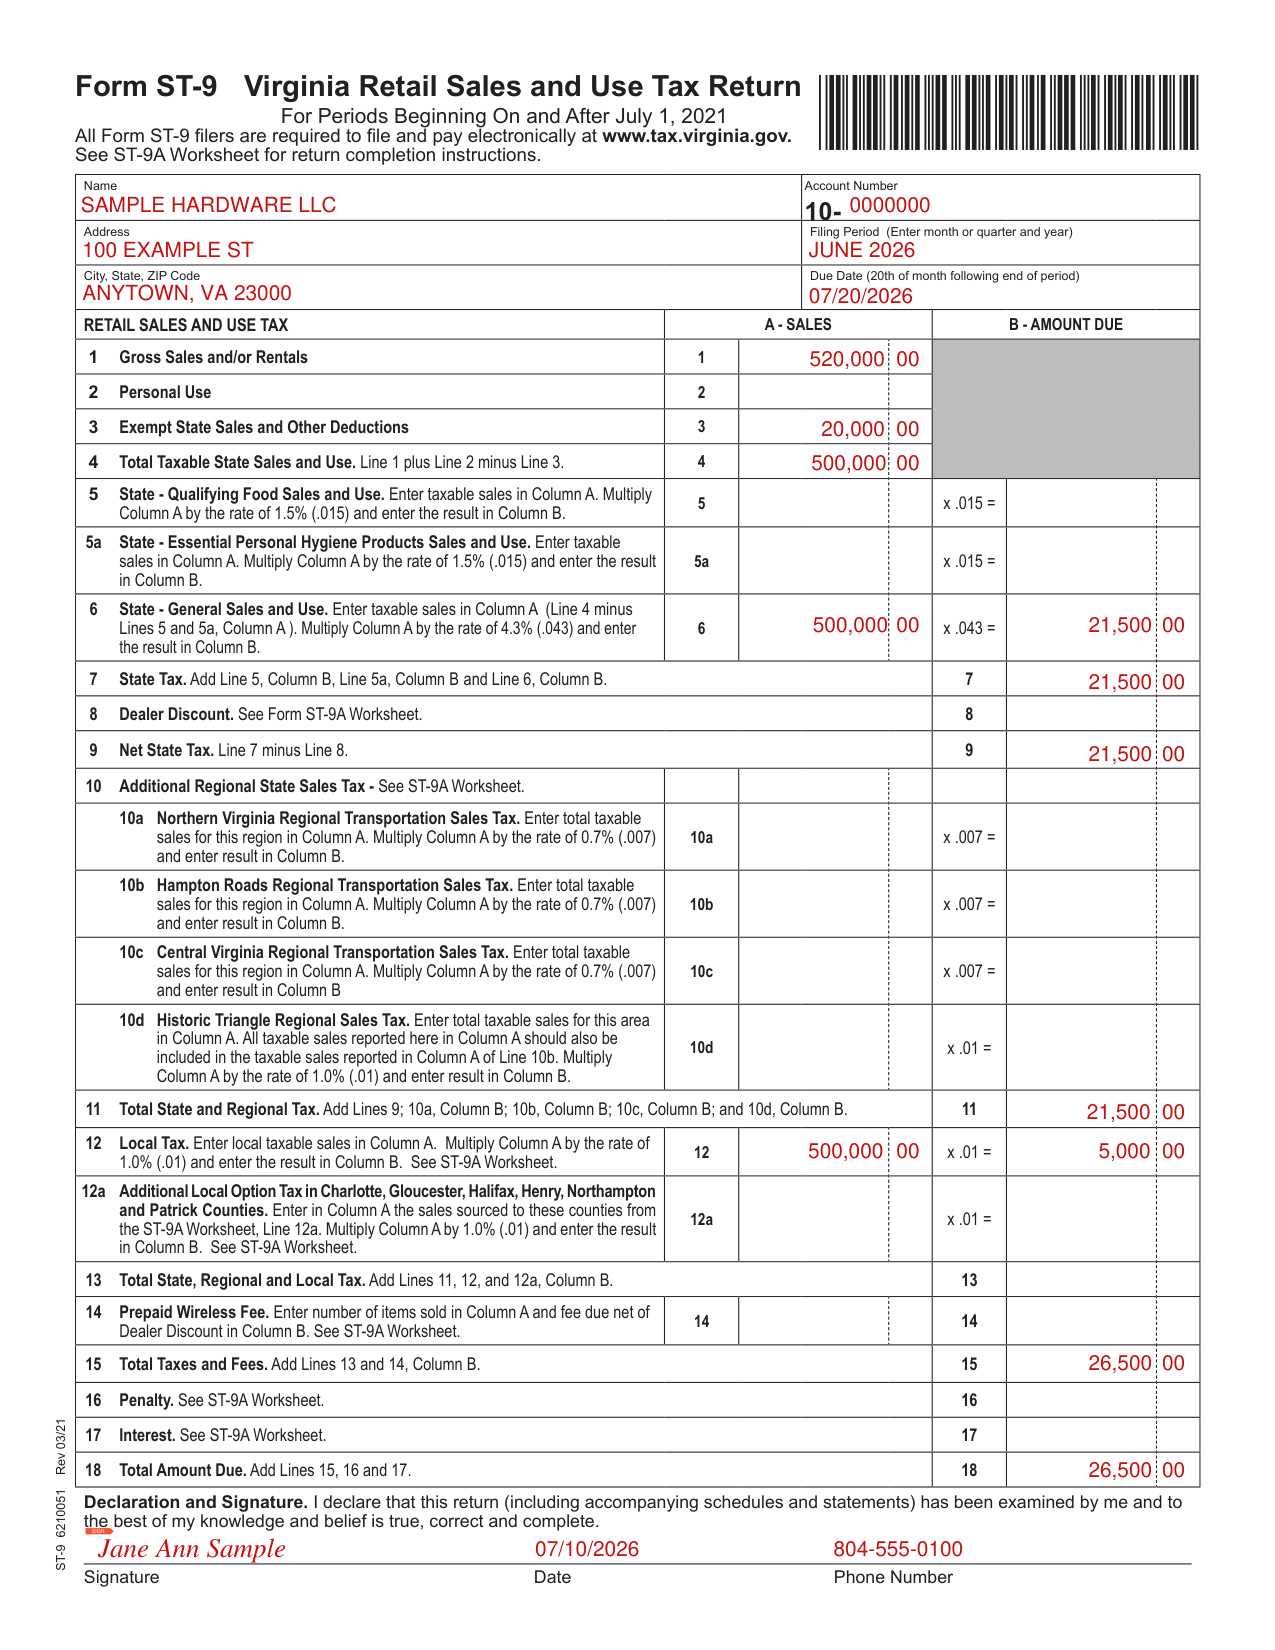
A filled-in Form ST-9 example: a hardware store's June return
How to fill out Form ST-9, box by box
Name, account number and filing period
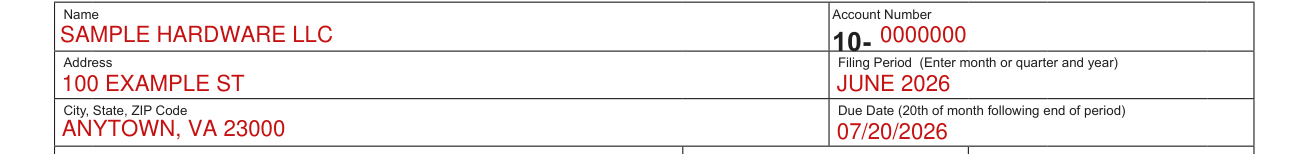
Enter the Name, Account Number, Address, City, State, ZIP Code, Filing Period (enter month or quarter and year) and Due Date (20th of month following end of period).
Lines 1 to 4: sales and deductions
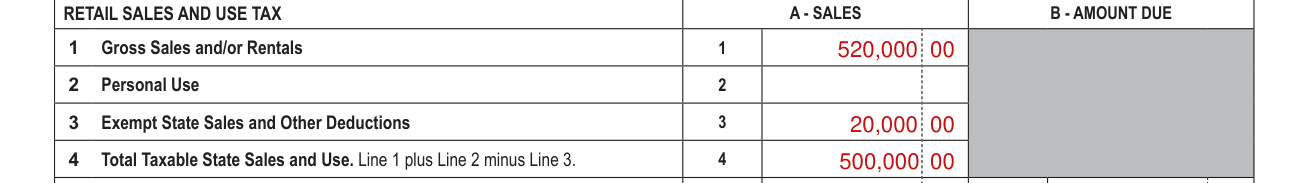
1 Gross Sales and/or Rentals. Enter the total gross dollar amount of items of tangible personal property and/or taxable services sold or leased during the period, whether for cash or on credit, including any services that were a part of a sale, but excluding the cost price of tangible personal property defined on Line 2. Do not include sales tax in your gross sales figure.
2 Personal Use. Enter the cost price of tangible personal property purchased without payment of sales tax and withdrawn from inventory for use or consumption and/or cost price of tangible personal property purchased either in or outside this state for dealer's own use or consumption on which no sales or use tax has been paid.
3 Exempt State Sales and Other Deductions. Enter the total of all exempt sales and other deductions that apply to the period covered by this return.
4 Total Taxable State Sales and Use. Line 1 plus Line 2 minus Line 3.
Lines 5 to 9: state tax and dealer discount
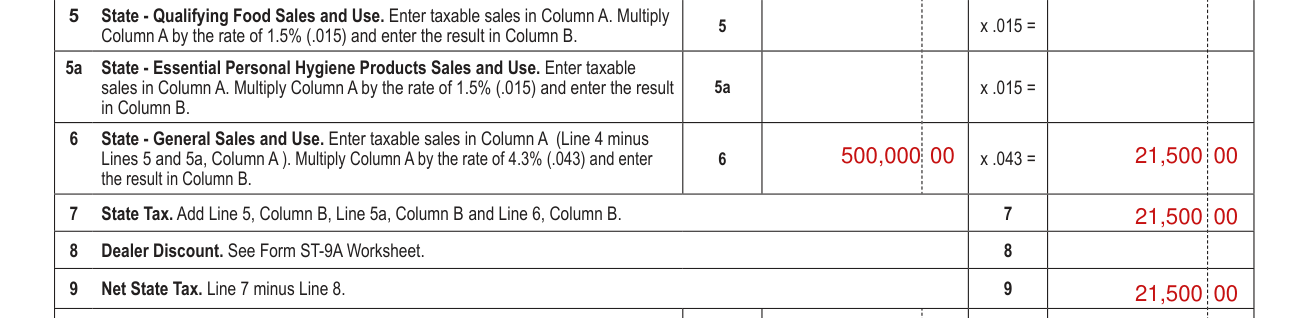
6 State - General Sales and Use. Enter taxable sales in Column A (Line 4 minus Lines 5 and 5a, Column A). Multiply Column A by the rate of 4.3% (.043) and enter the result in Column B.
5 State - Qualifying Food Sales and Use. 5a State - Essential Personal Hygiene Products Sales and Use. Enter taxable sales in Column A. Multiply Column A by the rate of 1.5% (.015) and enter the result in Column B.
7 State Tax. Add Line 5, Column B, Line 5a, Column B and Line 6, Column B.
A dealer discount may be taken only if the return and payment are submitted by the due date.
Any dealer whose average monthly sales tax liability exceeds $20,000 is not eligible for the discount (checked November 14, 2026).
The taxable sales on Line 4 is used to determine the RATE ONLY.
9 Net State Tax. Line 7 minus Line 8.
Line 10: regional sales tax
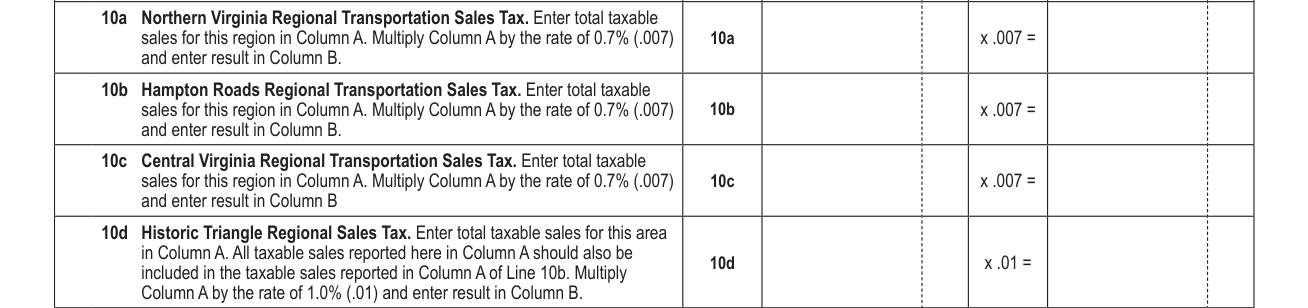
10 Additional Regional State Sales Tax. Complete Lines 10a, 10b, 10c and 10d if you have sales in any locality in the Northern Virginia, Hampton Roads, Central Virginia or Historic Triangle Regions.
10a Northern Virginia Regional Transportation Sales Tax. 10b Hampton Roads Regional Transportation Sales Tax. 10c Central Virginia Regional Transportation Sales Tax. Enter total taxable sales for this region in Column A. Multiply Column A by the rate of 0.7% (.007) and enter result in Column B.
10d Historic Triangle Regional Sales Tax. Enter total taxable sales for this area in Column A. All taxable sales reported here in Column A should also be included in the taxable sales reported in Column A of Line 10b. Multiply Column A by the rate of 1.0% (.01) and enter result in Column B.
Lines 11 to 14: local tax and prepaid wireless fee
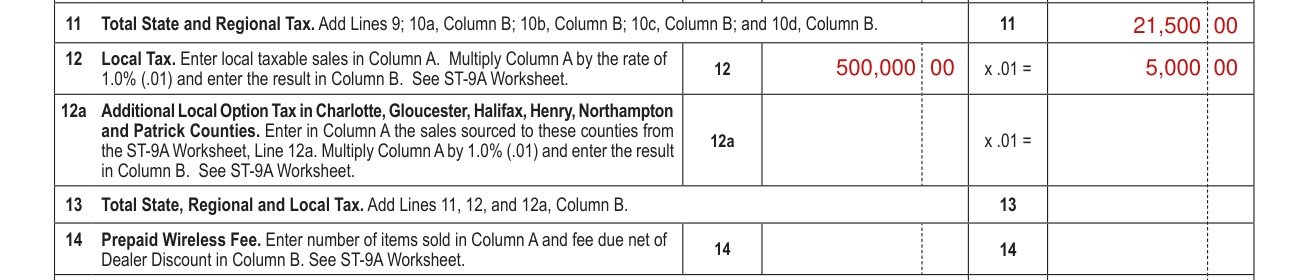
11 Total State and Regional Tax. Add Lines 9; 10a, Column B; 10b, Column B; 10c, Column B; and 10d, Column B.
12 Local Tax. Enter local taxable sales in Column A. Multiply Column A by the rate of 1.0% (.01) and enter the result in Column B. See ST-9A Worksheet.
Generally, the amount entered in Column A is the same as the taxable state sales and use amount.
12a Additional Local Option Tax in Charlotte, Gloucester, Halifax, Henry, Northampton and Patrick Counties. Enter in Column A the sales sourced to these counties from the ST-9A Worksheet, Line 12a. Multiply Column A by 1.0% (.01) and enter the result in Column B.
13 Total State, Regional and Local Tax. Add Lines 11, 12, and 12a, Column B.
14 Prepaid Wireless Fee. Enter number of items sold in Column A and fee due net of Dealer Discount in Column B. See ST-9A Worksheet.
Enter the number of items sold. Each separate retail purchase of a prepaid service is considered an item.
Lines 15 to 18 and the signature
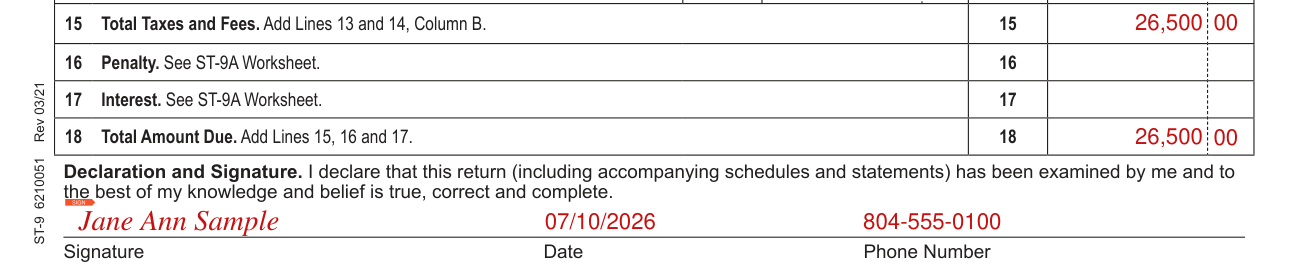
15 Total Taxes and Fees. Add Lines 13 and 14, Column B.
Penalty for late filing and payment equals 6% of Line 15 for each month or part of a month the tax is not paid, not to exceed 30%.
Interest is assessed on Line 15 at the rate established in Section 6621 of the Internal Revenue Code of 1954, as amended, plus 2%.
18 Total Amount Due. Add Lines 15, 16 and 17.
Declaration and Signature. "I declare that this return (including accompanying schedules and statements) has been examined by me and to the best of my knowledge and belief is true, correct and complete."
SIGN Signature Date Phone Number
More rules for Form ST-9
For assistance, call (804) 367-8037.
Transfer lines from the worksheet to the corresponding line number on Form ST-9.
Worksheet is for your records only. Do not mail.
Download a waiver from the Department's website.
Write to Virginia Department of Taxation, P.O. Box 1115, Richmond, VA 23218-1115.
If your situation is different
You report consolidated sales or have no fixed business location
If you are reporting consolidated sales for business locations in more than one locality or you do not have a fixed location for your business, file Form ST-9B with Form ST-9 to allocate sales to the appropriate Virginia locality.
If you are filing a consolidated return or reporting sales for a non-fixed business location, you must also complete Form ST-9B to report sales sourced to Virginia localities.
You pay by check
If paying by check, enter the total amount due from Form ST-9 on the Voucher, Form ST-9V, and enclose this voucher and your check with your return. Make your check payable to the Department of Taxation.
Common questions about Form ST-9
Is there a deadline?
Return and payment are due on 20th of month following end of period.
Where do I file it?
All ST-9 filers must file and pay electronically unless a request for a temporary waiver is approved.
Sources
[1] Form ST-9 (Rev 03/21), Virginia Department of Taxation (the Official source link on this page).