


Canada T2 at a glance
What it is: The T2 Corporation Income Tax Return (2025 and later tax years) is a corporation income tax return.
Who signs: Enter the Last name, First name, and Position, office, or rank of an authorized signing officer of the corporation.
A filled-in Canada T2 example: a bookkeeper fills in page one
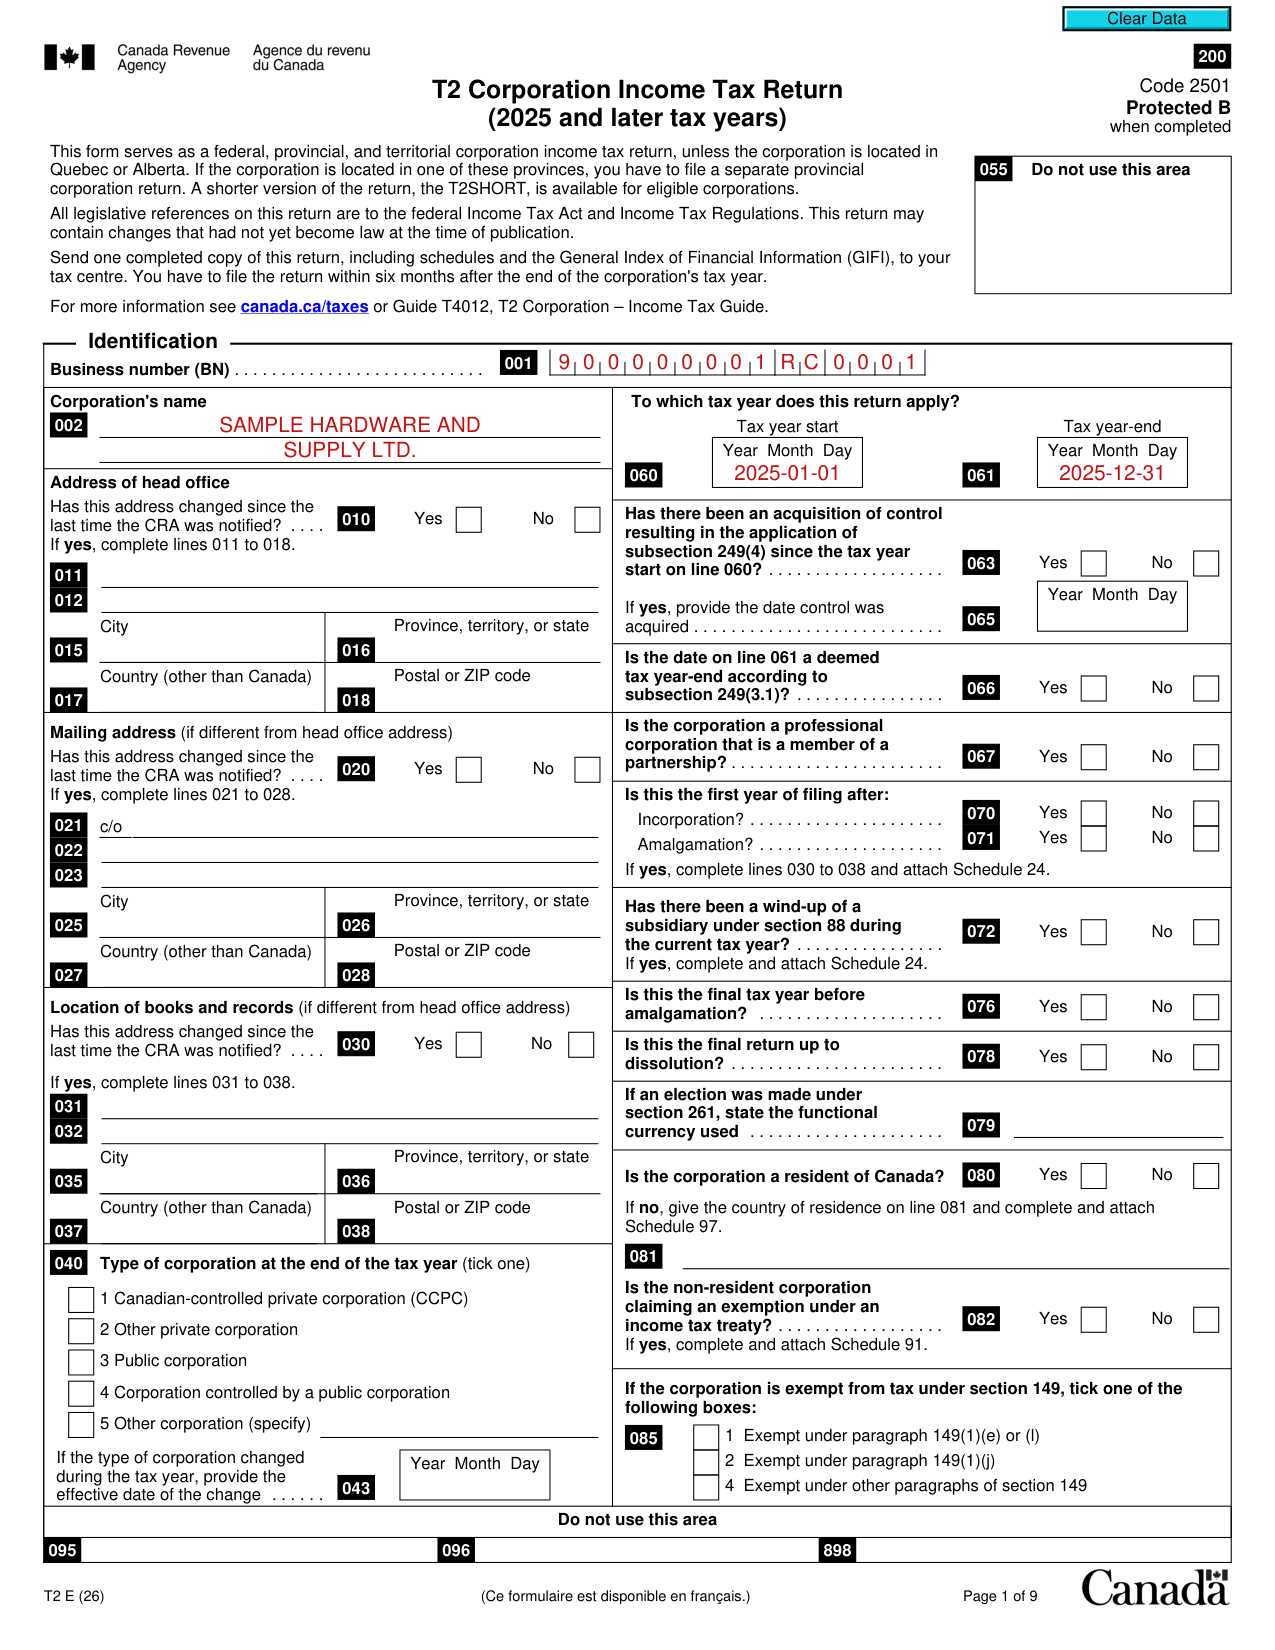
How to fill out Canada T2, box by box
Corporation Income Tax Return
This form serves as a federal, provincial, and territorial corporation income tax return, unless the corporation is located in Quebec or Alberta. If the corporation is located in one of these provinces, you have to file a separate provincial corporation return. A shorter version of the return, the T2SHORT, is available for eligible corporations. All legislative references on this return are to the federal Income Tax Act and Income Tax Regulations. This return may contain changes that had not yet become law at the time of publication. Send one completed copy of this return, including schedules and the General Index of Financial Information (GIFI), to your tax centre. You have to file the return within six months after the end of the corporation's tax year.
Identification
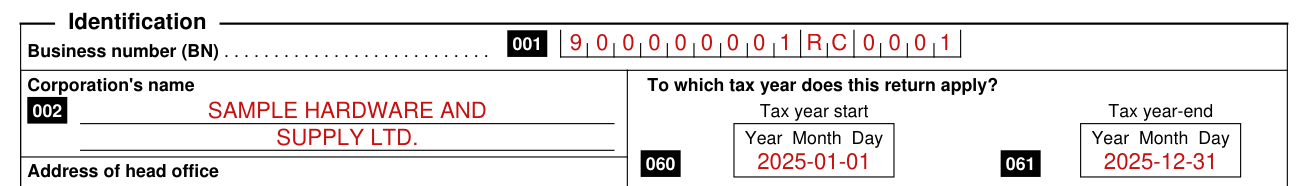
Enter the Business number (BN) on line 001 and the Corporation's name on line 002.
To which tax year does this return apply? Enter the Tax year start and the Tax year-end, each as Year Month Day.
Type of corporation
On line 040, Type of corporation at the end of the tax year, tick one: 1 Canadian-controlled private corporation (CCPC), 2 Other private corporation, 3 Public corporation, 4 Corporation controlled by a public corporation, or 5 Other corporation (specify).
If the type of corporation changed during the tax year, provide the effective date of the change.
Is the corporation a resident of Canada?
Line 080, Is the corporation a resident of Canada? Yes or No. If no, give the country of residence on line 081 and complete and attach Schedule 97.
Attachments
Schedules - Answer the following questions. For each yes response, attach the schedule to the T2 return, unless otherwise instructed.
Financial statement information: Use GIFI schedules 100, 125, and 141.
On line 255, Is the corporation subject to Part XIII.1 tax? Show your calculations on a sheet that you identify as Schedule 92.
Additional information
Specify the principal products mined, manufactured, sold, constructed, or services provided, giving the approximate percentage of the total revenue that each product or service represents.
Taxable income
On line 300, A, enter the Net income or (loss) for income tax purposes from Schedule 1, financial statements, or GIFI.
Deduct: 311 Charitable donations from Schedule 2; 313 Cultural gifts from Schedule 2; 314 Ecological gifts from Schedule 2; 320 Taxable dividends deductible under section 112 or 113, or subsection 138(6) from Schedule 3; 325 Part VI.1 tax deduction.
Deduct: 331 Non-capital losses of previous tax years from Schedule 4; 332 Net capital losses of previous tax years from Schedule 4; 333 Restricted farm losses of previous tax years from Schedule 4.
Deduct: 334 Farm losses of previous tax years from Schedule 4; 335 Limited partnership losses of previous tax years from Schedule 4; 336 Restricted interest and financing expenses from Schedule 4.
Deduct: 340 Taxable capital gains or taxable dividends allocated from a central credit union; 350 Prospector's and grubstaker's shares; 352 Employer deduction for non-qualified securities.
The Part VI.1 tax deduction on line 325 is equal to 3.5 times the Part VI.1 tax payable at line 724 on page 9.
B is the Subtotal. C, Subtotal, is amount A minus amount B (if negative, enter "0"). On line 355, D, enter the Section 110.5 additions or subparagraph 115(1)(a)(vii) additions. Line 360, Taxable income, is amount C plus amount D.
Small business deduction
For CCPCs that are not associated, enter $500,000 on line 410. However, if the corporation's tax year is less than 51 weeks, prorate this amount by the number of days in the tax year divided by 365, and enter the result on line 410. (checked October 22, 2026)
For associated CCPCs, use Schedule 23 to calculate the amount to be entered on line 410.
Line 430, Small business deduction, is Amount A, B, C, or K, whichever is the least, × 19%. Enter amount from line 430 at amount L on page 8.
Part I tax
On line 550, A, Base amount Part I tax is Taxable income (from line 360 on page 3) multiplied by 38%.
N, Part I tax payable, is amount K minus amount M. Enter amount N on line 700 on page 9.
Summary of tax and credits
Add provincial or territorial tax: 750 Provincial or territorial jurisdiction (if more than one jurisdiction, enter "multiple" and complete Schedule 5) and 760 Net provincial or territorial tax payable (except Quebec and Alberta).
The Balance is amount A minus amount B. If the result is negative, you have a refund. If the result is positive, you have a balance owing. Enter the amount on whichever line applies.
Generally, the CRA does not charge or refund a difference of $2 or less. (checked October 22, 2026)
For information on how to enrol for direct deposit, go to canada.ca/cra-direct-deposit. For information on how to make your payment, go to canada.ca/payments.
Line 896: If the corporation is a Canadian-controlled private corporation throughout the tax year, does it qualify for the one-month extension of the date the balance of tax is due? Yes or No.
If the return was prepared by a tax preparer for a fee, provide their 920 EFILE number and 925 RepID.
Certification
Enter the Last name, First name, and Position, office, or rank of an authorized signing officer of the corporation.
I certify that I have examined this return, including accompanying schedules and statements, and that the information given on this return is, to the best of my knowledge, correct and complete.
I also certify that the method of calculating income for this tax year is consistent with that of the previous tax year except as specifically disclosed in a statement attached to this return.
Enter the Date (yyyy/mm/dd) and the Signature of the authorized signing officer of the corporation.
Enter the Telephone number. On line 957, if the contact person is not the same as the authorized signing officer, complete the information below: the Name of other authorized person and the Telephone number.
Language of correspondence
On line 990, indicate your language of correspondence by entering 1 for English or 2 for French.
More rules for Canada T2
For more information see canada.ca/taxes or Guide T4012, T2 Corporation - Income Tax Guide.
Common questions about Canada T2
Is there a penalty?
Failure to provide the personal information collected may result in paying interest or penalties, or in other actions.
Sources
[1] T2 E (26), T2 Corporation Income Tax Return (2025 and later tax years), Canada Revenue Agency (the Official source link on this page).