
Updated:
Get Form Now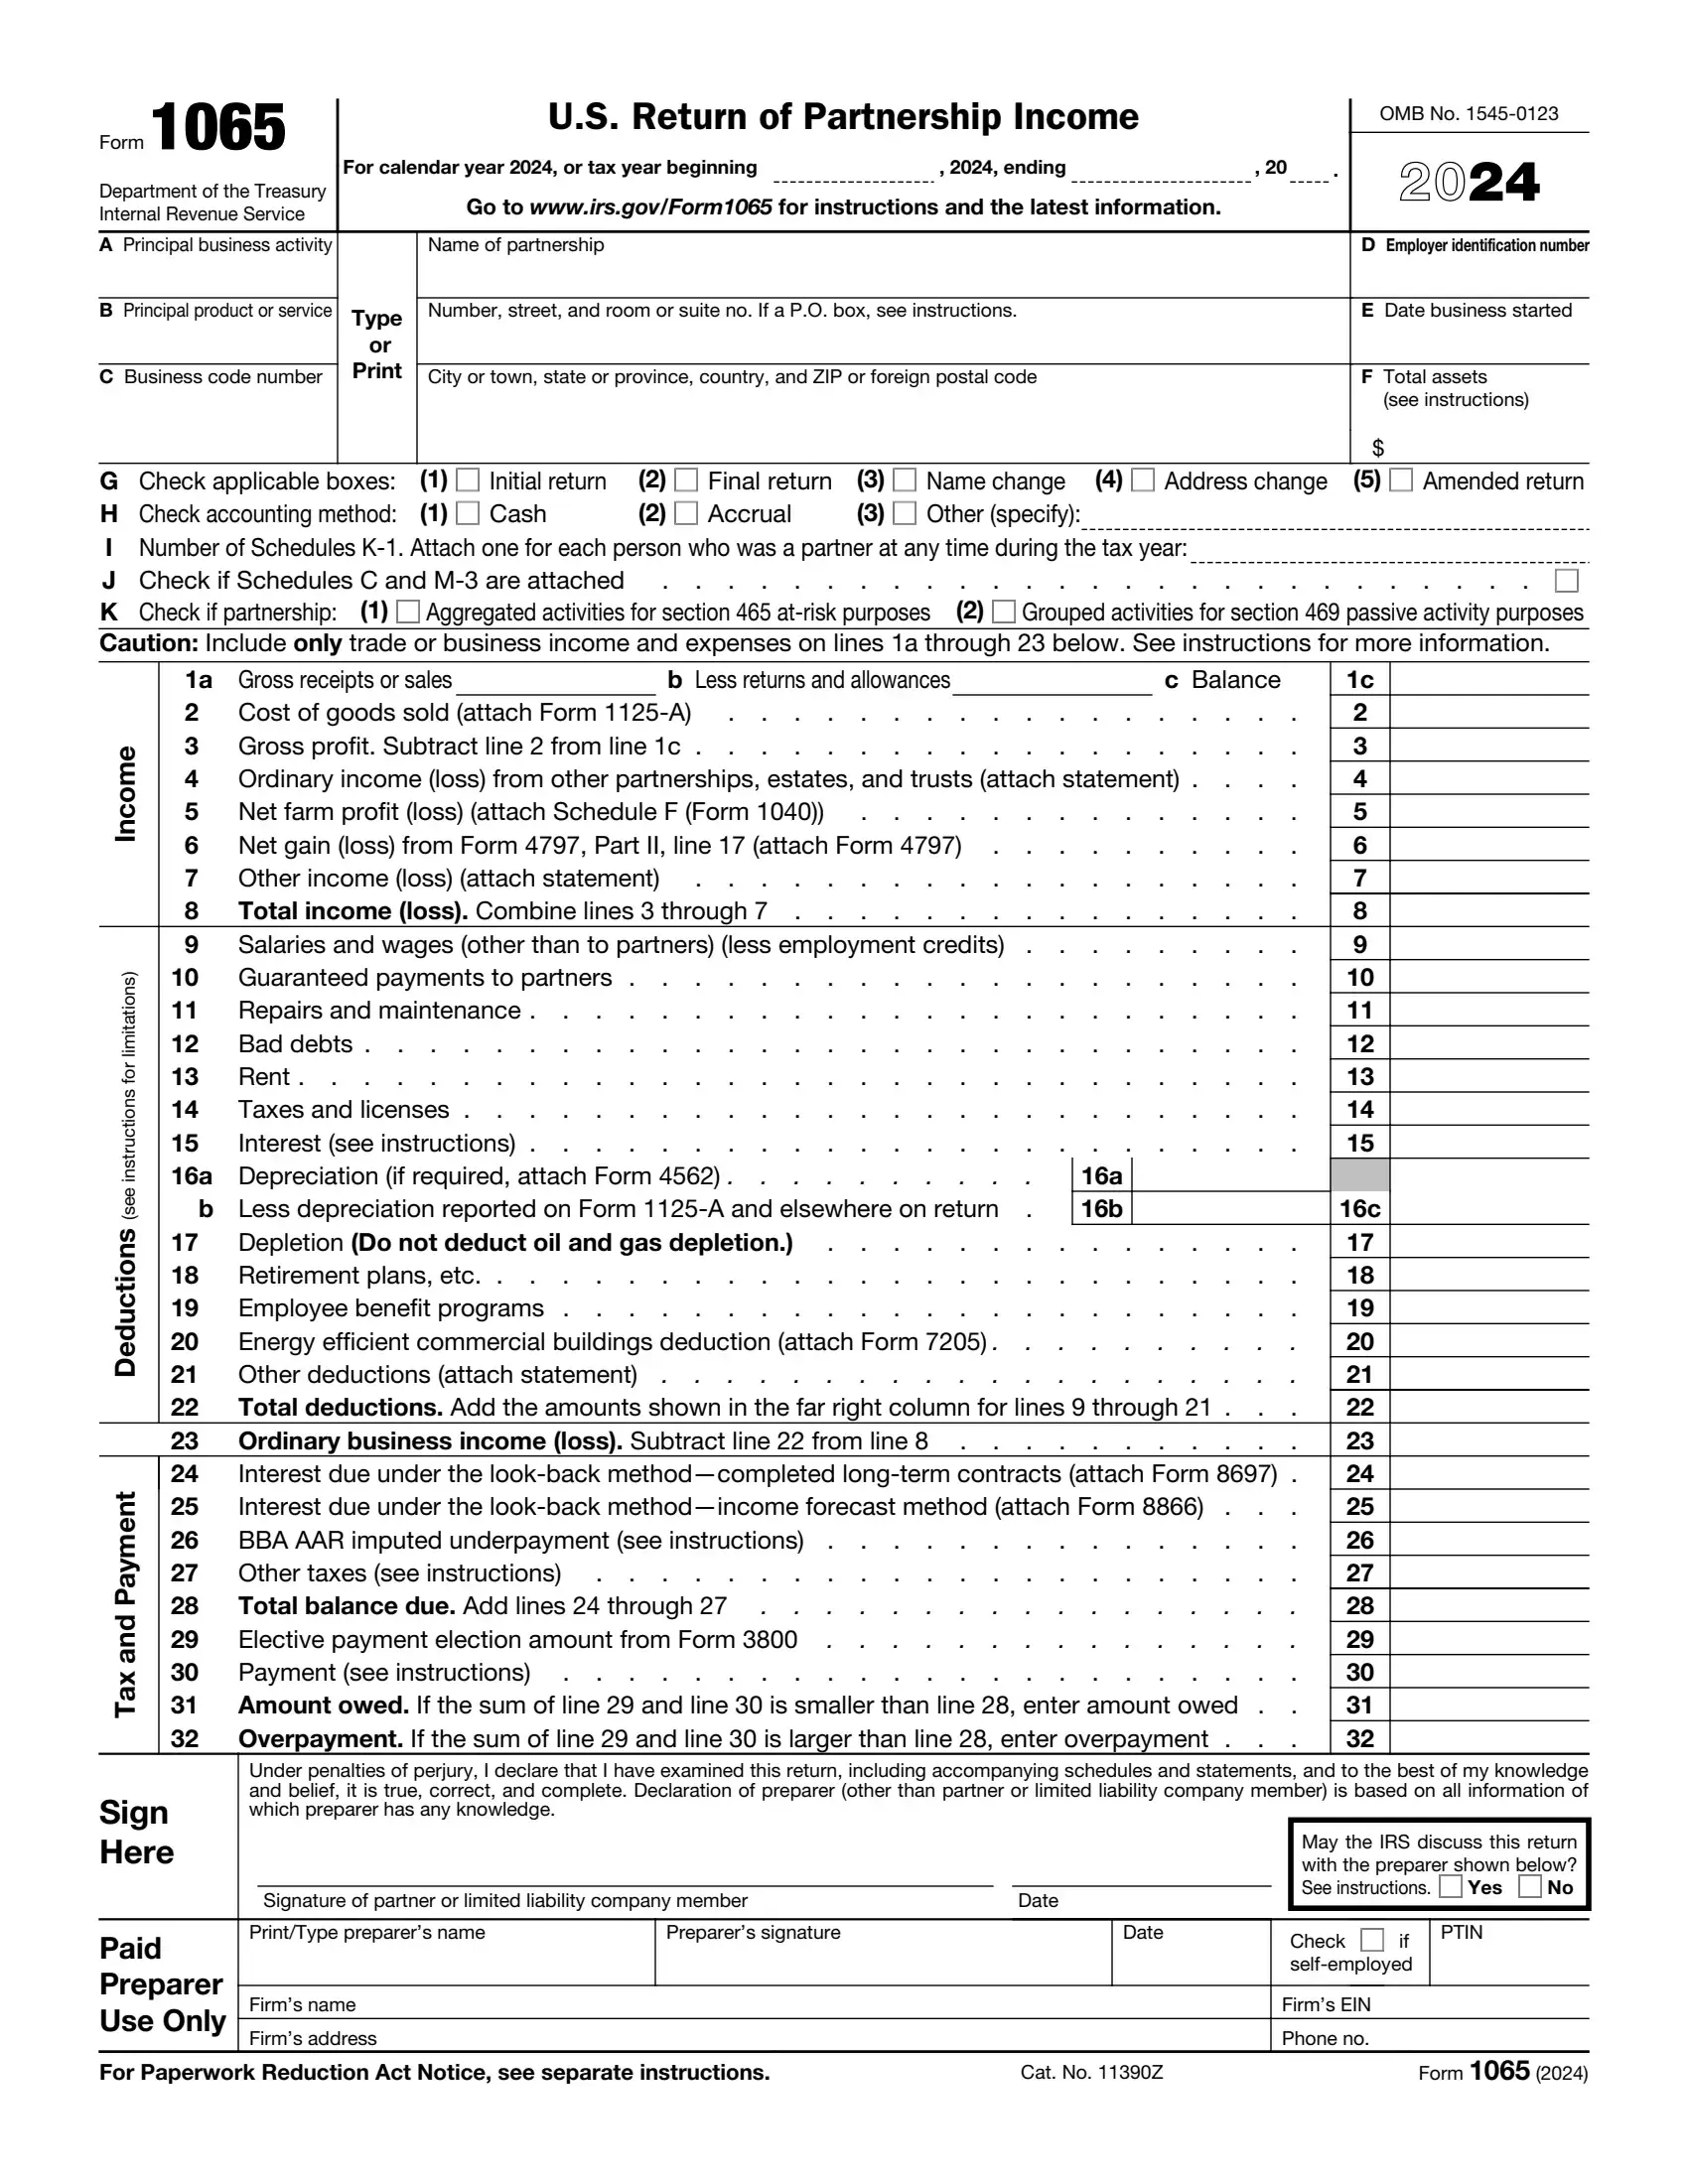
Form 1065, titled “U.S. Return of Partnership Income,” is a tax form used by partnerships to report their financial information to the Internal Revenue Service (IRS). This form details the partnership’s income, gains, losses, deductions, credits, and other financial data. It is essential for partnerships as it helps determine the share of income or loss each partner should report on their tax returns. Form 1065 is critical because it ensures that all income earned through the partnership is properly reported and taxed, avoiding discrepancies in individual partners’ filings.
The purpose of Form 1065 is to report income and provide a transparent mechanism for allocating the partnership’s income and losses among its partners according to their partnership agreement. Each partner receives a Schedule K-1 from the Form 1065 filing, which breaks down their share of the partnership’s financial activities. The partners then use this schedule to fill out their tax returns. Through Form 1065, the IRS ensures that partnerships adhere to tax laws and regulations, allowing for the consistent and accurate reporting of income and deductions across multiple stakeholders involved in the partnership.
Other IRS Forms for Partnerships
Partnerships registered and doing business within the US must report essential information with regard to their finances through the Form 1065. Learn more about other important IRS forms for partnerships.
What it is: Form 1065, U.S. Return of Partnership Income, is an information return used to report the income, gains, losses, deductions, credits, and other information from the operation of a partnership.[2]
Who signs: Form 1065 isn't considered to be a return unless it's signed by a partner or LLC member.[2]
Tax deadline: For calendar-year partnerships, the due date is March 15.[2]
Except as provided in Who Must File, every domestic partnership must file Form 1065, unless it neither receives income nor incurs any expenditures treated as deductions or credits for federal income tax purposes.[2]
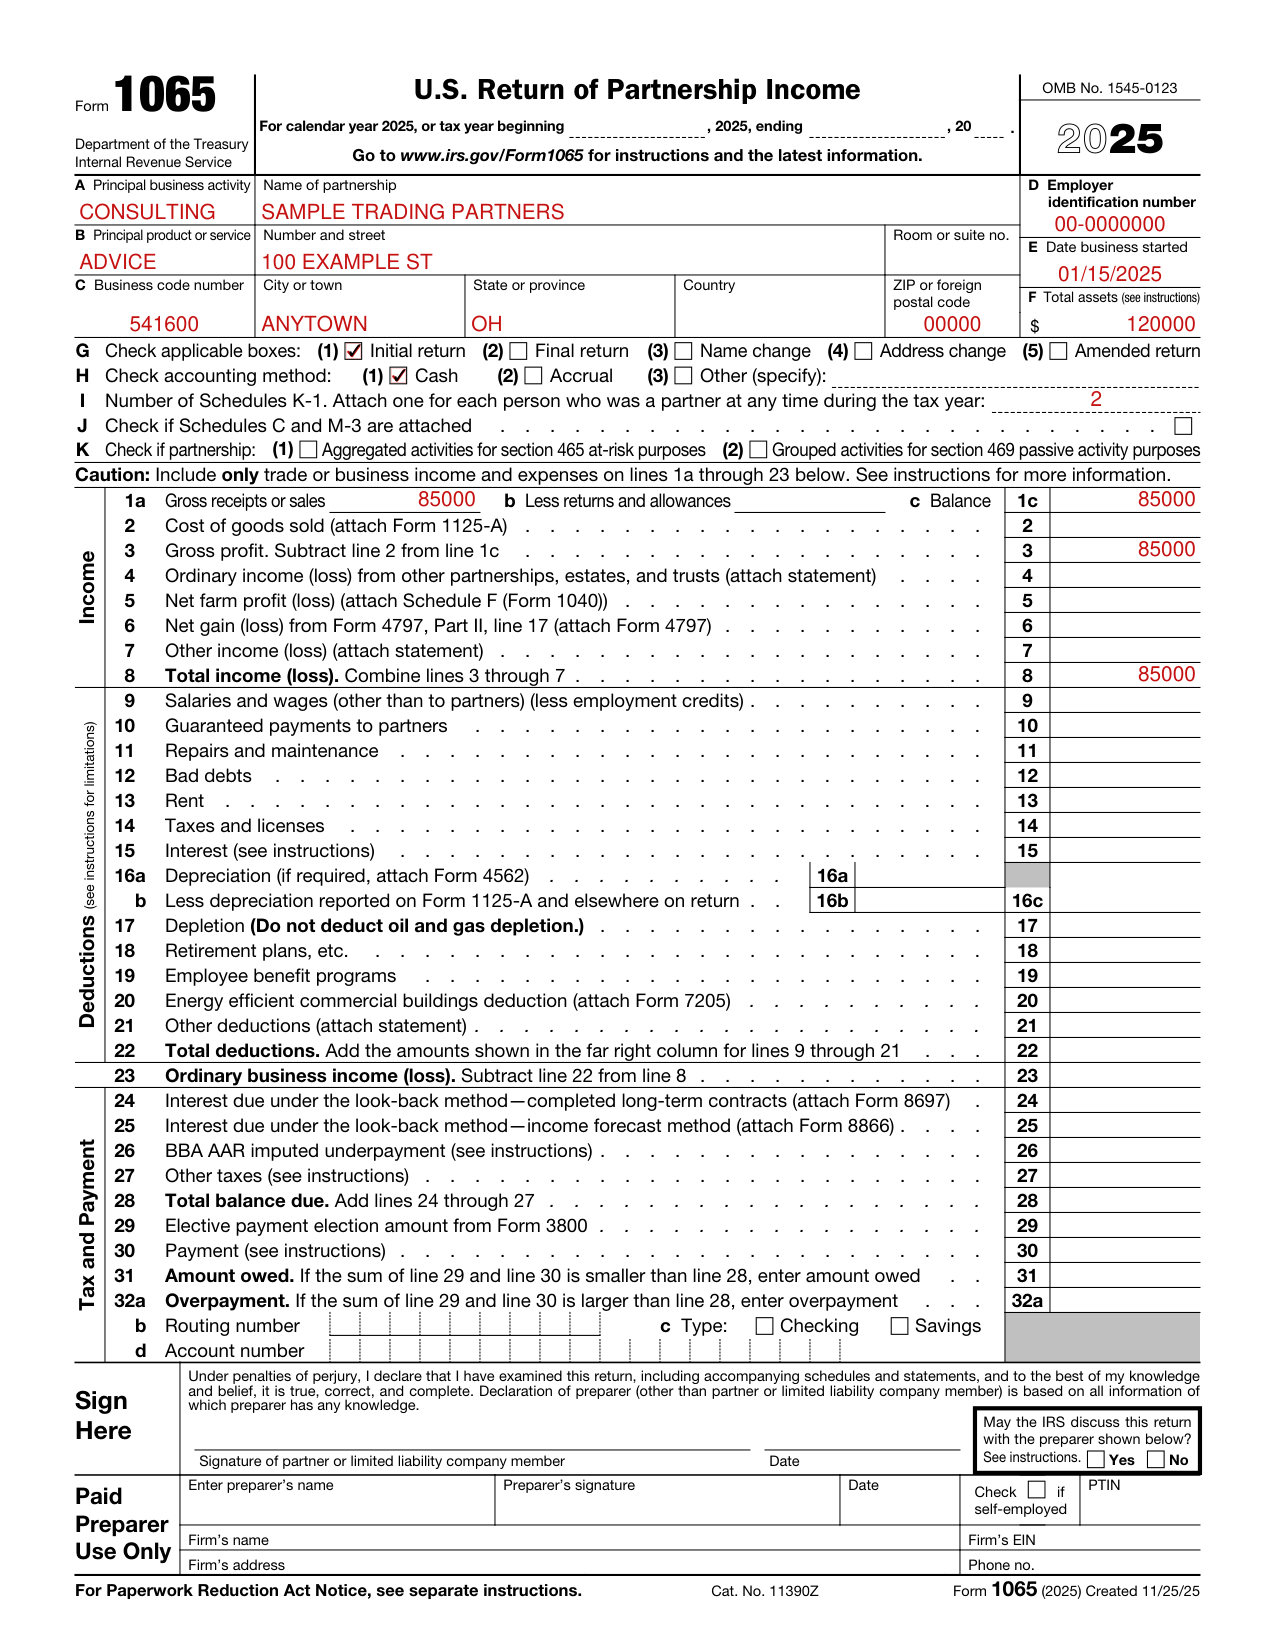
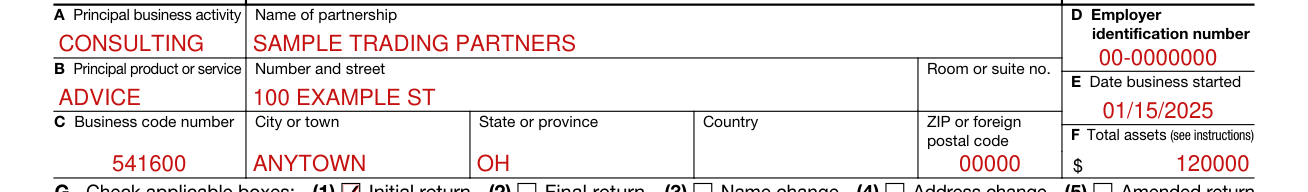
Enter the legal name of the partnership, address, and EIN on the appropriate lines.
Include the suite, room, or other unit number after the street address.
If the post office doesn't deliver mail to the street address and the partnership has a P.O. box, show the box number instead.[2]
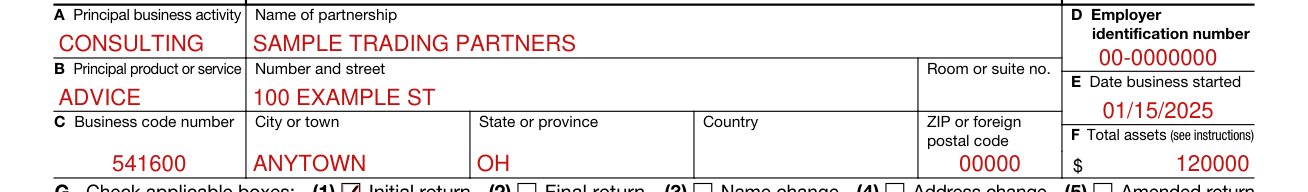
Enter the applicable activity name and the code number from the list, Codes for Principal Business Activity and Principal Product or Service.[2]

Show the correct EIN in item D.
If the partnership doesn't have an EIN, it must apply for one online at IRS.gov/EIN or by mailing or faxing Form SS-4, Application for Employer Identification Number.
If the partnership hasn't received its EIN by the time the return is due, enter “Applied for” and the application date in the space for the EIN.[2]

You aren't required to complete item F if the answer to Schedule B, question 4, is “Yes.”
If you're required to complete this item, enter the partnership's total assets at the end of the tax year, as determined by the accounting method regularly used in keeping the partnership's books and records.
If there were no assets at the end of the tax year, enter zero.[2]

If the partnership has changed its name, check box G(3).
If the partnership has changed its address since it last filed a return (including a change to an “in care of” address), check box G(4) for “Address change.”
If the amended return will be filed electronically, complete Form 1065 and check box G(5) to indicate that you're filing an amended return.[2]
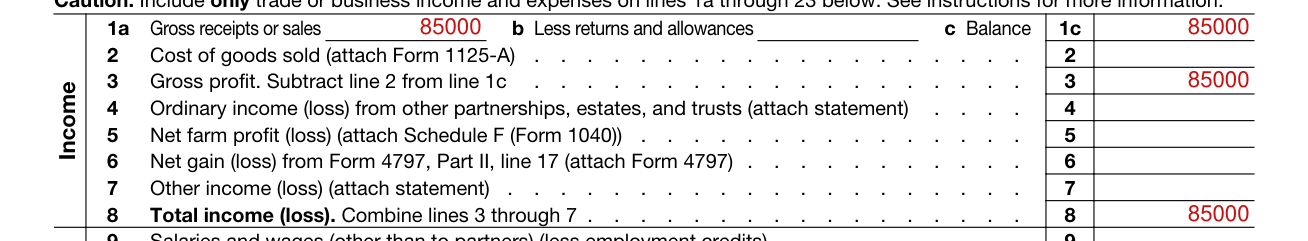
Report only trade or business activity income on lines 1a through 8.
Don't report rental activity income or portfolio income on these lines.
Enter on line 1a gross receipts or sales from all trade or business operations, except for amounts that must be reported on lines 4 through 7.[2]
Under penalties of perjury, I declare that I have examined this return, including accompanying schedules and statements, and to the best of my knowledge and belief, it is true, correct, and complete. Declaration of preparer (other than partner or limited liability company member) is based on all information of which preparer has any knowledge.
When a return is made for a partnership by a receiver, trustee, or assignee, the fiduciary must sign the return, instead of the partner or LLC member.
In the case of an entity partner, an individual who is authorized under state law to act for the entity partner must sign the partnership return.
If a partner, member, or employee of the partnership completes Form 1065, the paid preparer's space should remain blank.
If the partnership wants to allow the paid preparer to discuss its 2025 Form 1065 with the IRS, check “Yes” in the signature area of the return.[2]
Generally, a domestic partnership must file Form 1065 by the 15th day of the 3rd month following the date its tax year ended as shown at the top of Form 1065.
If the due date falls on a Saturday, Sunday, or legal holiday in the District of Columbia or the state in which you file your return, a return filed by the next day that isn't a Saturday, Sunday, or legal holiday will be treated as timely.
Calendar-year partnerships may therefore timely file their returns for the 2025 partnership year by March 16, 2026.
File Form 7004, Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns, to request an extension of time to file. File Form 7004 by the regular due date of the partnership return. Form 7004 can be electronically filed.[2]
If Schedule M-3 is filed, Form 1065 must be filed at the Ogden Internal Revenue Service Center.
If the partnership's principal business, office, or agency is located in Connecticut, Delaware, District of Columbia, Georgia, Illinois, Indiana, Kentucky, Maine, Maryland, Massachusetts, Michigan, New Hampshire, New Jersey, New York, North Carolina, Ohio, Pennsylvania, Rhode Island, South Carolina, Tennessee, Vermont, Virginia, West Virginia, Wisconsin and the total assets at the end of the tax year (Form 1065, page 1, item F) are less than $10 million and Schedule M-3 isn't filed, use Department of the Treasury Internal Revenue Service Center Kansas City, MO 64999-0011; if the total assets are $10 million or more or less than $10 million and Schedule M-3 is filed, use Department of the Treasury Internal Revenue Service Center Ogden, UT 84201-0011 (checked October 26, 2026). If the partnership's principal business, office, or agency is located in Alabama, Alaska, Arizona, Arkansas, California, Colorado, Florida, Hawaii, Idaho, Iowa, Kansas, Louisiana, Minnesota, Mississippi, Missouri, Montana, Nebraska, Nevada, New Mexico, North Dakota, Oklahoma, Oregon, South Dakota, Texas, Utah, Washington, Wyoming and the total assets at the end of the tax year (Form 1065, page 1, item F) are any amount, use Department of the Treasury Internal Revenue Service Center Ogden, UT 84201-0011.[2]
A penalty is assessed against the partnership if it's required to file a partnership return and it (a) fails to file the return by the due date, including extensions; or (b) files a return that fails to show all the information required, unless such failure is due to reasonable cause. The penalty is $255 for each month or part of a month (for a maximum of 12 months) the failure continues, multiplied by the total number of persons who were partners in the partnership during any part of the partnership's tax year for which the return is due (checked October 26, 2026).[2]
File all six pages of Form 1065.[2]
Attach a Schedule K-1 to Form 1065 for each partner.[2]
Beginning in 2024, partnerships were required to file Form 1065 and related forms and schedules electronically if they file 10 or more returns of any type during the tax year, including information, income tax, employment tax, and excise tax returns.
Partnerships with more than 100 partners are required to file Form 1065, Schedules K-1, and other related forms and schedules electronically.[2]
20. Was the partnership a specified domestic entity required to file Form 8938 for the tax year? See the Instructions for Form 8938.
Entities formed as LLCs that are classified as partnerships for federal income tax purposes have the same filing requirements as domestic partnerships. A domestic LLC with at least two members that doesn't file Form 8832 is classified as a partnership for federal income tax purposes.[2]
Generally, a partnership doesn't pay tax on its income but passes through any profits or losses to its partners. Partners must include partnership items on their tax or information returns.[2]
[1] Form 1065 (2025), U.S. Return of Partnership Income, Internal Revenue Service (the Official source link on this page).
[2] Instructions for Form 1065 (2025), Internal Revenue Service.