
Updated:
Get Form Now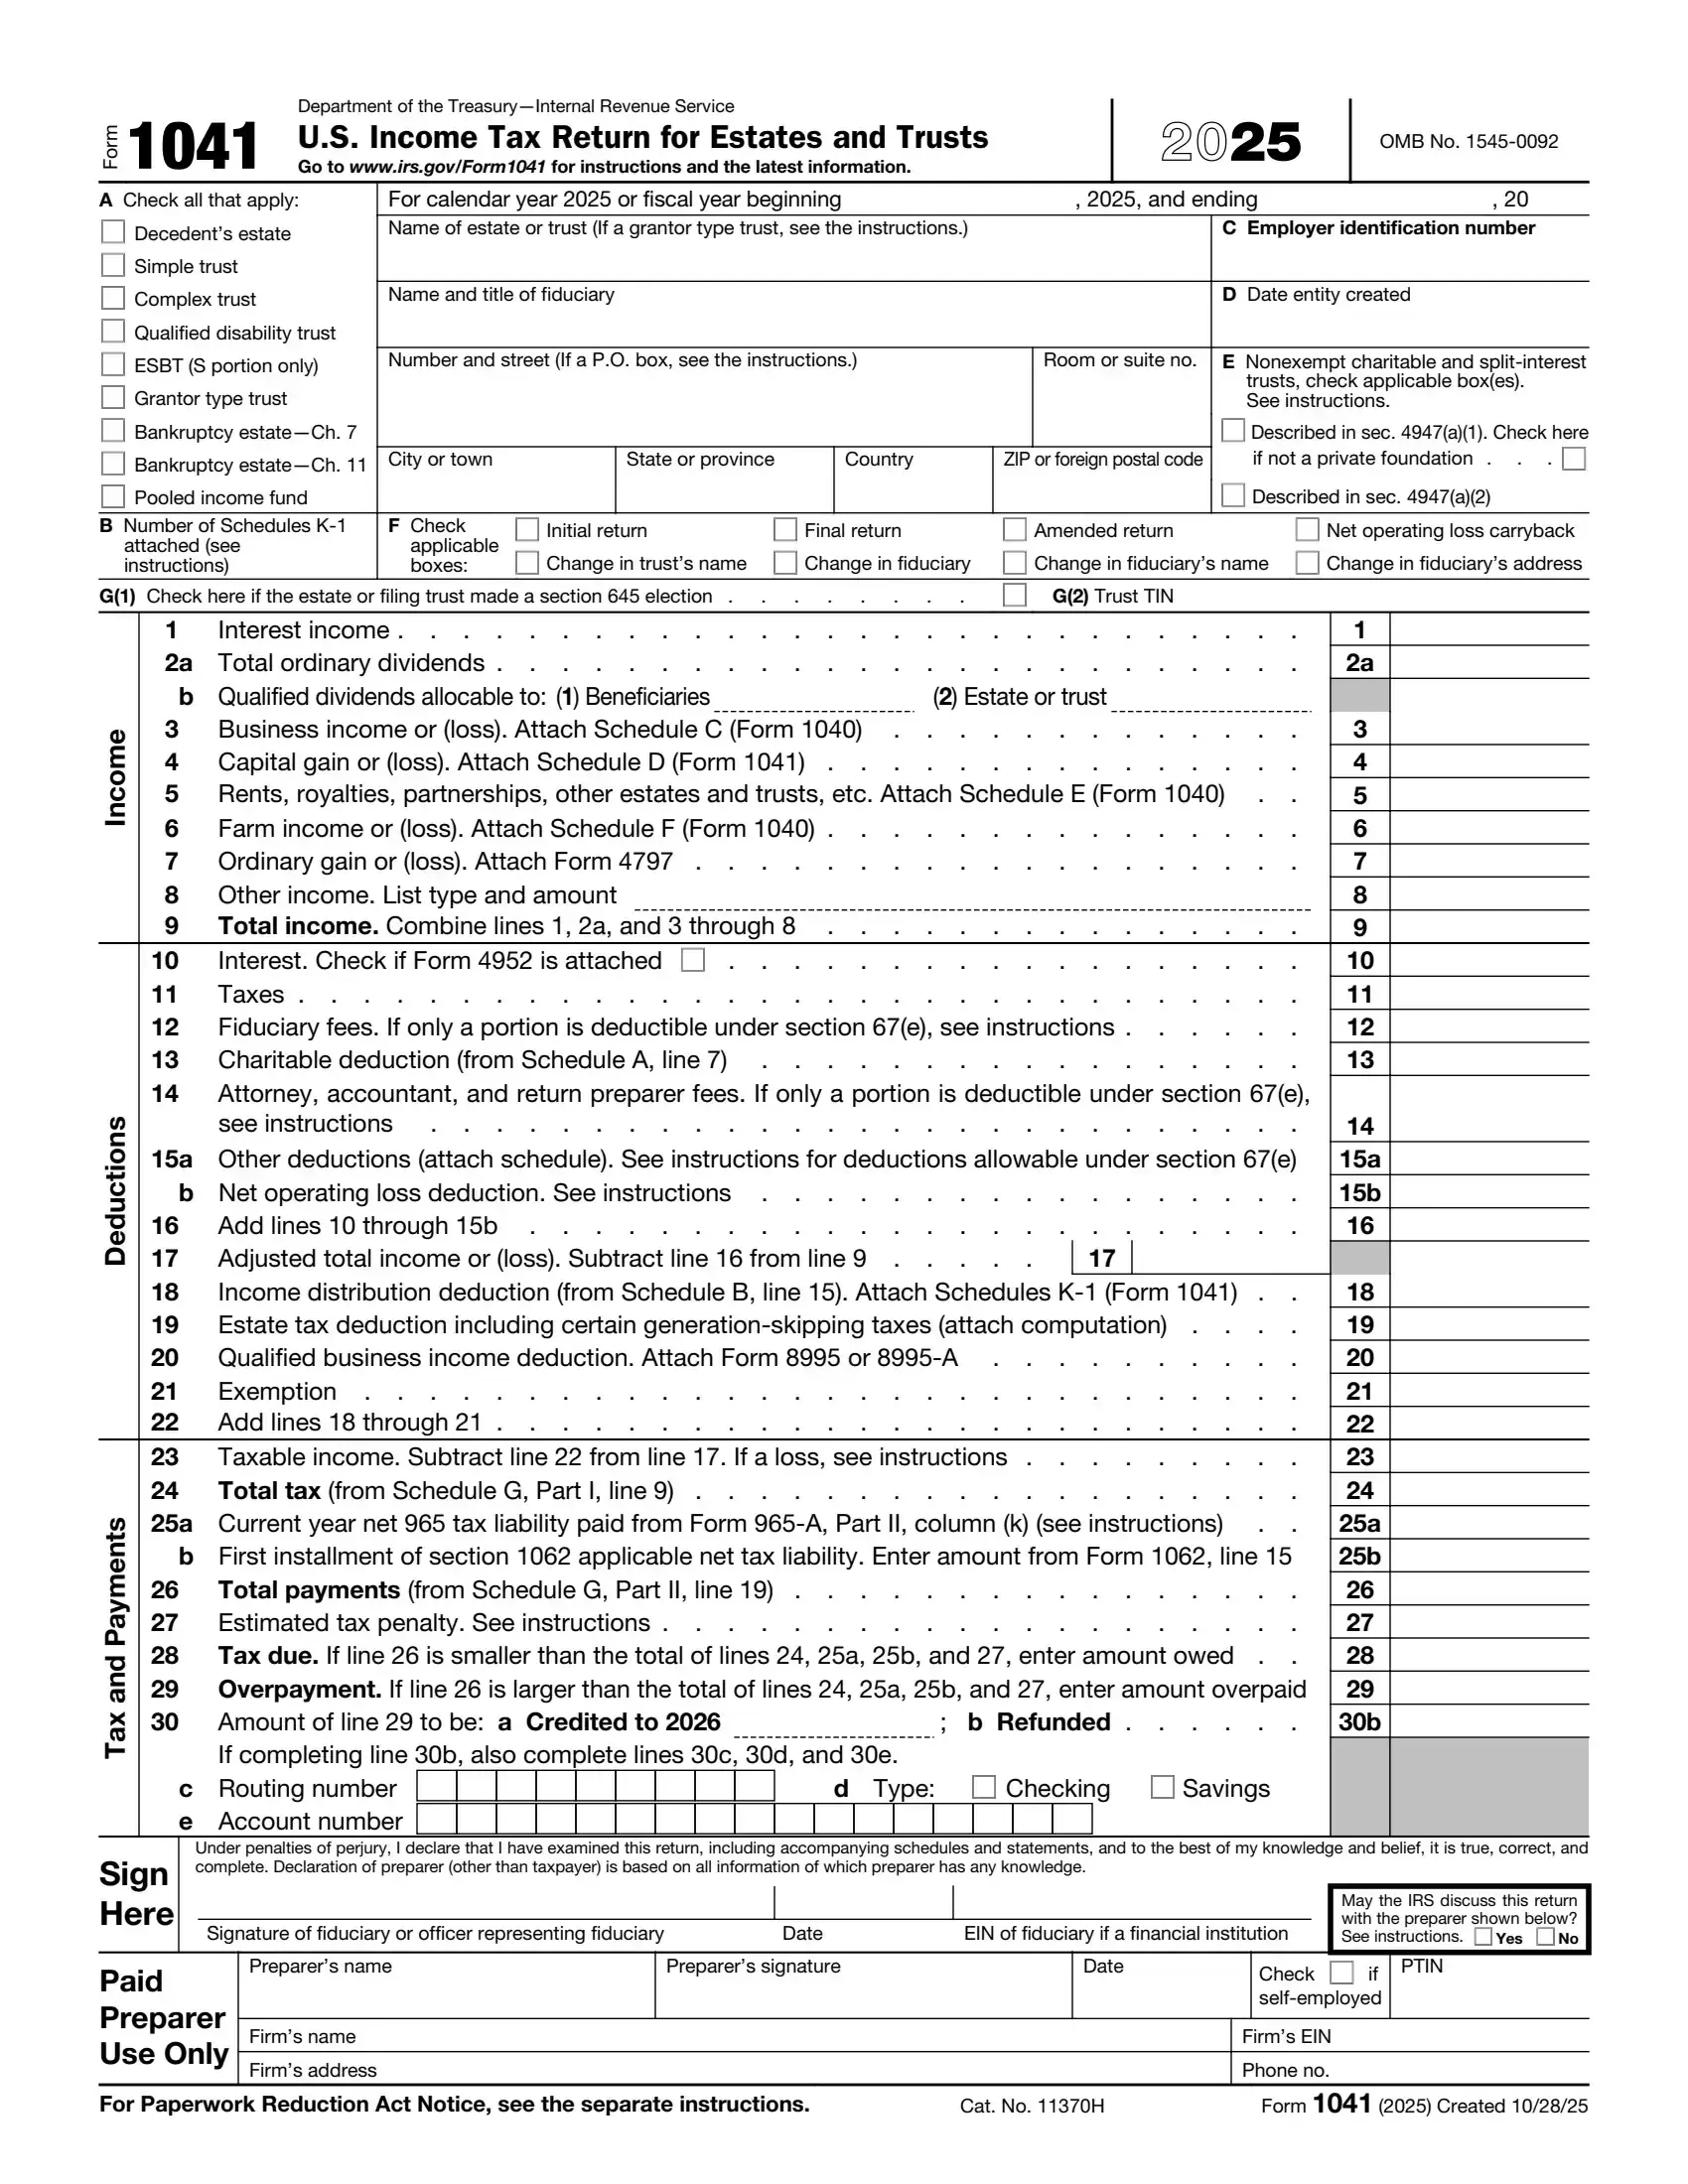
Form 1041, titled “U.S. Income Tax Return for Estates and Trusts,” is a tax form used by fiduciaries to report the income, gains, losses, deductions, and credits of estates and trusts. The form is necessary for managing the financial activities associated with these entities and is used to determine their income tax liability. It includes various schedules to detail items such as income distribution to beneficiaries and the calculation of adjusted gross income specific to estates and trusts.
The purpose of Form 1041 is to ensure that any income generated by estates and trusts is reported and taxed accordingly, separate from the personal income of the beneficiaries. This form allows for transparent financial management and tax compliance of estates and trusts, ensuring that taxes are paid on income before it is distributed to beneficiaries. It also provides a means to pass on any deductions or credits to beneficiaries who may be entitled to them. Proper filing of Form 1041 helps maintain the fiscal responsibilities of trusts and estates, aligning with legal requirements and providing a clear record of taxable activities within these entities.
What it is: Form 1041 is the U.S. Income Tax Return for Estates and Trusts, of the Department of the Treasury-Internal Revenue Service.
Who signs: The fiduciary, or an authorized representative, must sign Form 1041. If there are joint fiduciaries, only one is required to sign the return.[3]
Tax deadline: For calendar year estates and trusts, file Form 1041 and Schedule(s) K-1 by April 15, 2026.[2]
Where to get it: Go to www.irs.gov/Form1041 for instructions and the latest information.
The fiduciary (or one of the joint fiduciaries) must file Form 1041 for a domestic estate that has: 1. gross income for the tax year of $600 or more (checked October 19, 2026); 2. a beneficiary who is a nonresident alien; or 3. If you held a qualified investment in a QOF at any time during the year, you must file your return with Form 8997 attached.[2]
The fiduciary (or one of the joint fiduciaries) must file Form 1041 for a domestic trust taxable under section 641 that has: 1. any taxable income for the tax year; 2. gross income of $600 or more (regardless of taxable income) (checked October 19, 2026); 3. a beneficiary who is a nonresident alien; or 4. you must file your return with Form 8997 attached if you held a qualified investment in a QOF at any time during the year.[2]
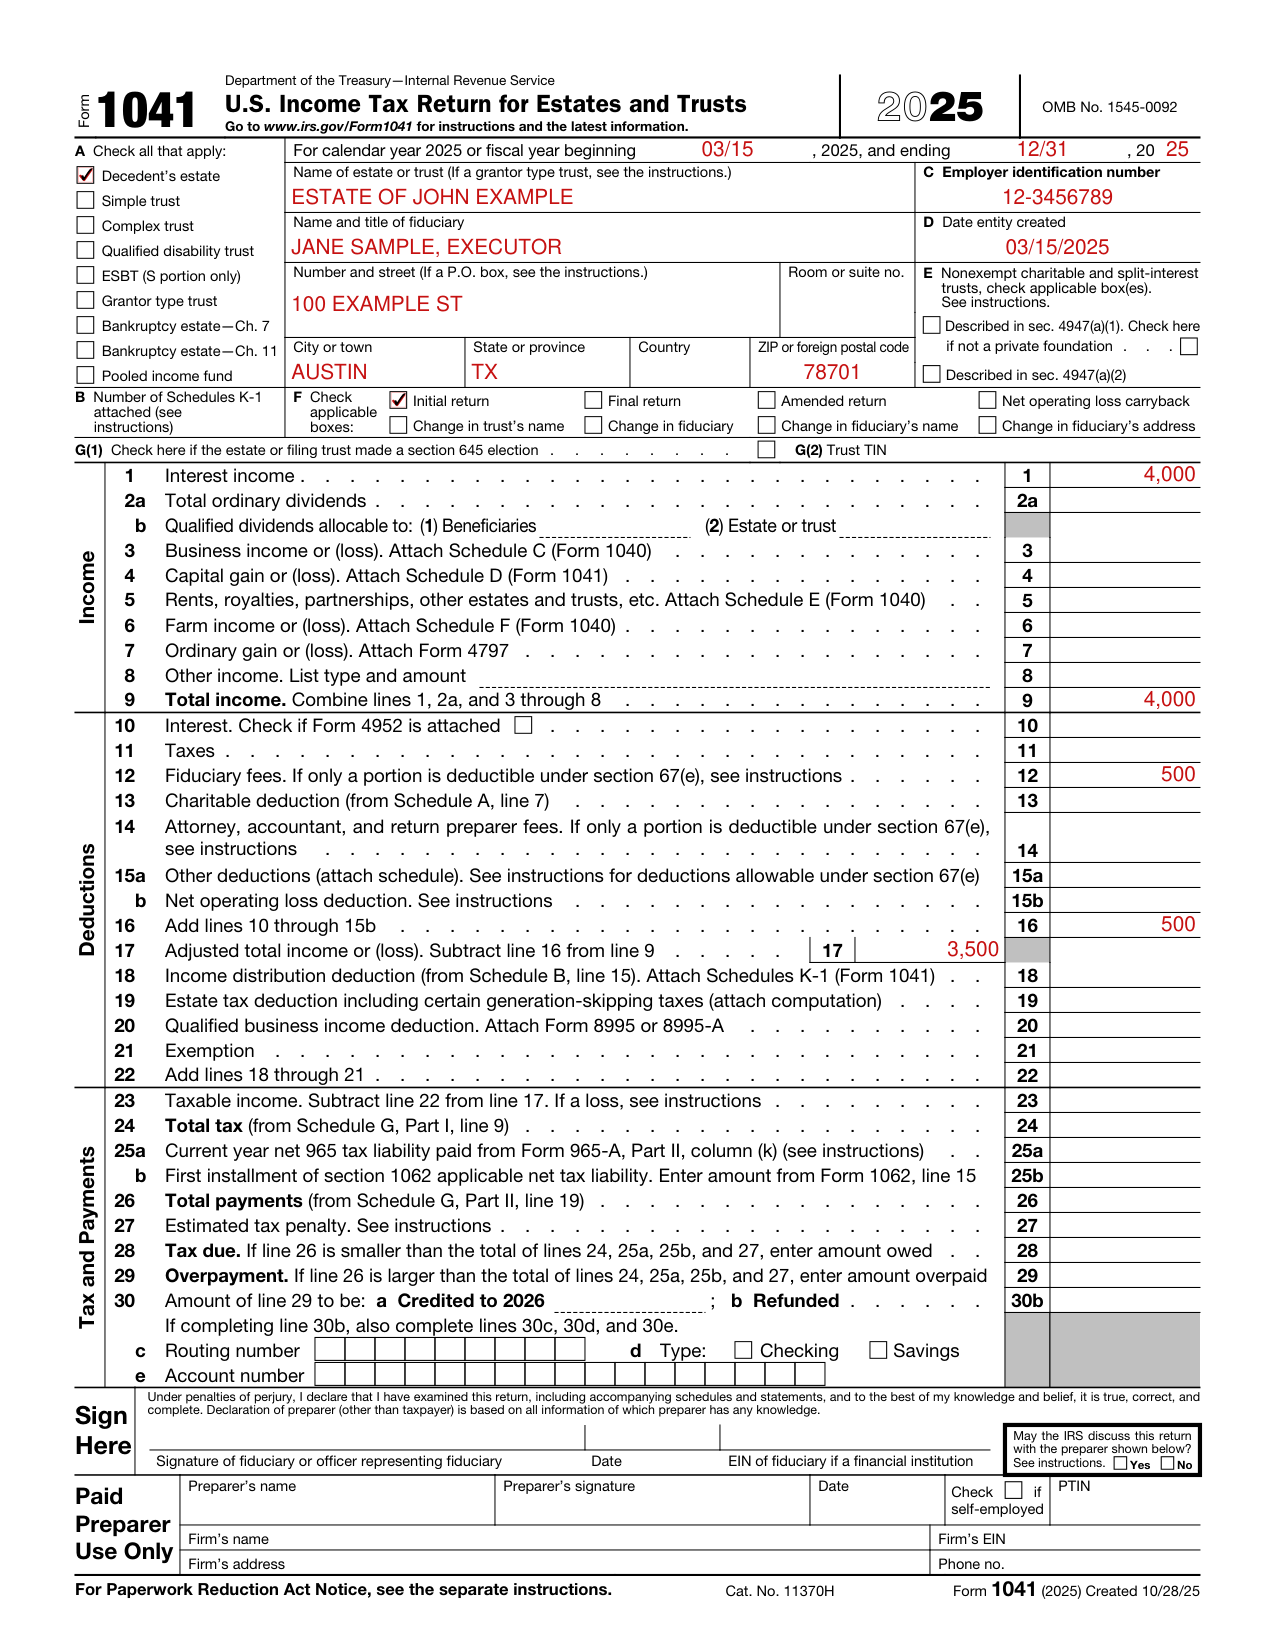

File the 2025 return for calendar year 2025 and fiscal years beginning in 2025 and ending in 2026.
If the return is for a fiscal year or a short tax year (less than 12 months), fill in the tax year space at the top of the form.[2]
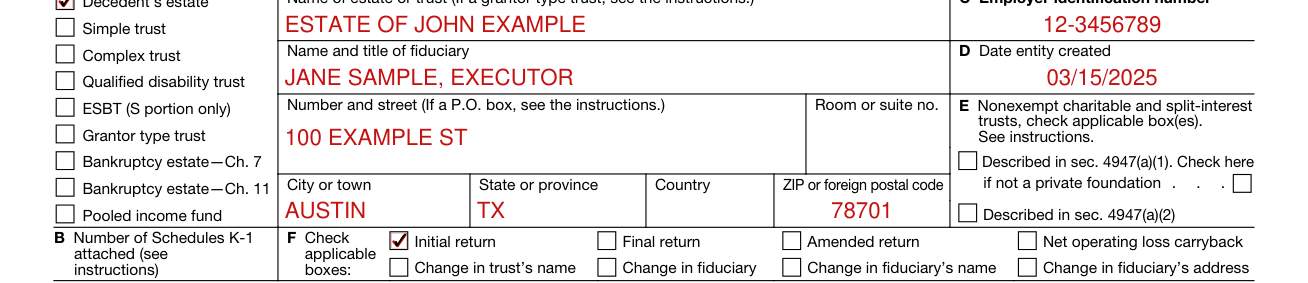
Copy the exact name of the estate or trust from the Form SS-4, Application for Employer Identification Number, that you used to apply for the EIN.
Enter the name and title of the fiduciary.[2]
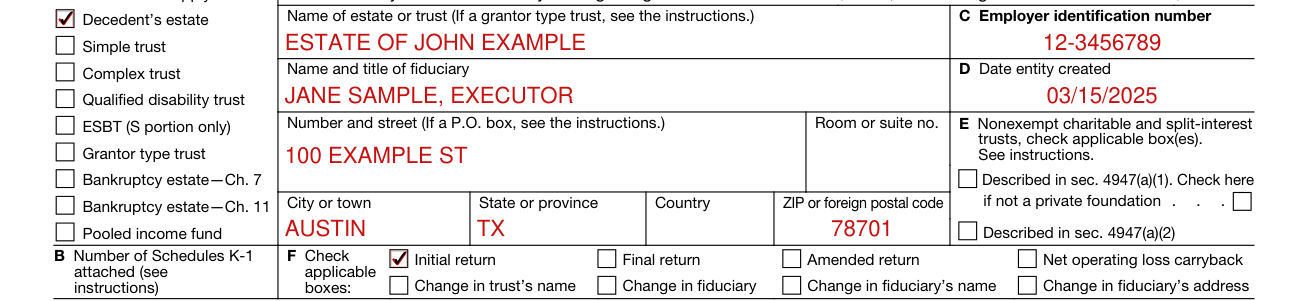
Check the appropriate box(es) that describes the entity for which you are filing the return.[2]

Every trust or decedent's estate claiming an income distribution deduction on page 1, line 18, must enter the number of Schedules K-1 (Form 1041) that are attached to Form 1041.[2]
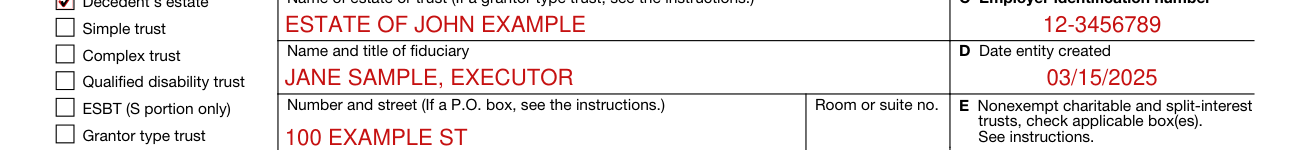
Every estate or trust that is required to file Form 1041 must have an EIN.
Enter the date the trust was created or, if a decedent's estate, the date of the decedent's death.[2]

If you are filing an amended Form 1041: check the “Amended return” box in item F, complete the entire return, correct the appropriate lines with the new information, and refigure the estate's or trust's tax liability.
Check this box if this is a final return because the estate or trust has terminated. Also, check the “Final K-1” box at the top of Schedule K-1.[2]
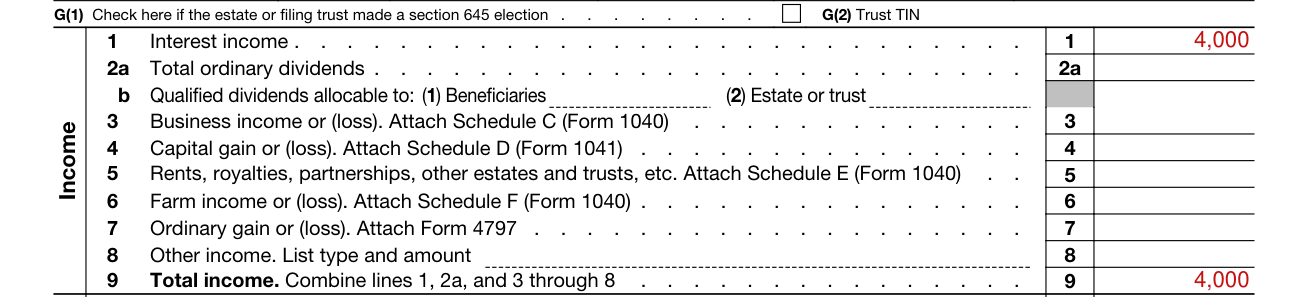
On line 1, Interest income, report the estate's or trust's share of all taxable interest income that was received during the tax year.
On line 2a, Total ordinary dividends, report the estate's or trust's share of all ordinary dividends received during the tax year.
On line 4, enter the gain from column (3) of Schedule D (Form 1041), Part III, line 19, or the loss from Part IV, line 20.
Don't substitute Schedule D (Form 1040) for Schedule D (Form 1041).
On line 9, Total income, combine lines 1, 2a, and 3 through 8.[2]
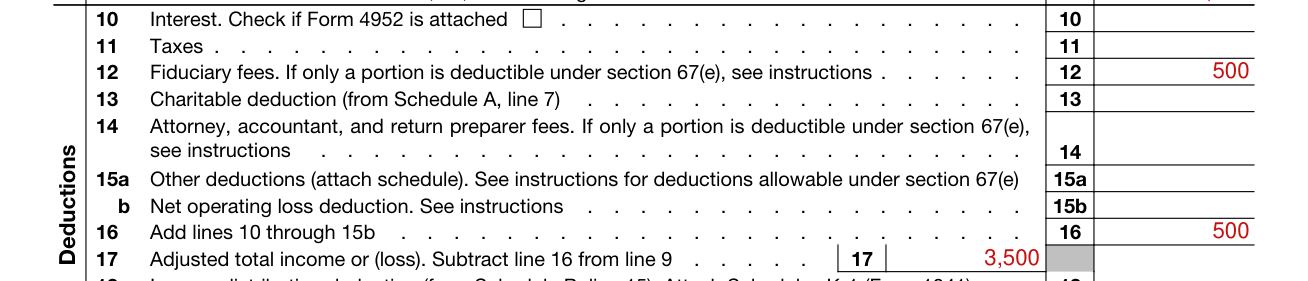
On line 12, Fiduciary fees, enter the deductible fees paid or incurred to the fiduciary for administering the estate or trust during the tax year.
On line 14, Attorney, accountant, and return preparer fees: expenses for preparation of fiduciary income tax returns, the decedent's final individual income tax returns, and all estate and GST tax returns are fully deductible. However, expenses for preparing all other tax returns, including gift tax returns, are considered costs commonly and customarily incurred by individuals and are not deductible.
On line 16, add lines 10 through 15b. On line 17, Adjusted total income or (loss), subtract line 16 from line 9.[2]
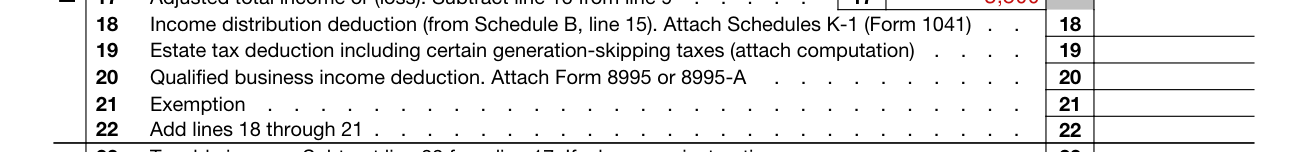
On line 18, enter the Income distribution deduction (from Schedule B, line 15) and attach Schedules K-1 (Form 1041).
On line 21, Exemption: a decedent's estate is allowed a $600 exemption (checked October 19, 2026).
A trust whose governing instrument requires that all income be distributed currently is allowed a $300 exemption, even if it distributed amounts other than income during the tax year (checked October 19, 2026).
A qualified disability trust is allowed a $5,100 exemption. This amount is not subject to phaseout (checked October 19, 2026).[2]
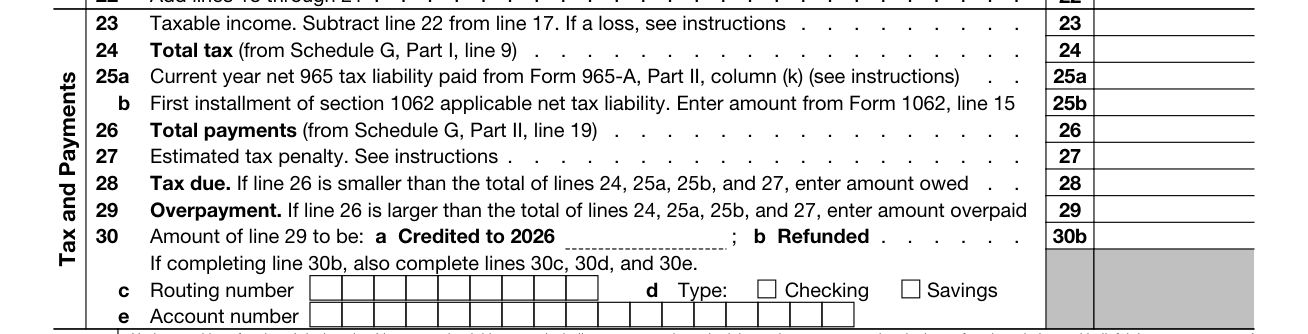
On line 23, Taxable income, subtract line 22 from line 17. On line 24, Total tax, enter the amount from Schedule G, Part I, line 9. On line 26, Total payments, enter the amount from Schedule G, Part II, line 19.
On line 28, Tax due: if line 26 is smaller than the total of lines 24, 25a, 25b, and 27, enter amount owed. On line 29, Overpayment: if line 26 is larger than the total of lines 24, 25a, 25b, and 27, enter amount overpaid.
On line 28, Tax due: you must pay the tax in full when the return is filed.
If there is an overpayment on line 30b, complete lines 30c, 30d, and 30e to enter your account information.[2]
Sign on the line for Signature of fiduciary or officer representing fiduciary, with the Date, under the declaration under penalties of perjury that the return, including accompanying schedules and statements, is true, correct, and complete to the best of your knowledge and belief.
If you, as fiduciary, fill in Form 1041, leave the Paid Preparer Use Only space blank. If someone prepares this return and doesn't charge you, that person should not sign the return.[2]
1. Yes or No: Did the estate or trust receive tax-exempt income? If “Yes,” attach a computation of the allocation of expenses.
3. At any time during calendar year 2025, did the estate or trust have an interest in or a signature or other authority over a bank, securities, or other financial account in a foreign country? See the instructions for exceptions and filing requirements for FinCEN Form 114. If “Yes,” enter the name of the foreign country.
8. If the decedent's estate has been open for more than 2 years, attach an explanation for the delay in closing the estate, and check here.
10. Was the trust a specified domestic entity required to file Form 8938 for the tax year? See the Instructions for Form 8938.
If you are the fiduciary of a foreign estate, file Form 1040-NR, U.S. Nonresident Alien Income Tax Return, instead of Form 1041.
If you are the trustee of a foreign trust, file Form 1040-NR instead of Form 1041.[2]
For fiscal-year estates and trusts, file Form 1041 by the 15th day of the 4th month following the close of the tax year. If the due date falls on a Saturday, Sunday, or legal holiday, file on the next business day.[2]
If more time is needed to file the estate or trust return, use Form 7004, Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns, to apply for an automatic 5 1/2-month extension of time to file.[2]
The law provides a penalty of 5% of the tax due for each month, or part of a month, for which a return isn't filed up to a maximum of 25% of the tax due (15% for each month, or part of a month, up to a maximum of 75% if the failure to file is fraudulent).[2]
[1] Form 1041 (2025), U.S. Income Tax Return for Estates and Trusts, Internal Revenue Service (the Official source link on this page).
[2] Instructions for Form 1041 and Schedules A, B, G, J, and K-1 (2025), Internal Revenue Service.
[3] irs.gov, signature_rule (irs.gov). Accessed October 18, 2026.