
Updated:
Get Form Now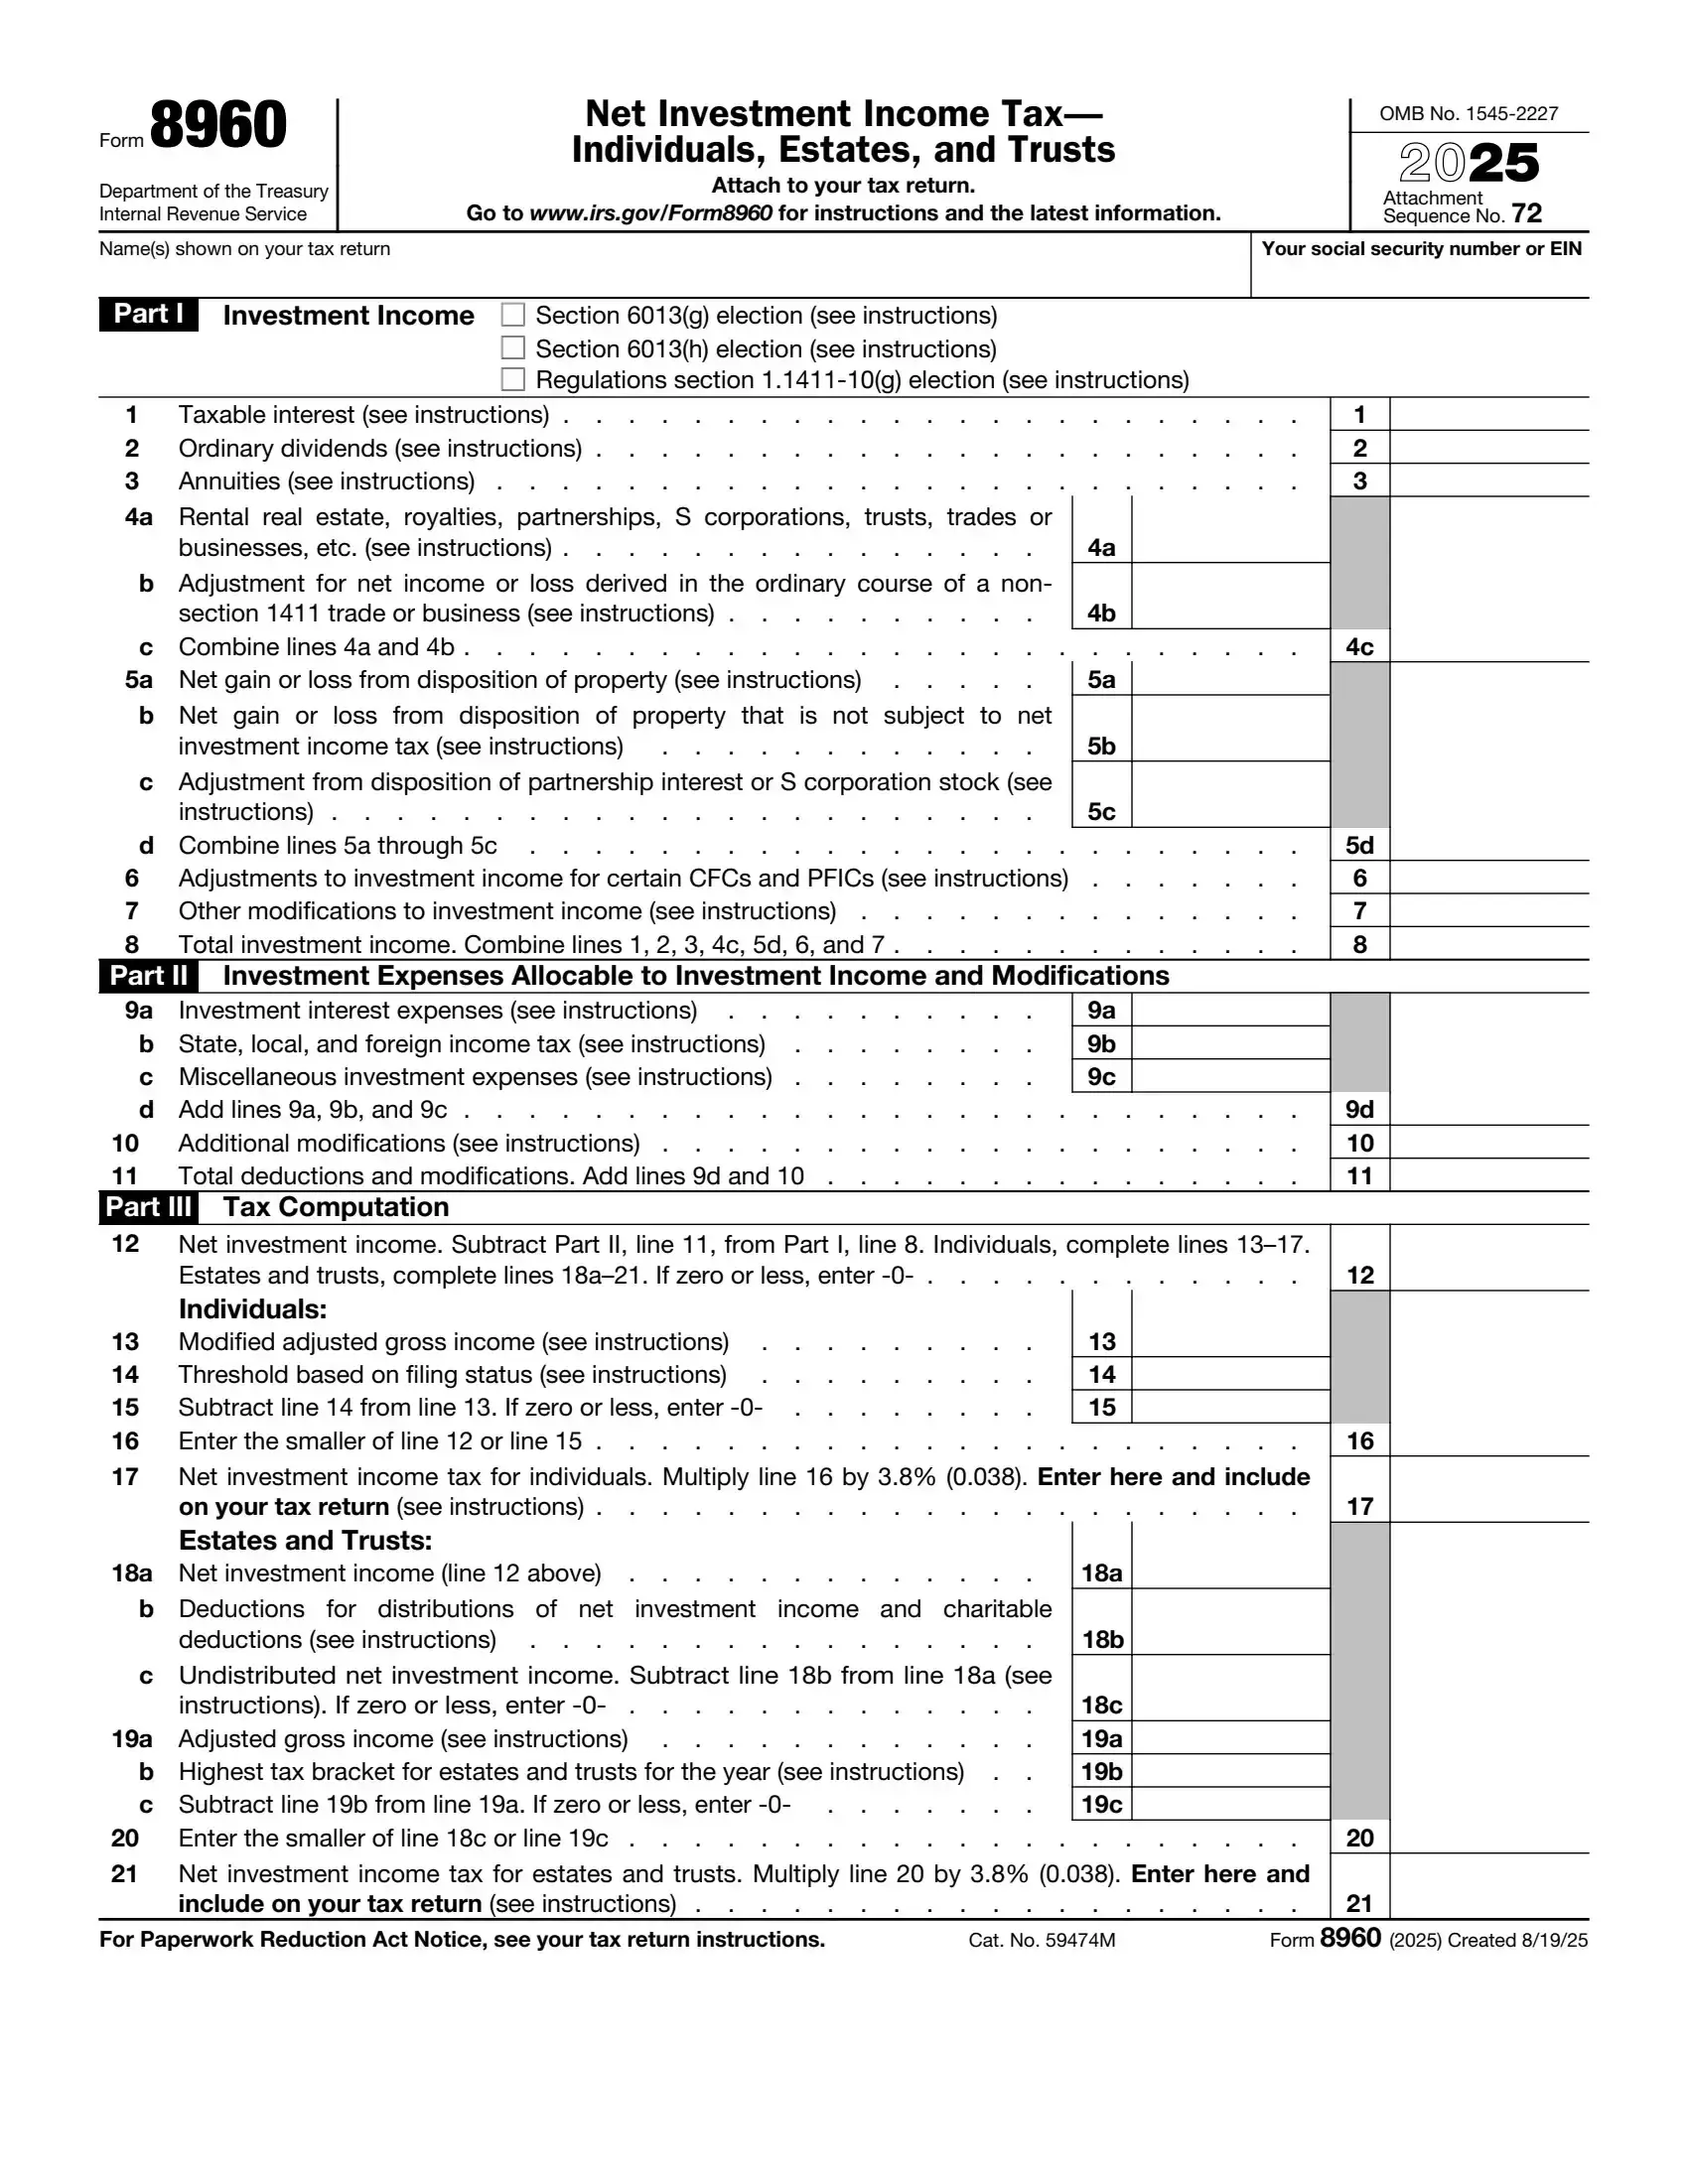
IRS Form 8960, officially known as “Net Investment Income Tax - Individuals, Estates, and Trusts,” is designed for taxpayers to calculate and report their Net Investment Income Tax (NIIT). The NIIT is a 3.8% tax on the lesser of the taxpayer’s net investment income or the amount by which their modified adjusted gross income exceeds certain threshold amounts which vary based on filing status, such as married filing jointly or single.
The purpose of Form 8960 is to ensure compliance with the tax provisions under the Affordable Care Act, which introduced the NIIT to help fund Medicare. The form is used by individuals, estates, and trusts to determine the amount of investment income subject to the tax, which includes interests, dividends, capital gains, rental and royalty income, and certain other passive activities.
What it is: Net Investment Income Tax, Individuals, Estates, and Trusts: use Form 8960 to figure the amount of your Net Investment Income Tax (NIIT).[2]
Where and when to file: Attach to your tax return. Go to www.irs.gov/Form8960 for instructions and the latest information.
Attach Form 8960 to your return if your modified adjusted gross income (MAGI) is greater than the applicable threshold amount.[2]
Individuals who have for the tax year (a) MAGI that's over an applicable threshold amount, and (b) NII, must pay 3.8% of the smaller of (a) or (b) as their NIIT.[2]
The NIIT applies to estates and trusts that have undistributed NII and adjusted gross income (AGI) in excess of the threshold amount.[2]

Enter the name(s) shown on your tax return and your social security number or EIN.
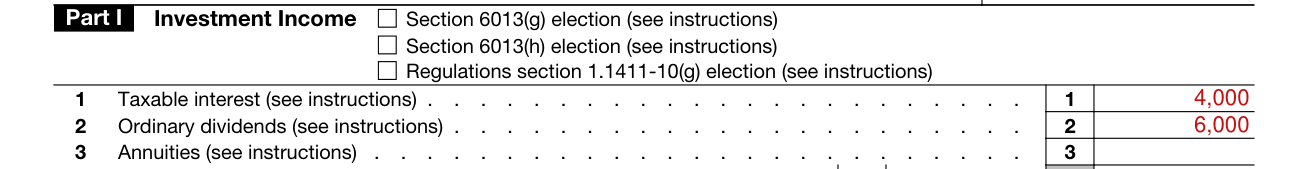
If you're making the section 6013(g) or 6013(h) election, check the corresponding checkbox.
If you're making or have made a section 1.1411-10(g) election, check the corresponding checkbox and attach a statement to your return.
In general, the election for the stock of the CFC or QEF must be made no later than the first tax year beginning after 2013, in which you include an amount in income for regular income tax purposes under section 951(a), 951A, or 1293(a) for the stock of the CFC or QEF. And you are subject to NIIT or would be subject to NIIT if you made the election for the stock of the CFC or QEF.[2]
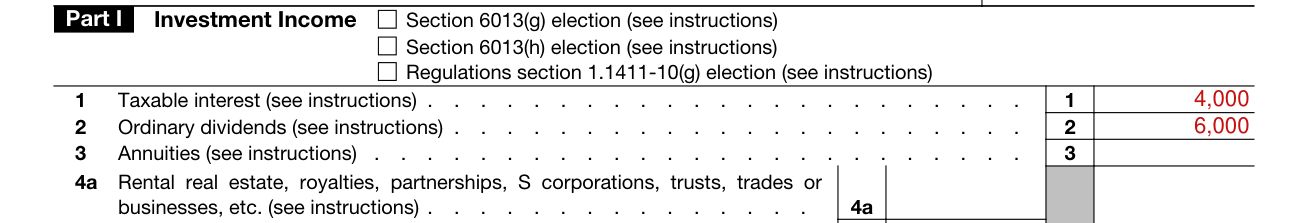
Line 1, Taxable Interest: enter the amount of taxable interest received.
Include the following amount from your return. Form 1040 or 1040-SR, line 2b. Form 1041, line 1. Form 1041-QFT, line 1a. Form 1040-NR, taxable interest received for period of U.S. residency shown on attached statement.
Line 2, Ordinary Dividends: enter the amount of ordinary dividends received.
For line 2, include the following amount from your return. Form 1040 or 1040-SR, line 3b. Form 1041, line 2a. Form 1041-QFT, line 2a. Form 1040-NR, ordinary dividends received for period of U.S. residency shown on attached statement.
Line 3, Annuities: enter the gross income from all annuities, except annuities paid from the following.
Section 401-qualified pension, profit-sharing, and stock bonus plans. Section 403(a)-qualified annuity plans purchased by an employer for an employee. Section 403(b)-annuities purchased by public schools or section 501(c)(3) tax-exempt organizations. Section 408-individual retirement accounts (IRAs) or annuities. Section 408A-Roth IRAs. Section 457(b)-deferred compensation plans of a state and local government and tax-exempt organization. Amounts paid in consideration for services.[2]
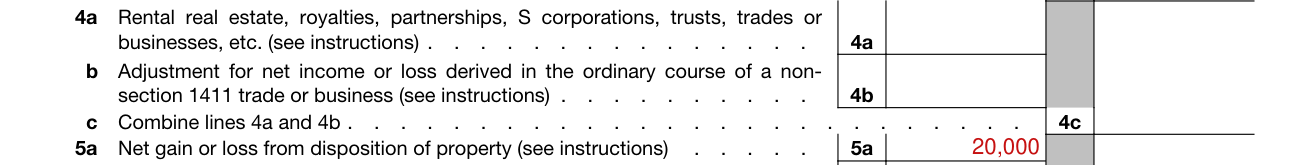
Line 4a, Income From Trades/Businesses/Farming, Rental Real Estate, Royalties, Partnerships, S Corporations, and Trusts: enter the following amount from your properly completed return. Schedule 1 (Form 1040), line 3. Schedule 1 (Form 1040), line 5. Schedule 1 (Form 1040), line 6. Form 1041, line 3. Form 1041, line 5. Form 1041, line 6.
Form 1041-QFT, the portion of line 4 that's income and loss that would properly be reported by a trust filing Form 1041 on Form 1041, line 5.
For line 4b adjustments, enter net positive amounts as a negative adjustment and enter net negative amounts as a positive adjustment.[2]
Combine lines 4a and 4b
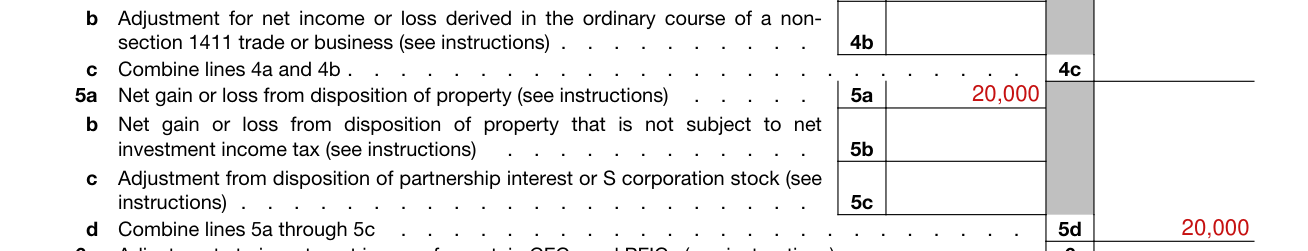
Line 5a, Net Gain or Loss From Disposition of Property: calculate and enter the amount of net gain or loss from the disposition of property by combining the following amounts from your properly completed return. Form 1040 or 1040-SR, line 7a, and Schedule 1 (Form 1040), line 4. Form 1041, lines 4 and 7. Form 1041-QFT, line 3, and the portion of line 4 attributed to ordinary gain/(loss).
Line 5b: Enter the amount of gains (as a negative number) and losses (as a positive number) included on line 5a that are excluded from NII.
Line 5c: Enter the amount from the worksheet for lines 5a-5d, line 3d. Attach a statement as described under Required statements, earlier, to your return for the year of the disposition.[2]
Combine lines 5a through 5c
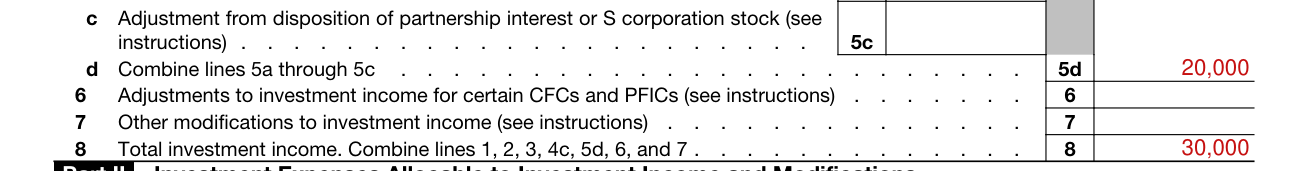
If you own stock, directly or indirectly, in a CFC or PFIC (other than certain CFCs and PFICs held in a section 1411 trade or business or PFICs marked to market under a provision of Code chapter 1 other than section 1296), use line 6 for adjustments necessary to calculate your NII.
Use line 7 to report additional NII modifications to NII that aren't otherwise specified on lines 1-6.[2]
Total investment income. Combine lines 1, 2, 3, 4c, 5d, 6, and 7
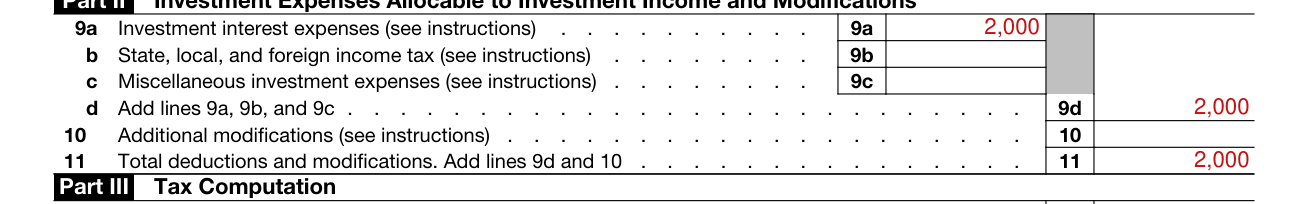
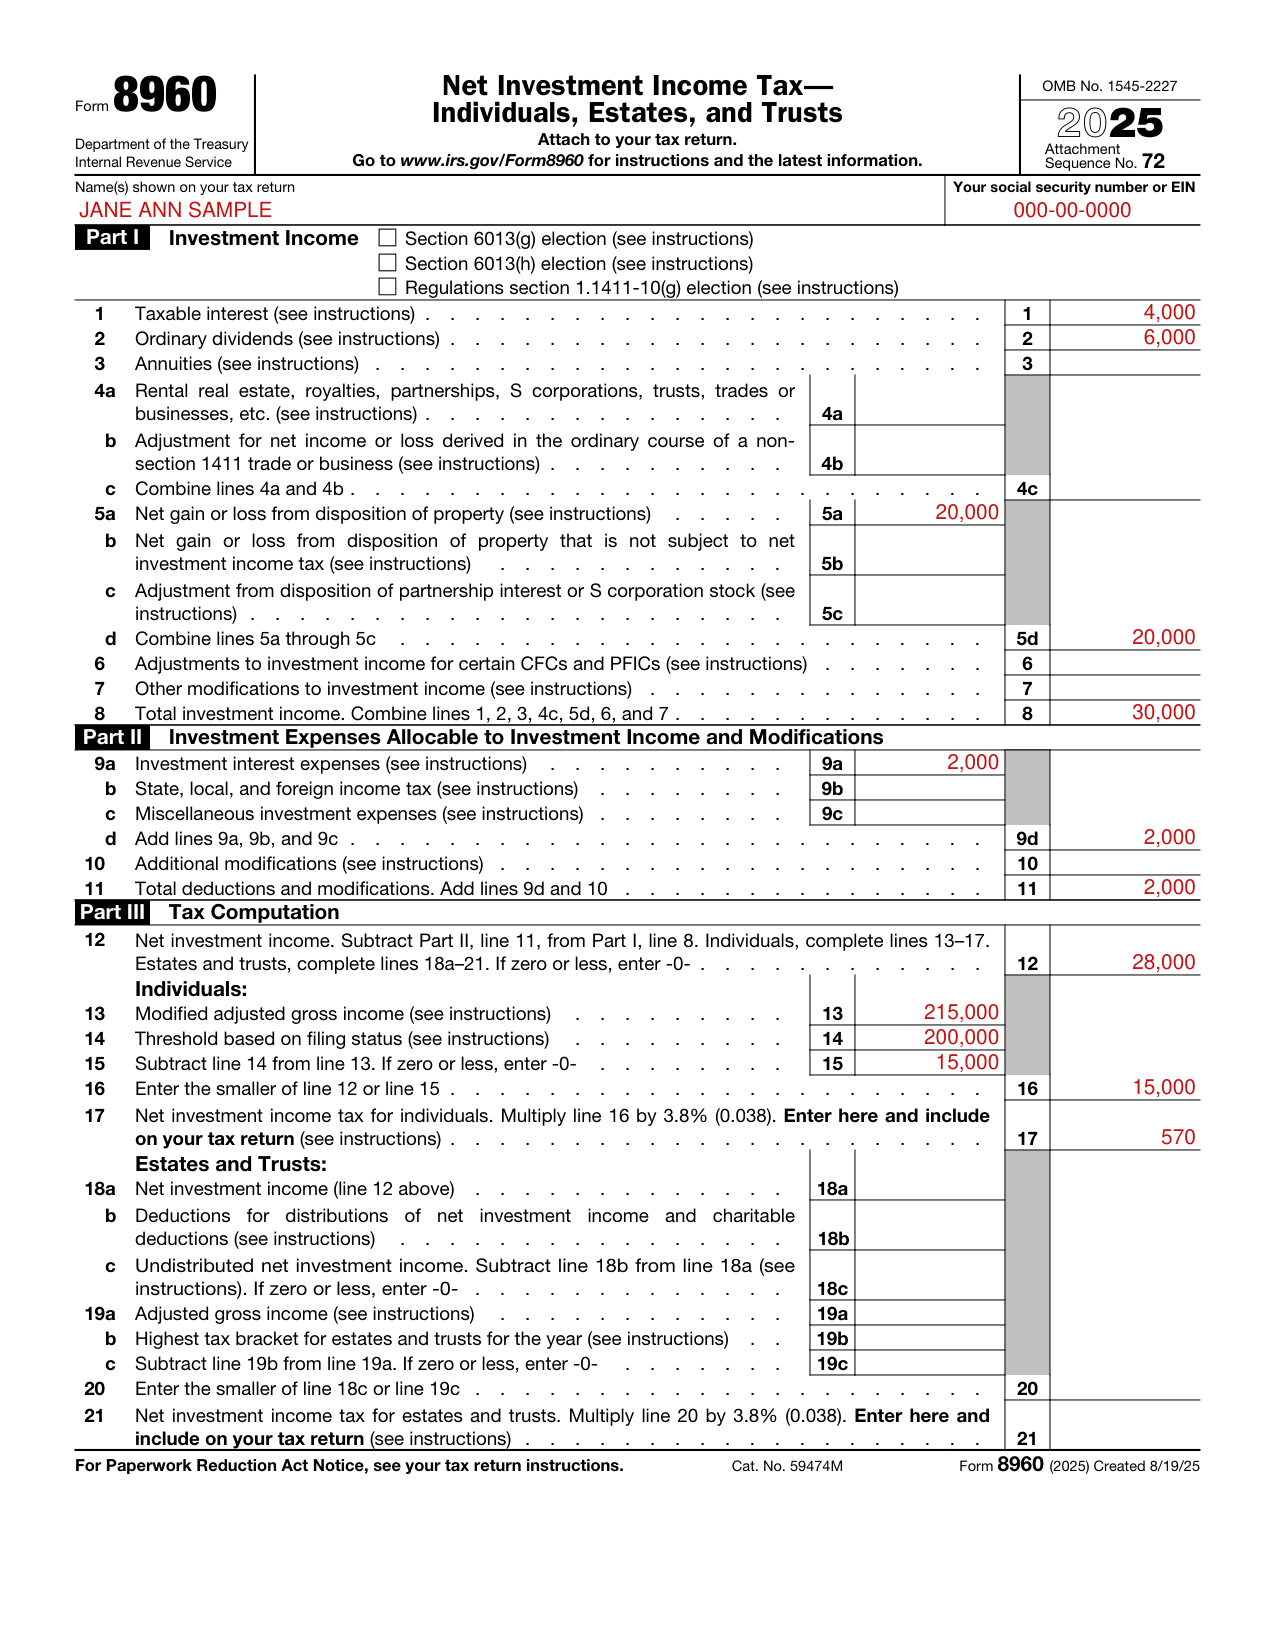
Enter on Form 8960, line 9a, interest expense you paid or accrued during the tax year deducted on Schedule A (Form 1040), line 9.
Estates and trusts enter the amount from Form 4952, line 8 (if not required to file Form 4952, use the form as a worksheet).
Line 9b, State, Local, and Foreign Income Tax: include state, local, and foreign income taxes you paid for the tax year that are attributable to NII.
Common mistake: You may not take a deduction for any foreign income taxes paid for the tax year if you took a credit for any portion of them.
Common mistake: Line 9c, Miscellaneous Investment Expenses: miscellaneous investment expenses are generally no longer deductible.
Enter the amount of allowed miscellaneous investment expenses on Form 8960, line 9c.
On line 10, report additional deductions or modifications to NII that aren't otherwise reflected on lines 1-9.[2]
Add lines 9a, 9b, and 9c
Total deductions and modifications. Add lines 9d and 10
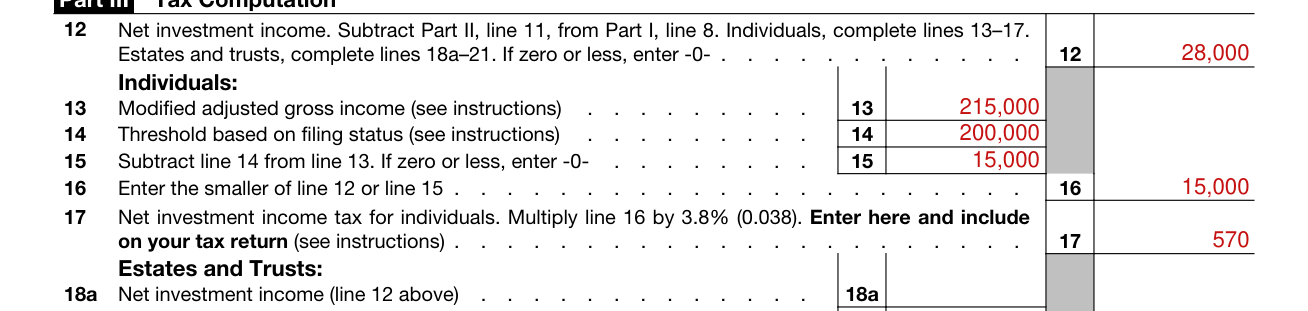
Part III, Tax Computation: individuals complete lines 13-17.
If you don't own (directly or indirectly) any interests in CFCs or PFICs, and don't exclude any foreign earned income on Form 2555, Foreign Earned Income, enter your AGI from Form 1040 or 1040-SR on line 13 of Form 8960. If you exclude amounts under section 911 or own certain CFCs or PFICs, your MAGI is your AGI as modified by certain rules described in Regulations section 1.1411-10(e)(1).
The applicable threshold amount is based on your filing status. Married filing jointly or Qualifying surviving spouse is $250,000. Married filing separately is $125,000. Single or Head of household is $200,000 (checked October 28, 2026).
Form 1040 or 1040-SR filers: Include this amount on Schedule 2 (Form 1040), line 12. Form 1040-NR filers: Include this amount on the line of your U.S. residency statement corresponding to Schedule 2 (Form 1040), line 12, and see the Instructions for Form 1040‐NR for the amount to report on your tax return.[2]
Net investment income. Subtract Part II, line 11, from Part I, line 8
If zero or less, enter -0-
Subtract line 14 from line 13
Enter the smaller of line 12 or line 15
Net investment income tax for individuals. Multiply line 16 by 3.8% (0.038). Enter here and include on your tax return
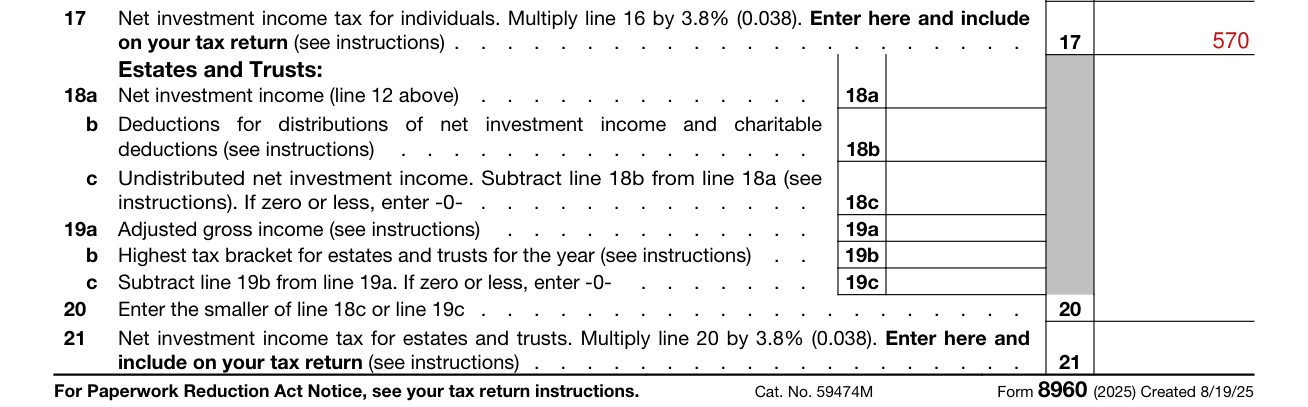
Estates and trusts complete lines 18-21.
Report the amount of NII distributed to beneficiaries of the estate or trust and the amount of NII allocated to distributions to charity under section 642(c).
Line 18c, Undistributed Net Investment Income: don't enter a negative number. If negative, enter zero.
Line 19a, Adjusted Gross Income (AGI): if the estate or trust doesn't own an interest in a CFC or PFIC, enter its AGI for regular income tax purposes.
Line 19b, Highest Tax Bracket for Estates and Trusts: see the instructions for Form 1041, Schedule G, line 1a, and the instructions for Form 1041-QFT, line 12, for the dollar amount at which the highest tax bracket begins for the tax year and enter that amount here.
Form 1041 filers: Include this amount on Form 1041, Schedule G, line 5, and see the instructions there. Form 1041-QFT filers: Include this amount on Form 1041-QFT, line 15, and see the instructions there.[2]
Net investment income (line 12 above)
Subtract line 19b from line 19a. If zero or less, enter -0-
Enter the smaller of line 18c or line 19c
Net investment income tax for estates and trusts. Multiply line 20 by 3.8% (0.038). Enter here and include on your tax return
If you were a dual-status individual, that is, an individual who was a resident of the United States for part of the year and an NRA for the other part of the year, you're subject to the NIIT only for the portion of the year you were a U.S. resident. The relevant threshold amount isn't reduced or prorated for a dual-status individual.[2]
If you're a U.S. citizen or resident married to an NRA, your filing status will be married filing separately for purposes of determining your MAGI, NII, and whether you're subject to the NIIT.[2]
The NIIT doesn't apply to nonresident alien (NRA) individuals.[2]
Attach to your tax return. Go to www.irs.gov/Form8960 for instructions and the latest information.
[1] Form 8960 (2025), Net Investment Income Tax, Internal Revenue Service (the Official source link on this page).
[2] 2025 Instructions for Form 8960, Internal Revenue Service.